
Radiopharmaceutical Injectors Market Report Scope and Overview
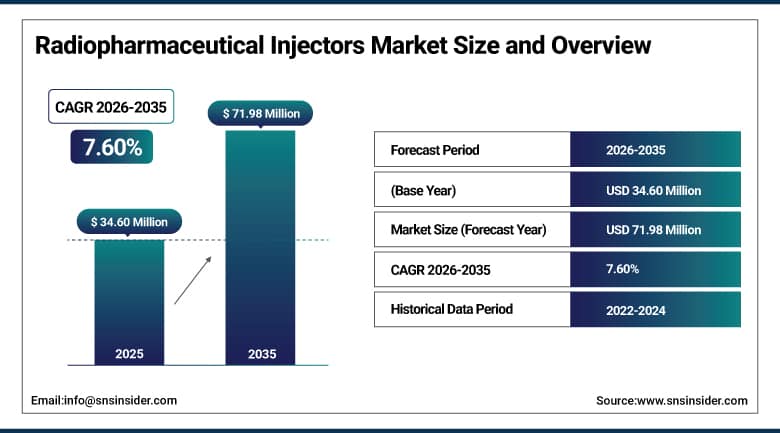
The Radiopharmaceutical Injectors Market was valued at USD 34.60 Million in 2025 and is estimated at USD 37.23 Million in 2026. The market is forecast to reach USD 71.98 Million by 2035, registering a CAGR of 7.60% from 2026 to 2035. Radiopharmaceutical injectors are shielded manual and automated devices that measure, deliver, and flush radioactive doses for imaging and therapy while limiting staff exposure. North America accounted for the largest regional share at 38.40% in 2025, while Asia Pacific is expected to grow fastest. Demand is shaped by PET scanner installations and the spread of radioligand therapy programs.
To Get More Information On Radiopharmaceutical Injectors Market - Request Free Sample Report
Key Market Trends & Insights:
-
By type: PET injectors held the largest market share of 72.40% in 2025.
-
By operation mode: Automated injectors held the largest market share of 57.40% in 2025.
-
By clinical area: Oncology held the largest market share of 44.60% in 2025.
-
By end user: Hospitals and clinics held the largest market share of 74.80% in 2025.
-
North America accounted for the largest regional share of 38.40% in 2025.
-
Asia Pacific is projected to register the fastest regional CAGR of 10.40% from 2026 to 2035.
-
The U.S. is the leading country market, supported by a large installed base of PET centers and a growing radioligand therapy network.
Growth Outlook
Nuclear medicine is moving from a diagnostic specialty to a treatment platform, and that shift raises the value of every device in the dose chain. Radioligand therapies that deliver lutetium-177 or radium-223 to tumors now treat prostate cancer and neuroendocrine tumors, and the Food and Drug Administration expanded the label of a leading prostate therapy on 28 March 2025 to patients earlier in their treatment course. Each new patient group creates demand for shielded handling and accurate dose delivery. Vendors are responding with systems built for therapeutic vials.
Imaging volumes are growing at the same time. Positron emission tomography is used more often in oncology, neurology, and cardiology, and new tracers for prostate cancer, dementia, and infection widen the range of procedures. Hospitals that add scanners need injectors that give consistent doses and cut radiation exposure for technologists, so purchases of automated systems follow the expansion of imaging capacity. Ageing populations and wider screening programs add further procedures, and health systems in emerging economies are building their first nuclear medicine departments, which creates a steady pipeline of new device placements over the coming decade.
Market Dynamics:
Driver: Radioligand Therapy Growth, Staff Safety Rules, and Dose Accuracy Needs Raise Device Demand
Radioligand therapies require careful handling of high-activity doses, often in single vials that must be delivered intravenously over several minutes. Automated injectors and dose delivery stands shield staff, record the delivered activity, and reduce spills, which makes them attractive to centers that are starting therapy programs. As therapy sites multiply, vendors are adding products designed for lutetium-based vials and larger volumes. Dedicated training and validation support from manufacturers helps new therapy centers qualify their staff and begin treating patients sooner, and this reinforces the preference for established suppliers with proven systems. This is especially relevant for new programs in community hospitals.
Radiation safety rules push in the same direction. Employers must keep exposure of technologists and nurses as low as reasonably achievable, and automation lowers hand and whole-body doses compared with manual drawing and injection. Accurate documentation of every dose also supports quality audits, and centers see injectors as a way to improve both safety and workflow efficiency in busy nuclear medicine departments. Hospital administrators also value the legal protection that comes with documented safe practice, and this adds weight to purchasing decisions for shielded equipment across large health systems and academic centers. Insurers and accrediting bodies also expect clear records of safe practice.
Restraint: High Equipment Costs, Small Buyer Base, and Reimbursement Uncertainty Limit Adoption
Automated injectors are specialized, low-volume devices, and their price can be hard to justify for small imaging centers that perform only a few procedures per day. Shielding, calibration, and software validation add to the cost, and many sites continue to use manual syringe shields and lead-lined carts. The buyer base is small, which limits economies of scale and keeps unit prices high. Procurement committees often ask for evidence of payback, and this is difficult when injectors do not generate separate revenue. Some centers also lack trained physicists who can maintain and calibrate advanced systems. Budgets for nuclear medicine are often shared with scanners and software.
Payment policy adds uncertainty. The Centers for Medicare and Medicaid Services published its final outpatient payment rule for 2026 on 21 November 2025, which set separate payment for higher-cost diagnostic radiopharmaceuticals but did not address the equipment used to deliver them. Facilities therefore weigh capital spending carefully, and approval cycles for new devices can be long. Differences in rules between countries add further complexity for suppliers that sell across regions, and smaller hospitals may delay purchases until their therapy volumes are clearly established and stable. Capital planning in public hospitals also tends to be slow and cautious. Procurement rules also add delays.
Opportunity: Theranostics, Single-Dose Systems, and Integrated Dose Software Open New Product Lines
Theranostic programs pair a diagnostic scan with a matching therapy, and they need injectors that can handle both low and high activities within the same department. Vendors that launch systems for single-dose therapy vials, automated sealing, and remote operation can reach new hospital programs. Emerging markets also build their first radioligand centers, which creates demand for complete, validated dose delivery packages. Service contracts, disposable tubing sets, and shielding upgrades provide recurring revenue that smooths the cycle of equipment sales and rewards suppliers with a large installed base in hospitals. Hospitals prefer suppliers that can support equipment for many years. Long product life helps.
Integration with software is another opening. Injectors that connect to dose calibrators, scheduling systems, and electronic records can log activity, patient identity, and time of administration automatically. Such traceability helps with audits and with the growing number of clinical trials that require precise dose records, and it supports service contracts and consumable sales for vendors. Remote monitoring and predictive maintenance can further reduce downtime, which matters greatly to centers where a single delayed dose can disrupt an entire schedule of imaging and treatment appointments. These data tools can also help sites prove compliance to regulators. Remote support tools add value for distant sites and help smaller hospitals maintain compliance.
Market Characteristics & Concentration
The Radiopharmaceutical Injectors Market is Moderately Consolidated. A small group of specialists, including Bayer through its Medrad business, Comecer, Tema Sinergie, Lemer Pax, and Sumitomo Heavy Industries, supply most dedicated systems, while Bracco, Mirion, Eckert & Ziegler, and Curium operate in neighboring parts of the dose chain. Most suppliers are European or Japanese manufacturers with long histories in shielded handling, and they sell directly or through regional distributors that offer installation and service.
Competition centers on shielding performance, dose accuracy, ease of cleaning, software integration, and service coverage. Buyers value local technical support and quick response because downtime delays patient procedures, and vendors compete on training and validation help as much as on the device itself. Product differentiation also comes from compatibility with different isotopes, vial formats, and scanner brands, which matters to buyers that operate mixed fleets and want a single supplier for several modalities.
Barriers to entry are significant. Products must meet radiation safety and medical device requirements, installed bases create switching costs, and relationships with nuclear medicine physicists and radiopharmacists take time to build. Partnerships between device makers and radiopharmaceutical suppliers are increasingly used to secure placements. New entrants usually focus on a single therapy or a regional market, and many choose to partner with established suppliers instead of competing directly across the full range of products.
Analyst Perspective
Radiopharmaceutical injectors are a small but strategic part of the nuclear medicine supply chain, and their growth is tied to the spread of therapy. Demand will shift from simple PET dose handling toward systems that can deliver high-activity therapeutic doses safely and record every step. Vendors with proven shielding, software integration, and service networks in both established and emerging regions will gain the most, while reimbursement and safety regulation will shape how quickly new centers adopt automation. An SNS Insider Analyst, Santosh Bhul, commented, "As radioligand therapy reaches more patients, the injector becomes a safety and quality tool, and suppliers that combine shielding with data capture will set the standard for new centers."
Type Insights
PET injectors accounted for 72.40% of the market in 2025. Fluorine-18 and other positron emitters are used in a large number of scans each day, so imaging centers invest in shielded injection systems that deliver consistent doses and limit staff exposure. Mature technology, a wide installed base, and high procedure volumes keep this type at the center of demand, with steady replacement and service business. Service agreements and replacement of shielding components add to the revenue of this type, and suppliers continue to refine designs that shorten setup time between patients.
Theranostic injectors are the fastest growing type, with a projected CAGR of 11.80% from 2026 to 2035. These systems handle single-dose therapy vials, large volumes, and higher activities, and they suit the rapid expansion of lutetium-based programs. Combined PET and SPECT injectors serve departments that run both modalities and want one device for several isotopes. Vendors also develop remote handling features that allow technologists to stay behind shielding during dose preparation, and these features are becoming a standard request in tenders for new therapy suites. Adoption depends on isotope supply and vial format.
Operation Mode Insights
Automated injectors accounted for 57.40% of the market in 2025. They measure activity, deliver the dose at a programmed rate, flush the line, and record the result without direct handling, which reduces exposure and improves consistency. Centers with high daily volumes and therapy programs favor automation, and vendors support it with software, training, and service contracts that raise recurring revenue. Software features such as automatic calibration checks, dose logging, and integration with hospital records make these devices useful for audits, and many buyers regard them as part of a broader safety program.
Manual injectors remain important in smaller centers and research laboratories, where lead-shielded syringes and simple infusion sets cost less. Semi-automated devices bridge the gap, and manufacturers continue to improve ergonomics and shielding thickness. Over time, rising safety expectations are expected to move more buyers from manual to automated systems. Training of technologists is essential in both modes, and suppliers that provide on-site instruction and recurring competency checks gain a lasting advantage in procurement decisions across hospital groups and imaging networks. Pricing differs widely between the two modes, and this shapes purchasing choices.
Clinical Area Insights
Oncology accounted for 44.60% of the market in 2025. PET imaging guides the staging and monitoring of many cancers, and radioligand therapies are expanding the treatment side. Tracers for prostate cancer and neuroendocrine tumors have increased procedure volumes, and hospitals are adding capacity for both diagnosis and treatment. Cardiology and neurology together make up a large share of the remaining demand, and growth in each area depends on tracer approvals, reimbursement for scans, and the availability of trained imaging staff in hospitals and clinics. Reimbursement is a key factor. Referral patterns matter.
Neurology is the fastest growing clinical area, with a projected CAGR of 10.90% from 2026 to 2035. Amyloid and tau tracers for dementia and new tracers for movement disorders are widening PET use in memory clinics. Cardiology contributes through myocardial perfusion imaging, where rubidium and other agents rely on shielded delivery systems. Other clinical areas, including infection and inflammation imaging, thyroid treatment, and pain palliation, add smaller but steady demand for shielded dose handling in departments that offer a wide range of nuclear medicine services. Specialized services also depend on referral networks.
End User Insights
Hospitals and clinics accounted for 74.80% of the market in 2025. Academic medical centers and community hospitals operate most PET and SPECT scanners, and they hold the radiation safety programs that favor automated dose delivery. Purchases are often made as part of scanner installations or nuclear medicine department upgrades. Group purchasing and service agreements are common in large health systems, which prefer standard equipment across sites to simplify training, spare parts, and compliance with radiation safety programs. Annual budgets and safety audits often trigger replacement of aging units. Standard fleets simplify maintenance.
Research institutions are the fastest growing end user, with a projected CAGR of 9.60% from 2026 to 2035. Preclinical laboratories, tracer development groups, and clinical trial sites need precise dose delivery for new compounds. Diagnostic imaging centers and nuclear pharmacies add steady demand through dispensing and administration of unit doses. Contract research organizations and radiopharmaceutical developers also buy injectors for multi-site trials, where consistent dose delivery supports the quality of data and the comparison of results between centers. Purchasing here is usually project based. Trial sponsors often specify required equipment and calibration procedures, which guides purchasing at participating sites.
Regional Insights:
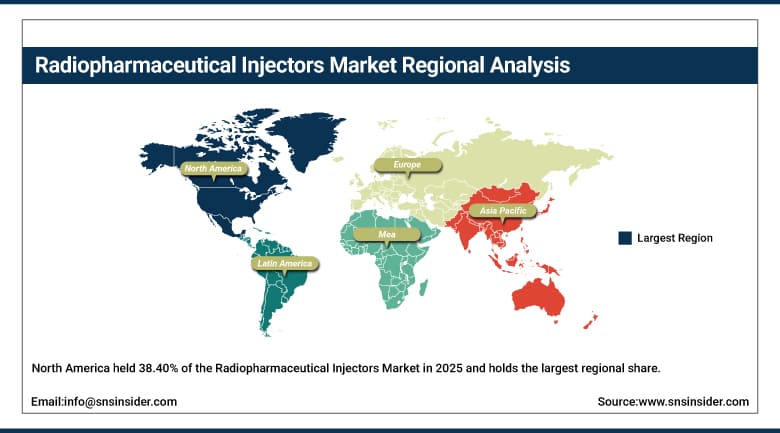
North America held 38.40% of the Radiopharmaceutical Injectors Market in 2025 and holds the largest regional share. The region has a large base of PET and SPECT scanners, a growing network of radioligand therapy sites, and the headquarters of several device and radiopharmaceutical suppliers. Canada adds demand through hospital programs and isotope production. Mexico is reported within Latin America in this analysis, so regional figures here cover the United States and Canada only. Strong clinical research adds further demand.
Get Customized Report as Per Your Business Requirement - Enquiry Now
U.S. Radiopharmaceutical Injectors Market
The U.S. Radiopharmaceutical Injectors Market was valued at USD 11.96 Million in 2025 and is projected to expand at a CAGR of 7.38% from 2026 to 2035. Academic centers, health systems, and commercial imaging networks purchase most devices, and the growing number of radioligand therapy sites supports demand for shielded delivery equipment. Local service and training are important buying criteria. Many imaging networks also replace older shielded equipment on regular cycles, which supports recurring orders for suppliers.
Regulation is also shifting. The Nuclear Regulatory Commission published a proposed rule on 18 May 2026 to modernize its requirements for the medical use of byproduct material, with the aim of easing licensing burdens for radiopharmaceutical users. If adopted, the changes may speed the opening of new therapy sites and support equipment purchases. Industry groups are also working with regulators to clarify training and exposure expectations for staff. Licensing is handled by both federal and state authorities.
Europe Radiopharmaceutical Injectors Market
Europe accounted for 31.20% of the market in 2025, led by Germany, France, Italy, the United Kingdom, and the Netherlands. The region is home to several leading injector manufacturers and has strong nuclear medicine traditions. Hospitals are expanding theranostic programs, and radiation protection rules built on European directives encourage automation and careful dose recording. Public procurement and cross-border supply of isotopes also influence how quickly hospitals adopt automated devices across the region. Cross-border service networks are well developed.
Asia Pacific Radiopharmaceutical Injectors Market
Asia Pacific is projected to register the fastest regional CAGR of 10.40% from 2026 to 2035, and the region held 22.60% of the market in 2025. China, Japan, South Korea, India, and Australia lead demand, with rapid growth in PET scanner installations, local isotope production, and new therapy centers. Japan has a long record of manufacturing nuclear medicine equipment. Government programs that support cancer screening and nuclear medicine training are also helping new departments to open in large cities.
Latin America Radiopharmaceutical Injectors Market
Latin America held 4.80% of the market in 2025, led by Mexico and Brazil, followed by Argentina, Colombia, and Chile. Mexico has a growing network of PET centers serving both public and private patients, and Brazil operates cyclotrons and a national radiopharmaceutical program. Purchases focus on dependable, lower-cost systems with strong local service. Public and private health systems alike are broadening access to PET, and imports of equipment are supported by agreements with international suppliers.
Middle East & Africa Radiopharmaceutical Injectors Market
The Middle East & Africa accounted for 3.00% of the market in 2025, led by Saudi Arabia, the United Arab Emirates, Israel, South Africa, and Egypt. Gulf states are investing in cancer centers and PET facilities, while South Africa and Egypt support established nuclear medicine services. Imports supply most equipment, and training from international suppliers helps new departments begin operation. Partnerships with global suppliers also help new departments obtain training and maintenance support. Local distributors play a key role.
Key Radiopharmaceutical Injectors Market Company Insights
Competition in the Radiopharmaceutical Injectors Market spans specialist injector manufacturers, contrast media and imaging groups, and radiopharmaceutical suppliers. Leading participants compete on shielding performance, dose accuracy, software integration, and service coverage. Partnerships between device makers and isotope suppliers are becoming more common as therapy volumes rise.
Key Radiopharmaceutical Injectors Companies:
-
Bayer AG (Medrad)
-
Bracco Imaging S.p.A. (ACIST Medical Systems)
-
Comecer S.p.A.
-
Tema Sinergie S.p.A.
-
Lemer Pax
-
Eckert & Ziegler SE
-
Mirion Technologies, Inc. (Capintec)
-
Curium Pharma
-
Lantheus Holdings, Inc.
-
Jubilant Radiopharma
-
GE HealthCare Technologies Inc.
-
Siemens Healthineers AG
-
Sumitomo Heavy Industries, Ltd.
-
Trasis S.A.
-
Universal Giken Co., Ltd.
-
Cardinal Health, Inc.
Recent Developments
-
In October 2026, Jubilant Radiopharma announced an expansion of its Kirkland, Quebec site that doubles capacity for its RUBY-FILL rubidium generator, with support from the Canadian government.
-
In August 2026, Curium agreed to acquire Lantheus in a definitive merger agreement expected to close in the first half of 2027.
-
In June 2026, Eckert & Ziegler opened a commercial medical isotope production site in Jintan, China, with partner DC Pharma.
-
In June 2026, GE HealthCare showcased nuclear medicine software and imaging systems for theranostics at the SNMMI annual meeting.
-
In February 2026, Bayer Medical Care received U.S. clearance for its MEDRAD MRXperion injector, extending its injector portfolio.
-
In November 2025, Bracco announced an expanded U.S. indication for its Max 3 syringeless injector, advancing its injector portfolio.
-
In June 2025, Mirion Medical introduced new Capintec radiopharmacy products at the SNMMI annual meeting, including a phantom for dose calibrator testing.
-
In May 2025, Tema Sinergie received CE marking for its ASTER automated lutetium-177 therapy dose handling system.
Scope and Research Methodology
This report estimates the Radiopharmaceutical Injectors Market through a bottom-up build from device shipments and typical selling prices by type and operation mode, checked against a top-down view of PET and SPECT procedure volumes and radioligand therapy sites in each region. The scope covers shielded manual, semi-automated, and automated injectors and dose delivery systems used to administer radiopharmaceuticals. Contrast media injectors, radiopharmaceutical drugs, and imaging scanners are excluded from the estimate. Installed base figures are cross-checked against scanner counts and radiopharmacy surveys to confirm unit estimates and replacement cycles. Pricing is validated against vendor quotations and tender records collected from hospitals in each region, and ranges are adjusted for shielding, software, and service content.
Secondary research draws on regulatory filings, agency and association publications, company reports, and technical literature. Primary research includes conversations with nuclear medicine physicians, radiopharmacists, hospital purchasing managers, and device makers, used to confirm pricing, installed base, and adoption trends. Region coverage follows the five regions used throughout this report, with Mexico reported within Latin America. Interviews are repeated across different company types and regions so that findings are not dependent on a single viewpoint, and responses are compared with published procedure statistics wherever such data exist. Where public data are limited, assumptions are documented and tested through expert review.
Segment shares are built from vendor shipments and procedure volumes by type, operation mode, clinical area, and end user, then aligned with regional totals. Forecasts apply growth assumptions for each segment and region that reflect scanner installations, therapy approvals, safety rules, and replacement cycles, and they are tested against alternative scenarios. Figures are reviewed at each update as new rules and company announcements become available, and values are stated in U.S. dollars. Estimates in this report are draft values prepared for internal review and are updated when new data are collected. Currency conversions follow the exchange rates of each reference year, and all estimates are rounded to two decimals for consistency across tables and text.
Radiopharmaceutical Injectors Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 34.60 Million |
| Market Size by 2035 | USD 71.98 Million |
| CAGR | CAGR of 7.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (PET Injectors, PET and SPECT Injectors, and Theranostic Injectors) • By Operation Mode (Automated and Manual) • By Clinical Area (Oncology, Cardiology, Neurology, and Others) • By End User (Hospitals and Clinics, Diagnostic Imaging Centers, Research Institutions, and Nuclear Pharmacies) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Bayer, Comecer, Tema Sinergie, Lemer Pax, Sumitomo Heavy Industries |

Frequently Asked Questions
Key players include Bayer, Comecer, Tema Sinergie, Lemer Pax, and Sumitomo Heavy Industries.
The market was valued at USD 34.60 Million in 2025 and is projected to reach USD 71.98 Million by 2035.
The market is expected to register a CAGR of 7.60% from 2026 to 2035.
North America led the market with a 38.40% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 10.40% from 2026 to 2035.
PET injectors led the type segment with a 72.40% share in 2025, and automated injectors led the operation mode segment.
