
Roof Coating Market Report Scope & Overview:
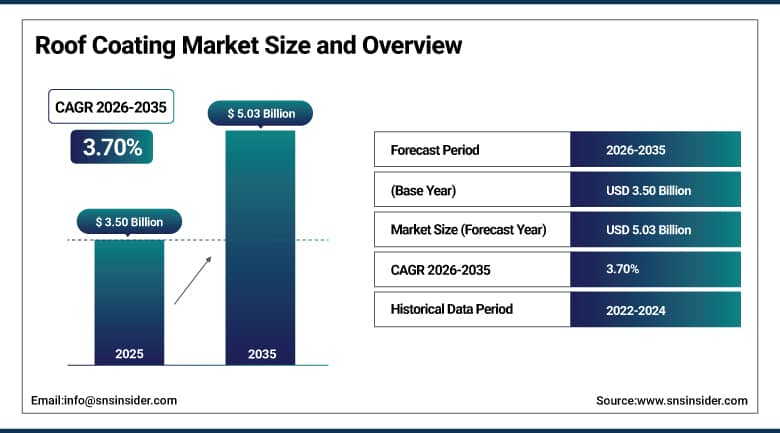
The Roof Coating Market was valued at USD 3.50 Billion in 2025 and is expected to reach USD 5.03 Billion by 2035, growing at a CAGR of 3.70% from 2026-2035.
The Roof Coating Market is expanding steadily as building owners extend the life of existing roofs through restoration coatings rather than full replacement, while cool-roof codes and energy-efficiency programs raise demand for reflective systems. Growth is supported by aging commercial roof stock in North America and Europe, rising cooling loads in hot regions, tighter volatile organic compound limits that favor waterborne and solventless chemistry, and wider use of silicone, acrylic and urethane systems on metal, membrane and built-up roofs. Contractors value fast-curing, single-coat products that reduce labor, and manufacturers are introducing bio-based and low-odor formulations. Asia Pacific offers the fastest incremental demand as construction expands.
Bio-based urethane technology is entering the restoration segment. In September 2025, Gaco introduced GacoBase U95, a two-component, castor oil-based urethane base coat for roof restoration and for encapsulating built-up gravel roofs as an alternative to spray foam. The low-VOC formulation requires no bleed-blocking primer and is compliant in all 50 states, a combination that reduces application steps for contractors while meeting regulatory limits, and it shows how suppliers are using renewable raw materials and simplified systems to differentiate in a mature, specification-driven category.
To Get More Information On Roof Coating Market - Request Free Sample Report
Roof Coating Market Trends
-
Adoption of cool-roof and reflective coatings driven by building energy codes
-
Shift from solvent-based to waterborne and solventless systems under VOC limits
-
Growth of silicone and elastomeric coatings for ponding water and UV resistance
-
Use of bio-based raw materials and fiber-reinforced one-coat systems
-
Restoration of aging roofs as a lower-cost alternative to tear-off and replacement
-
Integration of warranties, system certification and contractor training into product offers
U.S. Roof Coating Market Outlook
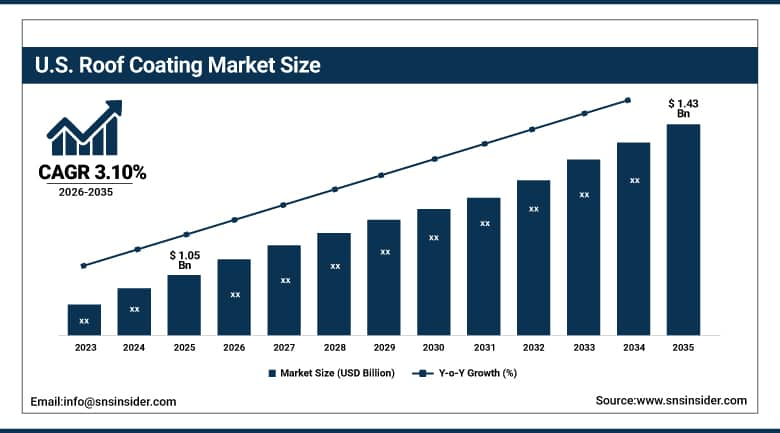
The U.S. Roof Coating Market was valued at USD 1.05 Billion in 2025 and is expected to reach USD 1.43 Billion by 2035, growing at a CAGR of 3.10% from 2026-2035.
The U.S. Roof Coating Market is the largest national market in North America, supported by a large stock of low-slope commercial roofs, frequent reroofing needs and cool-roof requirements in states such as California and New York. Acrylic, silicone, polyurethane and asphalt-based products are applied by professional roofing contractors on metal, single-ply, modified bitumen and built-up roofs, and sold through distributors, home centers and manufacturer-certified applicator networks. Storm damage, rising cooling costs and utility incentives influence purchasing, while product certification by the Cool Roof Rating Council and warranty programs shape specifications. Contractors prefer systems that cut labor and downtime.
Distribution partnerships are reinforcing silicone supply in North America. In November 2023, Dow named AB Specialty Silicones as its elastomeric coating distributor in the United States and Canada, giving contractors and formulators a dedicated channel for silicone-based roof coating technology. The appointment reflects growing demand for elastomeric systems that withstand ponding water, thermal movement and ultraviolet exposure, and it shows how raw material suppliers are tightening links with the downstream coating trade to capture restoration work on aging commercial roofs.
Roof Coating Market Segment Analysis
-
By Resin Type, the Acrylic segment dominated the Roof Coating Market with approximately 33.60% share in 2025, while the Silicone segment is the fastest growing with a CAGR of approximately 4.70%.
-
By Roof Type, the Low-Slope segment dominated the Roof Coating Market with approximately 54.35% share in 2025, while the Steep-Slope segment is the fastest growing with a CAGR of approximately 4.10%.
-
By Technology, the Water-Based segment dominated the Roof Coating Market with approximately 49.20% share in 2025, while the Solventless segment is the fastest growing with a CAGR of approximately 4.60%.
-
By Substrate, the Asphalt segment dominated the Roof Coating Market with approximately 38.70% share in 2025, while the Single-Ply Membrane segment is the fastest growing with a CAGR of approximately 4.50%.
-
By End Use, the Non-Residential segment dominated the Roof Coating Market with approximately 57.80% share in 2025, and is also the fastest growing with a CAGR of approximately 3.90%.
By Resin Type, Acrylic Dominates the Roof Coating Market and Silicone Grows Fastest
Acrylic coatings remain the leading chemistry, valued for their reflectivity, ease of application, low cost and compatibility with a wide range of substrates. Contractors apply them by roller or spray on metal, single-ply, spray foam and built-up roofs, and water-based formulations meet most volatile organic compound limits. Manufacturers offer fiber-reinforced and elastomeric versions that bridge cracks and extend service life, and the product's familiarity and broad availability through distributors keep it the default specification for cool-roof and maintenance programs.
Silicone coatings are advancing fastest because they resist ponding water, ultraviolet degradation and thermal cycling better than most alternatives. Building owners with low-slope roofs that hold water choose silicone to avoid blistering and delamination, and single-component, high-solids products shorten application time. Suppliers are widening the offer with high-build restoration systems and distribution partnerships for silicone technology, and long warranties tied to certified applicators strengthen the value case against replacement for aging commercial roofs.
By Roof Type, Low-Slope Dominates the Roof Coating Market and Steep-Slope Grows Fastest
Low-slope roofs account for the largest demand because commercial, industrial and institutional buildings use flat or nearly flat surfaces that are well suited to liquid-applied restoration. Warehouses, retail centers, schools and hospitals maintain large roof areas, and coatings extend membrane and built-up systems without tear-off. Water pooling, thermal movement and solar heat gain make seamless, reflective coatings attractive, and building codes and utility incentives for cool roofs reinforce adoption in warm climates across North America, the Middle East and Asia.
Steep-slope roofs are growing faster as coatings move into metal and residential applications where homeowners want to lower cooling bills and extend roof life. Reflective finishes for metal panels, tile and shingle surfaces are expanding, supported by retrofit programs and rising electricity costs. Manufacturers are introducing products with improved adhesion, color options and faster dry times suited to sloped surfaces, and contractor networks offering restoration services are extending reach into suburban housing stock where full replacement is expensive.
By Technology, Water-Based Dominates the Roof Coating Market and Solventless Grows Fastest
Water-based coatings lead because they combine low odor, low volatile organic compound content, easy cleanup and strong reflectivity, which suits occupied buildings and strict regional regulations. Acrylic and some elastomeric systems are formulated in water, and applicators value the safety benefits during work on commercial roofs. Their cost position relative to alternatives and wide distributor availability maintain a leading role, particularly in maintenance programs where speed, simplicity and compliance with environmental limits determine product choice.
Solventless systems are growing fastest as contractors seek one-coat, high-solids products that cure quickly and deliver heavy film builds without emissions. Fiber-reinforced and 100% solids formulations can be applied in a single pass on most substrates, reduce weather risk, and offer odorless application that limits disruption to tenants. Regulatory pressure on solvents, demand for durable restoration systems and growing acceptance of premium products by facility owners are expanding the segment, although higher material cost and specialized equipment moderate the pace.
By Substrate, Asphalt Dominates the Roof Coating Market and Single-Ply Membrane Grows Fastest
Asphalt-based roofs, including built-up and modified bitumen systems, represent the largest installed base for coatings because they are widespread on aging commercial and residential buildings. Coatings seal surface cracks, add reflectivity and protect against ultraviolet exposure, which delays costly replacement. Urethane and acrylic systems developed to encapsulate gravel-surfaced roofs give owners a cleaner alternative to tear-off, and the sheer volume of older bitumen roofs in North America and Europe sustains consistent restoration demand.
Single-ply membrane roofs are expanding fastest as thermoplastic and elastomeric membranes gain share in new construction and reroofing. Over time these membranes weather, discolor and lose reflectivity, and coating systems formulated for polyvinyl chloride, thermoplastic polyolefin and ethylene propylene diene monomer surfaces restore performance and extend life. Manufacturers have introduced primers and compatible topcoats with approvals from rating bodies, and as the installed base of membranes ages, recoating is becoming a standard maintenance practice for facility owners.
By End Use, Non-Residential Dominates the Roof Coating Market and Grows Fastest
Non-residential buildings lead demand because commercial, industrial, institutional and public roofs cover large areas, face scheduled maintenance cycles and are managed by facility teams that evaluate lifecycle cost. Coatings extend roof life, lower cooling loads and support sustainability goals, and owners often tie them to warranty programs and energy compliance. Warehouses and logistics centers built over the past two decades are entering the age at which restoration is cost-effective, which supports steady volume for manufacturers and certified applicators.
The same segment is also advancing fastest as new energy codes, corporate emission targets and utility rebates make reflective roofing a standard specification for large facilities. Growth in e-commerce warehousing, data centers and healthcare construction adds roof area, and property managers use coatings to defer capital expenditure. Manufacturers support the trend with system certifications, digital estimating tools and contractor training, while residential demand grows more slowly because homeowners continue to favor shingle replacement over liquid-applied restoration.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
86.43 |
|
Asia Pacific |
China |
39.65 |
|
Europe |
Germany |
27.58 |
|
Latin America |
Brazil |
49.84 |
|
Middle East & Africa |
Saudi Arabia |
26.31 |
North America Roof Coating Market Insights
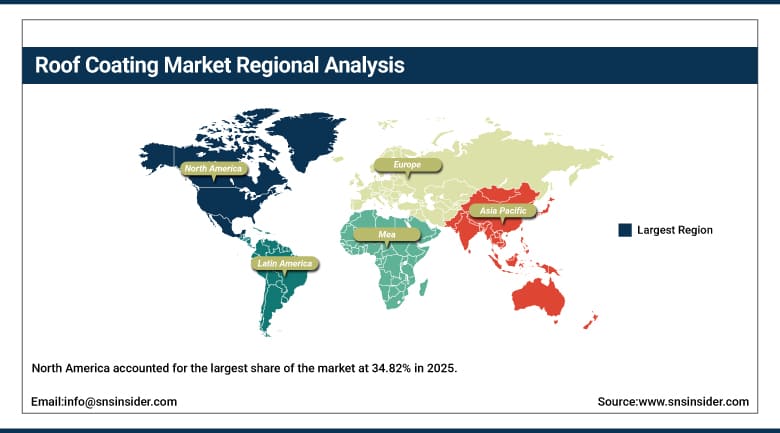
North America accounted for the largest share of the market at 34.82% in 2025, reflecting its large stock of aging low-slope commercial roofs, the maturity of its restoration contracting industry and the influence of cool-roof requirements in California, New York and other states. The United States generates most regional demand, and Canada adds a smaller market focused on durable, cold-tolerant systems. Reroofing represents the majority of demand, and restoration is often preferred to tear-off because of lower cost and less landfill waste.
Product innovation is concentrated in North America, where Gaco launched a bio-based urethane base coat in September 2025 and CertainTeed introduced its SMARTCOAT 400 acrylic system. Dow's appointment of AB Specialty Silicones as its elastomeric coating distributor for the United States and Canada in November 2023 strengthens silicone supply. Neogard received Cool Roof Rating Council approval for an aliphatic urethane topcoat in April 2023, and certification and warranty programs remain central to specifications in the region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Roof Coating Market Insights
Europe is a technology-driven market shaped by the Energy Performance of Buildings Directive, the renovation wave and some of the strictest volatile organic compound limits in the world. Germany, France, the United Kingdom, Italy and Spain lead consumption, and demand centers on flat roof waterproofing, refurbishment of public and commercial buildings and reflective coatings in southern countries. Polyurethane and acrylic liquid membranes are widely used for waterproofing and restoration, and contractors value systems that are certified and compatible with insulation layers.
Growth is steady rather than rapid, as renovation programs and climate-adaptation policies support demand but mature construction activity limits volume. Heat waves are raising interest in reflective coatings in Spain, Italy and Greece, and manufacturers emphasize low-emission, bio-based and recyclable formulations. Consolidation among roofing and waterproofing suppliers, including investment by building materials groups, is broadening system offers, and specifiers increasingly request environmental product declarations alongside performance data.
Asia Pacific Roof Coating Market Insights
Asia Pacific is the fastest-growing region, advancing at a CAGR of 4.90% during 2026-2035, supported by rapid urbanization, industrial construction and rising temperatures that raise cooling loads in China, India, Japan, South Korea and Southeast Asia. China leads regional consumption, driven by factory and warehouse roofs, while India's expanding logistics and housing sectors create new demand for reflective and waterproofing coatings. Local manufacturers supply cost-effective acrylic and bituminous products, and global suppliers are expanding production and distribution.
Government programs on building energy efficiency, heat mitigation in cities and green building ratings are encouraging adoption of cool roofs. Metal roofing is widespread on industrial buildings, creating demand for protective and reflective finishes, and rising awareness of life-cycle cost is shifting some owners from replacement toward restoration. Price sensitivity remains high, which favors waterborne acrylics, but premium silicone and urethane systems are entering high-value commercial and infrastructure projects.
MEA & Latin America Roof Coating Market Insights
The Middle East and Africa is driven by Gulf construction and extreme heat, with Saudi Arabia, the United Arab Emirates, Qatar and South Africa leading demand. Cool-roof rules are emerging in Dubai and Riyadh, and reflective, ultraviolet-resistant coatings help reduce air-conditioning loads in commercial and industrial buildings. Large infrastructure and housing programs create new roof area, while imported premium products compete with regional acrylic and bituminous suppliers.
Latin America is a smaller, price-sensitive market in which Brazil and Mexico lead demand, supported by housing programs, industrial construction and warm climates that favor reflective finishes. AkzoNobel announced the acquisition of Grupo Orbis in April 2022 to expand its coatings presence in the region, and global suppliers are strengthening distribution through paint retailers and builders' merchants. Currency swings and informal construction practices constrain premium product adoption, but rising awareness of energy savings is lifting interest in cool-roof solutions.
Market Dynamics
Growth Drivers: Roof Restoration, Cool-Roof Mandates and Aging Building Stock
Roof restoration is the leading driver because owners increasingly prefer to extend the life of existing roofs rather than tear them off. Coatings cost less than replacement, avoid disposal of old materials, and keep buildings in use during application. Aging commercial roof stock in North America and Europe, built in earlier decades of warehouse and retail construction, is reaching the point where restoration is economical, and warranties on coating systems give facility managers confidence to defer capital expenditure.
Cool-roof mandates and energy-efficiency programs strengthen demand. California Title 24 and similar codes require reflective surfaces on many low-slope roofs, and products listed by the Cool Roof Rating Council can reduce cooling costs and urban heat. Rising electricity prices and more frequent heat waves increase the value of reflective coatings, while utility rebates and green building programs encourage adoption. Product innovation, including fiber-reinforced one-coat systems and bio-based urethanes, shortens application time and widens the range of suitable roofs.
Restraints: Raw Material Volatility, VOC Compliance and Weather-Dependent Application
Raw material price volatility is a significant restraint because acrylic monomers, titanium dioxide, silicone intermediates and bitumen are tied to petrochemical and energy markets. Price swings compress margins for manufacturers and complicate bids for contractors, and supply disruptions can extend lead times for specific grades. Producers pass costs through slowly in a specification-driven market, and smaller formulators have limited ability to hedge or secure alternative sources, which can delay product launches and distribution.
Regulatory compliance and application constraints add further pressure. Volatile organic compound limits in California, the European Union and other jurisdictions force reformulation of solvent-based products and raise testing and certification costs. Coatings must be applied in dry, moderate weather, which compresses the working season in northern regions and creates scheduling risk for contractors. Poorly prepared substrates and ponding water can cause failures, and skilled labor shortages among roofing contractors limit how quickly demand for restoration projects can be converted into sales.
Opportunities: Silicone Systems, Single-Ply Membrane Recoating and Emerging Region Demand
Silicone and other high-performance systems present a significant opportunity as owners seek solutions for ponding water and long warranties. High-solids, single-component products reduce labor and shorten application time, and distribution partnerships, such as Dow's arrangement with AB Specialty Silicones, strengthen supply for formulators and contractors. Manufacturers that support these systems with training, certification and extended warranties can move up the value chain and capture restoration work on roofs that would otherwise be replaced.
Recoating of single-ply membranes and growth in emerging regions offer further opportunities. As thermoplastic and elastomeric membranes installed in recent decades weather, compatible primers and topcoats restore reflectivity and extend life, creating a recurring maintenance market. In Asia Pacific, the Middle East and Latin America, urbanization, industrial construction and new cool-roof rules are expanding the addressable roof area, and suppliers that localize production, adapt formulations to local climates and build applicator networks can establish early leadership.
Recent Developments:
-
2025, CertainTeed introduced SMARTCOAT 400 High Performance Acrylic Roof Coating, a heavy-bodied elastomeric coating for roof restoration. The product bonds to metal, single-ply, built-up and modified bitumen roofs, reduces interior temperatures and cooling costs, and forms the top layer of the SMARTCOAT system that is applied in sequence from cleaning to sealing.
-
2025, Castagra introduced Ecodur1 Cool Roof Coating, a fiber-reinforced, 100% solids product marketed as a one-coat solution on most substrates. The odorless, VOC-free coating is listed by the Cool Roof Rating Council and meets California Title 24 requirements, addressing contractor demand for faster application and regulatory compliance.
-
2025, BITEC introduced Storm Breaker HB Silicone, a single-component, high-build silicone coating for restoring aged roofs. The product offers waterproofing, ultraviolet protection, ponding water resistance and heat reflection with low VOC content and shorter application time, targeting owners of roofs that hold standing water.
-
2023, Neogard received Cool Roof Rating Council final approval for an aliphatic urethane roofing topcoat and FM certification for five roofing systems. The approvals strengthen the company's position in commercial specifications, where third-party listings and insurer certifications influence product selection.
-
2022, AkzoNobel announced its acquisition of Grupo Orbis to expand its presence in Latin America. The transaction adds regional brands and distribution capacity in a fast-growing coatings market, extending the reach of the company's decorative and protective product lines.
Roof Coating Market Key Players
-
The Sherwin-Williams Company
-
PPG Industries, Inc.
-
RPM International Inc.
-
BASF SE
-
AkzoNobel N.V.
-
Sika AG
-
Dow Inc.
-
GAF Materials Corporation
-
Carlisle Companies Incorporated
-
Henry Company
-
Nippon Paint Holdings Co., Ltd.
-
Kansai Paint Co., Ltd.
-
Hempel A/S
-
Wacker Chemie AG
-
Saint-Gobain (CertainTeed)
-
Gaco Western, LLC
-
Neogard
-
Polyglass U.S.A., Inc.
-
Owens Corning
-
Holcim Group
Roof Coating Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.50 Billion |
| Market Size by 2035 | USD 5.03 Billion |
| CAGR | CAGR of 3.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Resin Type (Acrylic, Silicone, Polyurethane, Bituminous, Epoxy, and Others) • By Roof Type (Low-Slope and Steep-Slope) • By Technology (Water-Based, Solvent-Based, and Solventless) • By Substrate (Asphalt, Metal, Single-Ply Membrane, Concrete, and Others) • By End Use (Non-Residential and Residential) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | The Sherwin-Williams Company, PPG Industries, Inc., RPM International Inc., BASF SE, AkzoNobel N.V., Sika AG, Dow Inc., GAF Materials Corporation, Carlisle Companies Incorporated, Henry Company, Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., Hempel A/S, Wacker Chemie AG, Saint-Gobain (CertainTeed), Gaco Western, LLC, Neogard, Polyglass U.S.A., Inc., Owens Corning, Holcim Group |

Frequently Asked Questions
Key players include The Sherwin-Williams Company, PPG Industries, RPM International, BASF, AkzoNobel, Sika, Dow, GAF Materials, Carlisle Companies, Neogard, Polyglass, Owens Corning and Holcim.
Key opportunities include silicone and high-solids restoration systems, recoating of aging single-ply membranes, reflective coatings driven by cool-roof codes, and growing roof area in Asia Pacific, the Middle East and Latin America.
The major growth factor is roof restoration, as building owners extend the life of aging roofs with coatings instead of replacing them, supported by cool-roof mandates, rising cooling costs and warranty-backed systems.
By Resin Type, the Acrylic segment dominated the market in 2025, owing to its reflectivity, ease of application and compatibility with many substrates.
North America dominated the market with a share of 34.82% in 2025, supported by aging commercial roof stock, a mature restoration industry and cool-roof requirements in several states.
