
Sterilization Equipment Market Report Scope & Overview:
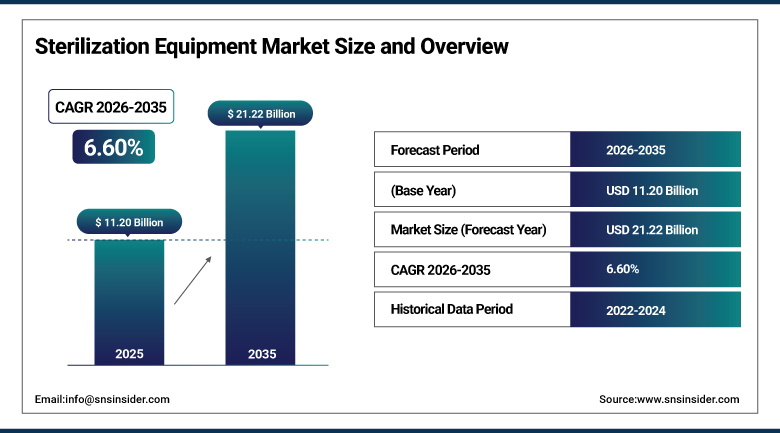
The Sterilization Equipment Market was valued at USD 11.20 Billion in 2025 and is expected to reach USD 21.22 Billion by 2035, growing at a CAGR of 6.60% from 2026-2035.
The Sterilization Equipment Market covers machines that destroy microorganisms on medical instruments, pharmaceutical products, laboratory materials and packaging, using steam, dry heat, ethylene oxide, hydrogen peroxide, plasma, filtration and radiation. Hospitals use steam sterilizers and washer-disinfectors in sterile processing departments, while drug makers and device manufacturers rely on validated chambers, isolators and contract sterilization sites. Growth is supported by rising surgical volumes, hospital-acquired infection control, biologics manufacturing and stricter standards, while emissions rules on ethylene oxide, capital cost and the need for validated, skilled operation shape adoption.
⮞In April, 2026, Getinge unveiled an expansion of its GSS67N steam sterilizer platform at the HSPA 2026 Annual Conference, supporting up to 24 trays and 600 lbs of FDA-cleared validated load in the same installed footprint. The update lets sterile reprocessing departments raise output without adding space or changing infrastructure.
To Get more information Sterilization Equipment Market - Request Free Sample Report
Sterilization Equipment Market Trends
- Shift toward low-temperature hydrogen peroxide and plasma systems for heat-sensitive instruments
- Adoption of fully automated sterile processing departments with tracking software
- Larger validated load capacity in the same footprint to raise throughput
- Growth of contract sterilization using X-ray, electron beam and gamma irradiation
- Reduced ethylene oxide use through lower-emission chambers and alternative modalities
- Rising demand for validated sterilization in biologics and cell and gene therapy manufacturing
U.S. Sterilization Equipment Market Outlook
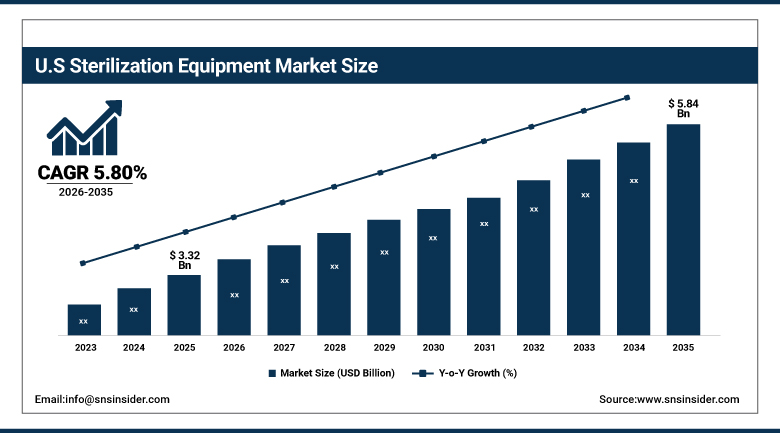
The U.S. Sterilization Equipment Market was valued at USD 3.32 Billion in 2025 and is expected to reach USD 5.84 Billion by 2035, growing at a CAGR of 5.80% from 2026-2035.
The U.S. Sterilization Equipment Market is the largest national market, supported by a high volume of surgical procedures, a large network of hospitals and ambulatory surgery centers, and a medical device and pharmaceutical industry that depends on validated sterilization. Steam sterilizers, washer-disinfectors and low-temperature systems are replaced on regular cycles, and accreditation standards require documented processes. Growth is moderated by hospital budgets, labor shortages in sterile processing and uncertainty over ethylene oxide rules.
⮞In May, 2025, Sterigenics, a Sotera Health company, announced a new X-ray sterilization facility at its Haw River, North Carolina campus, next to its existing gamma facility. The site is designed to meet growing sterilization demand from medical device, pharmaceutical and biopharmaceutical customers, and joins a network of 49 sterilization locations.
Sterilization Equipment Market Segment Analysis
- By Type, heat sterilization segment dominated the Sterilization Equipment Market in 2025 with an estimated 44.00% share; low-temperature sterilization segment is the fastest-growing segment, with an estimated CAGR of 8.60% during 2026–2035.
- By End User, hospitals and clinics segment dominated the Sterilization Equipment Market in 2025 with an estimated 44.00% share; pharmaceutical and biotechnology companies segment is the fastest-growing segment, with an estimated CAGR of 8.40% during 2026–2035.
- By Automation Level, manual and semi-automated systems segment dominated the Sterilization Equipment Market in 2025 with an estimated 57.00% share; fully automated systems segment is the fastest-growing segment, with an estimated CAGR of 9.10% during 2026–2035.
By Type, Heat Sterilization Dominates Sterilization Equipment Market; Low-Temperature Sterilization to Register Fastest Growth.
Heat sterilization dominates the Sterilization Equipment Market because steam autoclaves are the standard, lowest-cost and best-validated method for surgical instruments, laboratory media and many pharmaceutical products. They are fast, leave no toxic residue and are accepted by every major regulator. Hospitals operate several steam units in sterile processing departments, and dry heat ovens serve glassware and powders. Large installed bases create steady demand for replacement units, upgrades and service contracts supplied by long-established manufacturers. Service contracts for validation, repair and spare parts give suppliers recurring revenue. Mature supply chains keep prices competitive.
Low-temperature sterilization is projected to register the fastest growth because endoscopes, cameras, robotic instruments and plastic devices cannot withstand steam. Hydrogen peroxide, plasma, ozone and ethylene oxide systems sterilize these items at temperatures below about 60 degrees Celsius. Minimally invasive surgery is growing, and hospitals want faster cycles and safer chemistry than ethylene oxide, which supports hydrogen peroxide platforms. Filtration and radiation sterilization serve liquids, gases and single-use products in pharmaceutical and device manufacturing. Rapid cycle times are also a priority for busy operating rooms.
⮞In April 2026, STERIS launched its VHP LTS60 low-temperature sterilizer in North America, introducing a compact terminal surface sterilization system using vaporized hydrogen peroxide for heat-sensitive materials, with hands-free loading and configurable cycles to support validated sterilization processes.
By End User, Hospitals and Clinics Dominates Sterilization Equipment Market; Pharmaceutical and Biotechnology Companies to Register Fastest Growth.
Hospitals and clinics dominate the Sterilization Equipment Market because every surgical and dental procedure depends on sterile instruments, and facilities run sterilizers and washers throughout the day. Central sterile supply departments invest in steam and low-temperature units, instrument tracking and monitoring to meet accreditation standards and infection prevention rules. Ambulatory surgery centers, dental offices and outpatient clinics add many smaller buyers, and replacement cycles and expansion of operating rooms keep orders steady. Group purchasing organizations influence equipment choices for hospital networks. Rising operating room counts add steady replacement demand.
Pharmaceutical and biotechnology companies are projected to register the fastest growth as biologics, vaccines and cell and gene therapy production require validated sterilization of equipment, single-use assemblies, vials and isolators. Large steam sterilizers for production lines, vaporized hydrogen peroxide systems for isolators and filtration trains for liquids are in demand. Medical device makers, laboratories and food and beverage processors add steady demand, with device makers using contract radiation and ethylene oxide services. Regulators also expect documented validation of each cycle in these settings.
⮞In March 2026, Fundação Butantan initiated procurement for a 430-liter, double-door sterilization autoclave for its monoclonal-antibody production building, including installation, commissioning, qualification and operator training requirements, illustrating demand for validated sterilization equipment in biologics manufacturing.
By Automation Level, Manual and Semi-Automated Systems Dominates Sterilization Equipment Market; Fully Automated Systems to Register Fastest Growth.
Manual and semi-automated systems dominate the Sterilization Equipment Market because most hospitals, clinics, dental offices and laboratories worldwide use units that need operators to load, select cycles and record results. These systems cost less than fully automated lines, fit small departments and are easy to maintain, so they remain the default choice for facilities with limited budgets. Tabletop autoclaves and standard chamber units form the bulk of installations in developing countries. Training, ease of use and low maintenance also favor these systems in smaller sites.
Fully automated systems are projected to register the fastest growth as large hospitals and pharmaceutical plants adopt conveyor-based sterile processing, robotic loading and software that tracks every instrument set. Automation cuts labor needs at a time of staff shortages, improves traceability and reduces errors in reprocessing. Vendors are bundling washers, sterilizers and tracking software into integrated departments, and hospital groups building new central processing facilities are choosing these designs to standardize quality. Digital cycle records also support audits and compliance with accreditation rules. Labor savings help justify investment.
⮞In December 2025, Getinge introduced Automatiq, a modular sterile-processing automation portfolio combining self-navigating mobile robots, intelligent workstations, automated loading equipment and orchestration software to reduce manual handling and improve workflow coordination in hospital central sterile supply departments.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
86.00 |
|
Europe |
Germany |
27.00 |
|
Asia Pacific |
China |
46.00 |
|
Latin America |
Brazil |
49.00 |
|
Middle East & Africa |
Saudi Arabia |
31.00 |
North America Sterilization Equipment Market Insights
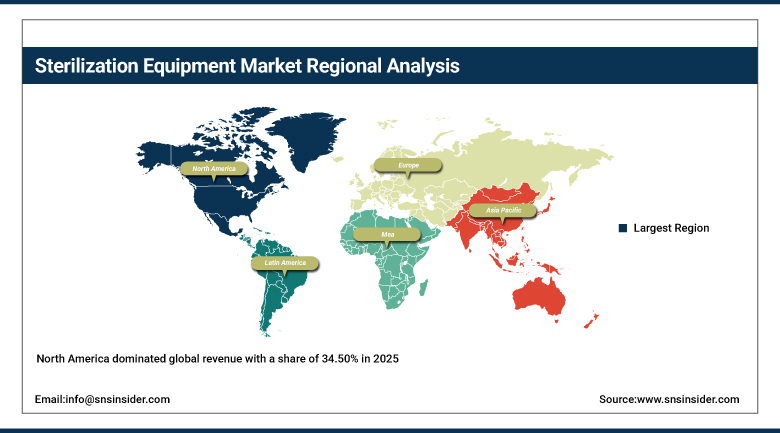
North America dominated global revenue with a share of 34.50% in 2025. The United States accounts for dominant share of regional demand, with Canada adding volume through hospital modernization and medical device manufacturing. STERIS, Getinge, Advanced Sterilization Products, Tuttnauer and Andersen Products serve hospitals, while Sotera Health and other contract sterilizers support device makers. Group purchasing organizations and large health systems negotiate multi-year contracts that favor suppliers with broad service networks.
The region has a large installed base of steam and low-temperature units, strict accreditation requirements, and a medical device industry that depends on ethylene oxide and radiation services. Hospitals are replacing aging sterilizers and investing in tracking and automation to address labor shortages. Emissions rules on ethylene oxide and tight hospital budgets are the main restraints, while pharmaceutical manufacturing investment supports demand for validated production equipment. Ambulatory surgery centers are also expanding quickly, adding demand for compact, high-throughput sterilizers that fit smaller departments with limited staff and space. Group purchasing also supports standardization.
⮞In August 2025, Advanced Sterilization Products (ASP) launched its BIOTRACE Instant Read Steam System, an FDA-cleared biological indicator system delivering sterilization-monitoring results in seven seconds, compared with 20 minutes or longer for conventional systems, supporting faster sterility-assurance decisions in hospital sterile processing departments.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Sterilization Equipment Market Insights
Germany leads regional demand, followed by France, the United Kingdom, Italy, Spain and the Nordic countries, supported by large hospital systems, a strong medical technology base and established sterilizer manufacturers. Getinge, Belimed, Steelco, Miele Professional, Matachana, MMM Group, Systec and BMT Medical Technology are headquartered or heavily active in the region. Eastern European countries are modernizing hospitals with European Union funding, and Spain and the Nordic countries are investing in central sterile departments with integrated tracking and washing equipment. Germany and France also host large exporters.
European Union rules on medical devices and standards for reprocessing shape purchasing, and sustainability goals push hospitals toward units that save water and energy. Public hospital budgets slow replacement cycles in some countries, but renovation of central sterile departments and expansion of contract sterilization capacity add demand. Regional makers also export widely to Asia, the Middle East and Africa, strengthening their position in global supply. Cooperation between hospitals and manufacturers on training programs also helps raise reprocessing quality across the region.
⮞In September 2026, Berlin's Unfallkrankenhaus hospital procurement organization advanced a modernization program for its medical-device reprocessing department, covering replacement of steam and low-temperature sterilizers, washer-disinfectors and associated equipment while maintaining continuous operations for a facility processing approximately 100,000 sterilization units annually.
Asia Pacific Sterilization Equipment Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 8.40% during 2026-2035. China leads regional demand, followed by Japan, India, South Korea and Southeast Asian countries, supported by hospital construction, rising surgical volumes and growth of pharmaceutical and device manufacturing. Shinva Medical Instrument, Sakura Seiki, Human Meditek and local makers compete with global brands on price. Southeast Asian countries such as Thailand, Malaysia, Indonesia and Vietnam are building private hospitals and medical tourism centers that purchase international sterilization brands, while Australia adds mature demand. Rising incomes also support private hospital construction.
Governments are expanding hospital capacity and tightening infection control rules, which raises demand for central sterile departments and validated equipment. Chinese suppliers are growing exports, while India is building local capacity for autoclaves and tabletop sterilizers through new entrants. Price sensitivity, uneven reprocessing standards and a shortage of trained staff in smaller cities remain challenges, although rising medical tourism and private hospital chains support premium purchases. Pharmaceutical contract manufacturing in India and China is also growing, which supports orders for large steam sterilizers, isolators and filtration trains for production lines.
⮞In July 2025, China's Shinva Medical Instrument launched its LAS-M Series vertical autoclave, incorporating enhanced safety features, intelligent operation and improved sterilization efficiency; the company reported that the first 20 units had passed factory inspections and entered customer use, supporting laboratory sterilization requirements.
MEA & Latin America Sterilization Equipment Market Insights
In Latin America, Brazil leads on the strength of its large hospital system and growing medical device sector, followed by Mexico, Argentina and Colombia. Regional demand is supported by private hospital investment and expanding surgical access. Multinational makers sell through distributors, while local assemblers serve price-sensitive buyers with tabletop and mid-size autoclaves. Chile, Peru and Colombia add steady demand through hospital upgrades, and public health programs in several countries are modernizing sterile processing in major referral hospitals. Peru and Chile also invest in hospital networks.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates and South Africa lead demand. Large hospital construction programs in the Gulf drive orders for central sterile departments, and Matachana and MMM Group are among suppliers active in the region. Limited budgets and a shortage of trained technicians restrain adoption in much of Africa, although donor programs and private clinics are creating new demand. Egypt, Turkey and Nigeria add smaller volumes through hospital construction and private clinic growth, and local distributors are important for installation, training and service support across the region.
⮞In October 2026, Saudi Arabia's National Guard Health Affairs issued a procurement notice for environmental-monitoring devices for sterilization departments at King Abdulaziz Medical City in Riyadh, demonstrating continued investment in monitoring infrastructure supporting controlled hospital sterilization environments and infection-prevention procedures.
Market Dynamics
Growth Drivers: Surgical Volumes, Infection Control and Biologics Manufacturing
Rising surgical volumes are a central driver of the Sterilization Equipment Market. Aging populations, more minimally invasive procedures and expansion of ambulatory surgery centers increase the number of instrument sets that must be cleaned and sterilized each day. Hospitals also face pressure to prevent surgical site infections, which supports spending on validated equipment, tracking and monitoring. Regulators and accreditation bodies also demand stronger records, which favors modern equipment with built-in data capture. Rising numbers of dental procedures add further demand for tabletop sterilizers. Government infection control programs in emerging markets also boost purchases.
Biologics, vaccines and cell and gene therapy manufacturing add a second source of growth, because production relies on sterilized equipment, single-use assemblies and aseptic filling. Pharmaceutical investment in new plants raises orders for large steam sterilizers, vaporized hydrogen peroxide systems and filtration, and regulators continue to raise expectations for validation and documentation. Growth in single-use device manufacturing also raises demand for contract and in-house sterilization capacity. Pharmaceutical companies increasingly require validated, traceable processes for every sterilization step.
⮞In April 2026, Biogen highlighted its $2 billion investment in manufacturing capabilities across its Research Triangle Park campuses in North Carolina, building on decades of U.S. manufacturing investment to modernize facilities and expand production capabilities, supporting demand for validated sterilization equipment used in pharmaceutical manufacturing.
Restraints: Ethylene Oxide Regulation, Capital Cost and Skills Gaps
Ethylene oxide is a widely used sterilant for medical devices but is classified as a carcinogen, and emissions rules create uncertainty for operators and customers. Changes to compliance dates and local opposition to facilities can delay investment, and users must plan for alternatives that need requalification of products. Uncertainty over future rules can also make buyers delay long-term capacity decisions. Environmental objections to emissions from large sterilization sites also affect permits. Requalification of products after changing sterilant adds time and expense.
Sterilizers and automated departments require significant capital, and public hospitals in many countries delay replacement. Skilled sterile processing technicians are in short supply, which limits full use of advanced systems. Strict validation requirements also lengthen the time needed to adopt new technologies. Supply chain disruptions for chambers, valves and control parts can extend delivery times for new systems. Water and energy use in steam systems can raise operating cost for hospitals.
Opportunities: Low-Temperature Systems, Automation and Contract Sterilization
Low-temperature hydrogen peroxide and plasma systems offer room to replace ethylene oxide in hospitals and some device applications, giving suppliers a chance to win upgrades. Automation, tracking software and integrated washer and sterilizer lines let hospitals address staff shortages and improve quality. Service revenue from validation, preventive maintenance and software subscriptions can improve margins for equipment suppliers. Partnerships between equipment makers and software firms can add value through analytics. Rental and leasing models can lower the upfront cost for smaller facilities.
Contract sterilization using X-ray, electron beam and gamma irradiation offers growth for device and pharmaceutical customers that prefer to outsource, and the build-out of new facilities supports equipment sales. Emerging markets building hospitals also present large first-time buyer opportunities. Hospitals in Asia, the Middle East and Africa are still building central sterile departments, which creates first-time buyer demand for complete packages. Retrofit and upgrade packages let hospitals extend the life of existing sterilizers at lower cost.
⮞In August 2026, India's Ministry of Health and Family Welfare finalized amendments to the Medical Devices Rules, 2017, removing the separate loan-licence requirement for manufacturers outsourcing sterilization to facilities holding valid licences, reducing administrative burdens and supporting greater use of specialized third-party sterilization services.
Recent Developments:
- In October 2026, STERIS agreed to buy Xodus Medical for USD 2.10 billion in a deal expected to close by December 31, 2026. The company also said in August 2026 it would spend USD 600 million on a North Carolina hub to make and distribute chemicals used in healthcare sterilization and pharmaceutical production.
- In April 2026, Getinge expanded its GSS67N steam sterilizer platform to support up to 24 trays and 600 lbs of validated load in the same footprint. The upgrade was unveiled at the HSPA 2026 Annual Conference.
- In November 2025, Getinge introduced a new version of its Solsus 66 steam sterilizer with a combined steam option. The unit is offered in Europe and other markets accepting CE-marked medical devices.
- In May 2025, Sterigenics announced a new X-ray sterilization facility at its Haw River, North Carolina campus. The facility adds irradiation capacity for the Southeast United States.
Sterilization Equipment Market Key Players are:
-
STERIS plc
-
Getinge AB
-
Belimed AG
-
Steelco S.p.A.
-
Advanced Sterilization Products
-
Matachana Group
-
MMM Group
-
Tuttnauer Co., Ltd.
-
Shinva Medical Instrument Co., Ltd.
-
Sakura Seiki Co., Ltd.
-
Miele Professional
-
Andersen Products, Inc.
-
Sotera Health Company
-
Stryker Corporation
-
Systec GmbH
-
BMT Medical Technology s.r.o.
-
HUMAN MEDITEK CO., LTD.
-
Renosem
-
Scitek Global Co., Ltd.
-
Labtron Equipment Ltd.
Sterilization Equipment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 21.22 Billion |
| Market Size by 2035 | USD 12.27 Billion |
| CAGR | CAGR of 6.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Heat Sterilization, Low-Temperature Sterilization, Filtration Sterilization, and Radiation Sterilization) • By End User (Hospitals and Clinics, Pharmaceutical and Biotechnology Companies, Medical Device Manufacturers, Food and Beverage Companies, and Others) • By Automation Level (Manual and Semi-Automated, and Fully Automated) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | STERIS plc; Getinge AB; Belimed AG; Steelco S.p.A.; Advanced Sterilization Products; Matachana Group; MMM Group; Tuttnauer Co., Ltd.; Shinva Medical Instrument Co., Ltd.; Sakura Seiki Co., Ltd.; Miele Professional; Andersen Products, Inc.; Sotera Health Company; Stryker Corporation; Systec GmbH; BMT Medical Technology s.r.o.; HUMAN MEDITEK CO., LTD.; Renosem; Scitek Global Co., Ltd.; Labtron Equipment Ltd. |

Frequently Asked Questions
Key players include STERIS plc, Getinge AB, Belimed AG, Steelco S.p.A., Advanced Sterilization Products, Matachana Group, MMM Group and Tuttnauer Co., Ltd.
Key opportunities include low-temperature hydrogen peroxide and plasma systems, automated sterile processing departments, and contract sterilization using X-ray, electron beam and gamma irradiation.
The major growth factor is rising surgical volumes and infection control requirements, together with expanding biologics and pharmaceutical manufacturing.
By Type, the Heat Sterilization segment dominated the market in 2025 with an estimated 44.00% share, supported by the wide use of steam autoclaves in hospitals and laboratories.
North America dominated the market with a share of 34.50% in 2025, driven by a high volume of surgeries, a large hospital network and a strong medical device industry.
