
Subsea Well Access Market Report Scope & Overview:
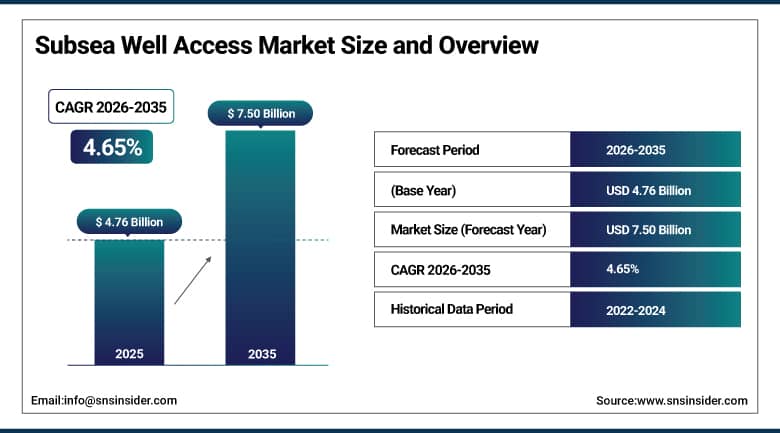
The Subsea Well Access Market was valued at USD 4.76 Billion in 2025 and is expected to reach USD 7.50 Billion by 2035, growing at a CAGR of 4.65% from 2026 to 2035.
The subsea well access market is growing at a steady pace owing to increasing demand in deepwater exploration, high standards in safety operations, and the need to sustain efficiency in aging offshore fields. Subsea well access systems include technologies and equipment that allow safe and controlled intervention, maintenance, testing, and control of oil and gas wells on the sea floor, encompassing riser-based and riserless solutions that sustain deep-sea production through subsea trees, blowout preventers, and control systems. Furthermore, market growth is being reinforced by the use of advanced technologies in subsea intervention promoting safe operation and enhancing productivity in complex deepwater fields, growing brownfield optimization activity across aging offshore infrastructure, and increasing regulatory compliance and safety standards governing offshore well operations worldwide.
Aging reservoirs, including over 60% of Golden Triangle wells drilled between 2005 and 2015, face declining output, water breakthrough, and scaling challenges, making well interventions 6 to 10 times cheaper than new drilling at USD 15 to 25 million versus USD 120 to 150 million, driving strong economic incentive for operators to prioritize subsea well access investment over new drilling programs.
To Get More Information On Subsea Well Access Market - Request Free Sample Report
Subsea Well Access Market Trends
- Rising brownfield optimization is sustaining subsea well access investment as operators prioritize cost-effective interventions.
- Growing riserless intervention adoption is enabling flexible subsea well access without full rig-based riser systems.
- Increasing vessel-based system deployment is providing cost-efficient alternatives to conventional rig-based well intervention.
- Expanding digital monitoring and remote intervention adoption is improving productivity and safety in complex deepwater operations.
- Strategic partnerships are accelerating efficient and environmentally compliant subsea well access solution development.
The U.S. Subsea Well Access Market Outlook
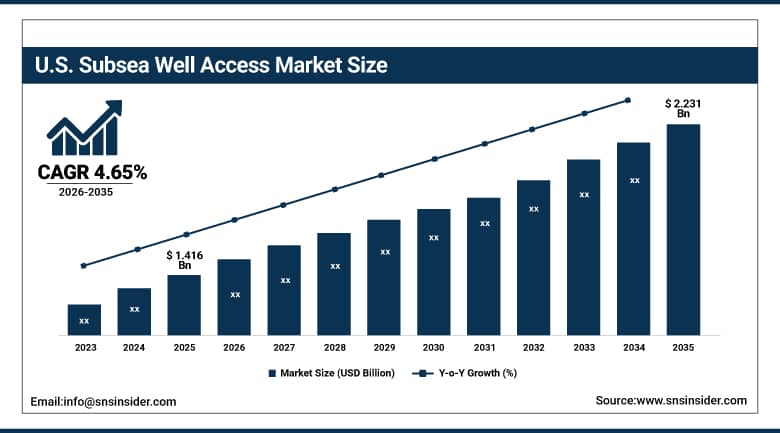
The U.S. subsea well access market was valued at USD 1.41 Billion in 2025 and is projected to reach USD 2.23 Billion by 2035, growing at a CAGR of 4.65% during 2026–2035.
The country's leading offshore operators continue to expand subsea well access investment, driven by sustained Gulf of Mexico deepwater production activity and growing brownfield optimization programs across aging offshore well portfolios. Growing regulatory emphasis on offshore well safety compliance, combined with rising operator focus on cost-efficient intervention alternatives extending mature field productive life, continues to reinforce sustained domestic demand for both rig-based and vessel-based subsea well access technology across the country's substantial offshore oil and gas production base.
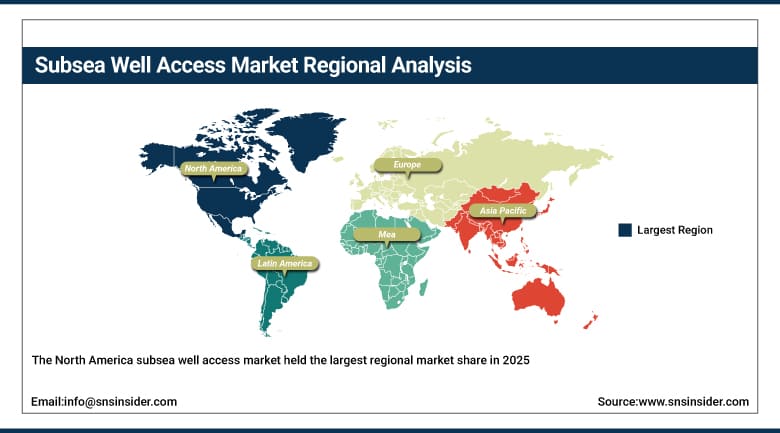
The North America region captured the largest market share in the subsea well access solutions in 2025, where the United States was the major contributing country to the region due to vast deepwater production facilities in the Gulf of Mexico region.
Subsea Well Access Market Segment Analysis
- By Application, well intervention dominated the subsea well access market with a 48.60% share in 2025, while production enhancement is the fastest-growing application segment with a CAGR of 8.20% from 2026–2035.
- By Type, rig-based well access systems dominated the subsea well access market with a 62.40% share in 2025, while vessel-based well access systems is the fastest-growing type segment with a CAGR of 7.20% from 2026–2035.
- By Service Type, installation services dominated the subsea well access market with a 54.60% share in 2025, while maintenance services is the fastest-growing service type segment with a CAGR of 8.60% from 2026–2035.
- By Location, deepwater dominated the subsea well access market with a 43.50% share in 2025, while ultra-deepwater is the fastest-growing location segment with a CAGR of 7.90% from 2026–2035.
By Application, well intervention dominated the subsea well access market, while production enhancement is the fastest-growing segment.
The well intervention segment dominated the subsea well access market with a revenue share of 48.60% in 2025 due to the aging global offshore well portfolio. Well intervention remains the dominant application category owing to periodic maintenance and stimulation requirements across offshore wells needing sustained production efficiency and reservoir pressure management, representing the foundational and most frequently performed subsea well access activity worldwide.
The production enhancement segment is expected to exhibit the highest revenue growth at a CAGR of 8.20% in the forecast period of 2026 to 2035. The increasing inclination of the operators towards enhancing the recovery from the existing offshore wells through enhanced production stimulation technologies is propelling the growth of the segment, owing to the faster and cheaper gains provided by production enhancement over drilling.
By Type, rig-based well access systems dominated the subsea well access market, while vessel-based well access systems is the fastest-growing segment.
The segment of rig based well access systems held the largest market share in terms of revenue at 62.40% in 2025 for the subsea well access market. Rig-based well access systems are the leading category of systems due to the stability associated with their operations and extensive use offshore, being compatible with existing offshore rigs infrastructure that makes them the most favorable choice in the majority of cases.
The vessel-based well access systems segment is expected to grow at the fastest CAGR of 7.20% during the forecast period 2026-2035, owing to the increasing need for cost-efficient, flexible intervention alternatives. Growing operator preference for vessel-based systems, which avoid the high day rates associated with dedicated offshore rigs while still providing effective well access capability, is driving rapid segment growth across cost-conscious offshore intervention programs worldwide.
By Service Type, installation services dominated the subsea well access market, while maintenance services is the fastest-growing segment.
The installation services segment dominated the subsea well access market with the largest revenue share in 2025. Installation services remain the dominant category owing to their essential role in deploying subsea trees, wellheads, and control systems required to establish new well access infrastructure, representing a substantial and recurring capital expenditure category across offshore field development programs worldwide.
This maintenance services market segment is set to witness highest CAGR growth in the forecast period from 2026 to 2035. Increasing awareness of the fact that aging subsea infrastructure necessitates increased inspection and maintenance efforts is the key factor fuelling fast segment growth owing to focus on maximizing the lifetime of existing equipment rather than replacing it completely.
By Location, deepwater dominated the subsea well access market, while ultra-deepwater is the fastest-growing segment.
Revenue share for the deep water section accounted for 43.50% of the total subsea well access market in 2025 because of the migration of offshore operations into deeper waters. Deepwater is still the most prevalent location type due to exploration and production activity that takes place at deeper water sites, which account for a large portion of global offshore oil and gas reserves.
The ultra-deepwater segment is expected to witness the fastest CAGR of 7.90% during the forecast period 2026-2035. Growing operator investment in the most technically demanding ultra-deepwater fields, requiring increasingly sophisticated well access technology capable of withstanding extreme pressure and temperature conditions, is driving strong segment growth as exploration continues pushing into ever-deeper offshore frontiers.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Norway |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
26.80% |
|
Latin America |
Brazil |
37.70% |
North America Subsea Well Access Market Insights
The North America subsea well access market held the largest regional market share in 2025 owing to extensive Gulf of Mexico deepwater production infrastructure, sustained operator investment in well intervention technology, and strong regulatory framework governing offshore well safety compliance.
The US was the leading country within the North America subsea well access market in 2025, driven by extensive Gulf of Mexico deepwater production activity and growing brownfield optimization programs across aging offshore well portfolios. Canada is contributing to regional growth through its own expanding offshore exploration and production investment.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Subsea Well Access Market Insights
The Europe subsea well access market was a major contributor in 2025. This is attributed to the region's substantial North Sea offshore production base, growing aging infrastructure maintenance requirements, and strong presence of leading subsea equipment and service providers.
Norway is one of the major markets in Europe owing to its substantial North Sea offshore production base and strong government-backed investment in well intervention and maintenance technology. The United Kingdom is also a significant market, driven by North Sea decommissioning projects and aging asset maintenance programs requiring sustained subsea well access investment.
Asia Pacific Subsea Well Access Market Insights
The Asia-Pacific region is anticipated to experience the fastest growth throughout the forecast period. The market growth is driven by expanding offshore exploration and production investment, growing deepwater field development activity, and increasing regional interest in extending mature field productive life.
China is one of the main growth drivers in the Asia Pacific subsea well access market, owing to its expanding domestic offshore oil and gas production capacity and growing rig-based well access system investment. Australia, India, and Southeast Asian nations are also contributing to regional growth through expanding offshore exploration activity and rising deepwater production investment.
Middle East & Africa and Latin America Subsea Well Access Market Insights
Middle East & Africa and Latin American regions are gradually expanding subsea well access adoption as offshore exploration investment grows across both regions, supported by increasing regional deepwater and pre-salt field development activity.
Brazil is set to be a prominent Latin American market fueled by its substantial pre-salt field operations requiring sustained well intervention and access investment. The Middle East & Africa region has UAE and Saudi Arabia investing in offshore exploration infrastructure as part of broader energy sector diversification supporting the region's expanding offshore production capacity.
Market Dynamics
Growth Drivers: Rising deepwater exploration and offshore safety standards driving market growth
The increasing demand in deepwater exploration, high standards in safety operations, and the need for efficiency in old mature offshore fields are driving the Subsea Well Access Market demand. Subsea well access systems play a strategic role in offshore asset productivity, supporting offshore oil and gas production without surface structures and enabling safe extraction and transportation in complex deepwater environments using flexible, lower-footprint infrastructure.
The use of advanced technologies in subsea intervention provides the opportunity to promote safe operation, enhance productivity, and maximize performance in complex deepwater fields around the world. Deepwater exploration, escalated offshore oil and gas production, stringent regulatory compliance and safety standards, reservoir depletion issues, and mounting global energy demand are further supporting demand across the forecast period, as operators continue investing in well intervention capability extending mature field productive life.
Restraints: High operating costs and technical complexity limiting market expansion
One of the biggest challenges that face market development includes the very high costs related to rig-based access systems especially when used for ultra-deepwater drilling which requires special ships and rigs that can withstand very high pressure and temperatures during times of unstable prices of oil and gas.
Additionally, the technical complexity of coordinating subsea intervention operations in increasingly deep and remote offshore locations requires substantial specialized engineering expertise, adding cost and scheduling complexity for operators. Fluctuating oil and gas commodity pricing directly affects offshore operator capital expenditure decisions, creating cyclical demand patterns that can constrain revenue predictability for subsea well access equipment and service providers.
Opportunities: Expansion of vessel-based intervention and brownfield optimization creating new growth avenues
The future of the Subsea Well Access Market looks promising with opportunities in cost-efficient vessel-based intervention alternatives, as growing brownfield optimization activity across aging offshore infrastructure is expected to generate substantial opportunities for well access equipment and service providers offering flexible, cost-effective intervention solutions.
There is a considerable growth opportunity in the continued development of riserless well intervention technology that reduces operational costs relative to conventional rig-based approaches. The expansion of deepwater and ultra-deepwater exploration investment in emerging markets across Asia Pacific and Latin America is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: TechnipFMC launched an updated subsea production system technology platform, offering operators enhanced well access capability for increasingly complex deepwater field development projects.
- 2025: Oceaneering International expanded its vessel-based well intervention service fleet, strengthening its ability to provide cost-efficient, flexible offshore well access alternatives to conventional rig-based operations.
- 2026: Aker Solutions launched an updated riserless well intervention system, offering operators a cost-effective alternative to conventional rig-based well access for routine maintenance and stimulation operations.
- 2026: Baker Hughes expanded deployment of its subsea wellhead technology, strengthening its ability to support operators pursuing brownfield optimization across aging offshore well portfolios.
Subsea Well Access Market key players are:
- TechnipFMC plc
- SLB (Schlumberger Limited)
- Baker Hughes Company
- Halliburton Company
- Aker Solutions ASA
- Subsea 7 S.A.
- Oceaneering International, Inc.
- Dril-Quip, Inc.
- Weatherford International plc
- NOV Inc.
- Expro Group Holdings N.V.
- Forum Energy Technologies, Inc.
- Trendsetter Engineering, Inc.
- Helix Energy Solutions Group, Inc.
- Saipem S.p.A.
- McDermott International, Ltd.
- Petrofac Limited
- Enpro Subsea Ltd.
- Proserv Group Inc.
- Kongsberg Maritime AS
Subsea Well Access Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.76 Billion |
| Market Size by 2035 | USD 7.50 Billion |
| CAGR | CAGR of 4.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Rig-Based Well Access Systems, Vessel-Based Well Access Systems) • By Application (Well Intervention, Production Enhancement, Well Testing) • By Service Type (Installation Services, Maintenance Services) • By Location (Shallow Water, Deepwater, Ultra-Deepwater) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | TechnipFMC plc, SLB (Schlumberger Limited), Baker Hughes Company, Halliburton Company, Aker Solutions ASA, Subsea 7 S.A., Oceaneering International, Inc., Dril-Quip, Inc., Weatherford International plc, NOV Inc., Expro Group Holdings N.V., Forum Energy Technologies, Inc., Trendsetter Engineering, Inc., Helix Energy Solutions Group, Inc., Saipem S.p.A., McDermott International, Ltd., Petrofac Limited, Enpro Subsea Ltd., Proserv Group Inc., Kongsberg Maritime AS. |
Frequently Asked Questions
The North America region dominated the Subsea Well Access Market in 2025, supported by extensive Gulf of Mexico deepwater production infrastructure.
The market is driven by increasing demand in deepwater exploration, high standards in safety operations, and the need to sustain efficiency in aging offshore fields.
The Rig-Based Well Access Systems segment dominated the Subsea Well Access Market in 2025, accounting for approximately 62.40% market share.
The Subsea Well Access Market is expected to grow at a CAGR of 4.65% from 2026 to 2035.
The Subsea Well Access Market was valued at USD 4.76 Billion in 2025.
