
Urinary Catheters Market Report Scope & Overview:
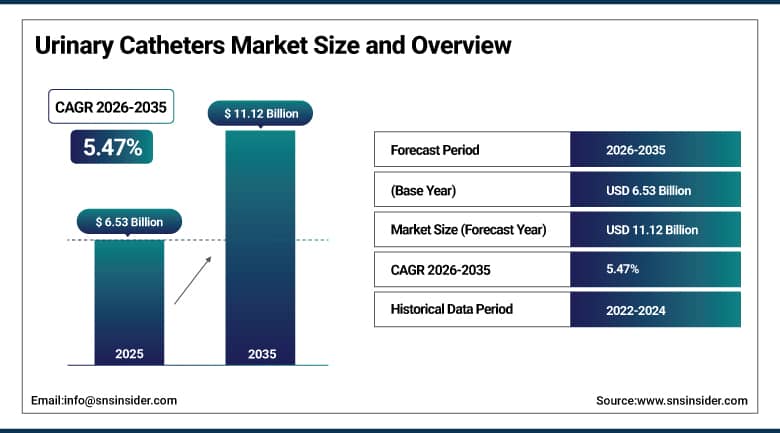
The Urinary Catheters Market was valued at USD 6.53 Billion in 2025 and is expected to reach USD 11.12 Billion by 2035, growing at a CAGR of 5.47% from 2026-2035.
The Urinary Catheters Market is expanding as aging populations, chronic bladder conditions and a shift to home care raise demand for drainage devices. Intermittent catheters now lead because they carry a lower infection risk than long-term indwelling use. Hydrophilic and gel-coated products improve comfort and are gaining reimbursement. Indwelling catheters remain essential in hospitals and surgery. External catheters offer a non-invasive option, particularly for women. Manufacturers are investing in antimicrobial coatings, ready-to-use designs and discreet compact packaging. Infection prevention programs and payer rules shape purchasing. The market is expected to grow steadily as care moves from hospitals to homes and as more patients learn to self-catheterize.
⮞In July 2026, the U.S. Centers for Disease Control and Prevention reported a 10% decrease in catheter-associated urinary tract infections among U.S. acute care hospitals in 2024 compared with 2023. The decline shows how infection prevention programs shape catheter selection and use.
To Get More Information On Urinary Catheters Market - Request Free Sample Report
Urinary Catheters Market Trends:
-
Rising use of hydrophilic and ready-to-use intermittent catheters
-
Growth of female and male external catheters as non-invasive alternatives
-
Antimicrobial and silver-alloy coatings to reduce infection risk
-
Shift of catheter care from hospitals to homes through direct supply services
-
Reimbursement changes that separate coated catheters in billing codes
U.S. Urinary Catheters Market Outlook:
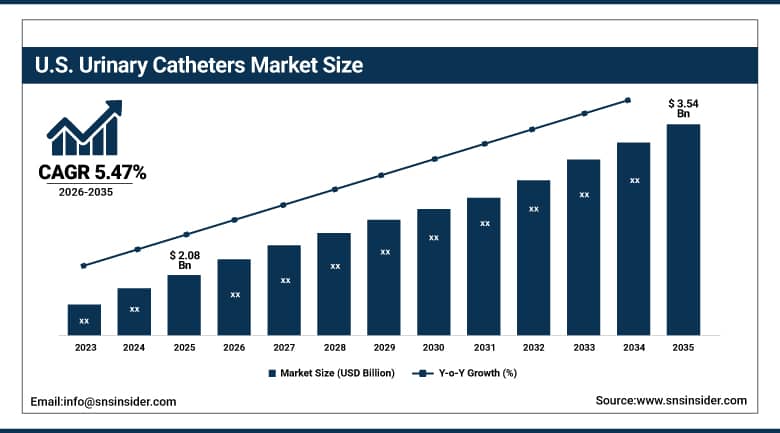
The U.S. Urinary Catheters Market was valued at USD 2.08 Billion in 2025 and is expected to reach USD 3.54 Billion by 2035, growing at a CAGR of 5.47% from 2026-2035.
The U.S. Urinary Catheters Market is the largest national market, supported by high rates of incontinence, prostate disease and spinal cord injury. Medicare and private insurers cover intermittent catheters for many patients, which supports home use. Direct-to-consumer suppliers deliver catheters to homes and handle claims. Hospitals focus on reducing infections, so they use catheters only when needed and favor coated and closed-system products. Female external catheters have grown quickly since their introduction. Manufacturers face recall risk and tight FDA oversight. Competitive bidding rules and billing codes influence product choice. Demand is expected to rise steadily as the population ages and as coverage widens.
⮞In April 2026, the Centers for Medicare & Medicaid Services confirmed that hydrophilic catheters have separate billing codes, A4295, A4296 and A4297, effective January 1, 2026. The change shows payers distinguishing coated products in reimbursement.
Urinary Catheters Market Segment Analysis:
-
By Product Type, the Intermittent Catheters segment dominated the Urinary Catheters Market with approximately 57.82% share in 2025, while the External Catheters segment is the fastest growing with a CAGR of approximately 7.07%.
-
By Coating, the Coated Catheters segment dominated the Urinary Catheters Market with approximately 61.12% share in 2025 and is also the fastest growing with a CAGR of approximately 6.62%.
-
By Application, the Urinary Incontinence segment dominated the Urinary Catheters Market with approximately 37.50% share in 2025, while the Spinal Cord Injury segment is the fastest growing with a CAGR of approximately 6.33%.
-
By End User, the Hospitals segment dominated the Urinary Catheters Market with approximately 50.68% share in 2025, while the Home Care segment is the fastest growing with a CAGR of approximately 7.26%.
-
By Gender, the Male segment dominated the Urinary Catheters Market with approximately 63.17% share in 2025, while the Female segment is the fastest growing with a CAGR of approximately 6.87%.
By Product Type, Intermittent Catheters Dominates the Urinary Catheters Market and External Catheters Grows Fastest
Intermittent catheters lead because clinical guidelines prefer them to long-term indwelling devices for people who cannot empty the bladder. Single-use insertion lowers the risk of biofilm and repeated infection, and users keep more independence and mobility. Spinal cord injury, spina bifida, multiple sclerosis and post-surgical retention create long-term daily demand. Hydrophilic and ready-to-use formats reduce urethral trauma and make catheterization more comfortable, which improves adherence. Reimbursement in the United States, the United Kingdom and many European countries covers intermittent supplies at home. Companies bundle catheters with delivery and support services, which builds repeat purchases.
External catheters are the fastest growing product because they avoid insertion into the urethra and remove a main route for infection. Female external devices that wick urine away have expanded quickly in hospitals, nursing homes and private homes, and male sheath designs have improved adhesion and comfort. Nurses value the lower workload and fewer skin injuries, and patients prefer the discretion. Hospitals use external options to cut catheter days, which supports infection reduction targets. New entrants are launching alternatives to established brands, and payers are beginning to define coverage. Indwelling Foley catheters remain essential for surgery, critical care and urinary retention.
⮞In August 2026, Coloplast reported organic growth of 7% in Continence Care in the first nine months of its 2025/26 fiscal year. The result shows steady demand for catheter-based continence products.
By Coating, Coated Catheters Dominates the Urinary Catheters Market and Is Also the Fastest Growing
Coated catheters lead because hydrophilic and gel layers reduce friction, which cuts urethral trauma, strictures and pain during repeated catheterization. Clinicians increasingly recommend them for long-term users, and guideline bodies in Europe and the United States favor low-friction products. Antimicrobial coatings with silver or other agents add protection in short-term hospital use. Manufacturers offer ready-to-use designs that remove the need to open a water sachet, which suits travel and work. Payers have started to create separate codes and coverage rules, which gives suppliers a clearer pathway. Uncoated catheters are now used mainly where cost is the main concern.
Coated devices are anticipated to record the highest growth due to the introduction of improved versions to tackle cost and sustainability issues. Compact and sleeved designs are being introduced by suppliers in order to minimize contamination through contact, and there are efforts towards designing recyclable packs. Coated catheters have found acceptance in emerging economies due to higher incomes and the availability of affordable devices made by local companies in China and India. Hospitals compare the effectiveness of hydrophilic and silver alloy catheters in reducing infections, but the effectiveness of medicated Foley catheters is still questionable.
⮞In its second quarter 2026 filing, Dentsply Sirona reported Wellspect net sales of USD 86 million. Wellspect sells the LoFric range of hydrophilic catheters, and the figure indicates the scale of this coated catheter business.
By Application, Urinary Incontinence Dominates the Urinary Catheters Market and Spinal Cord Injury Grows Fastest
Urinary incontinence leads applications because it is common among older adults, women after childbirth and people with neurological disease. Catheters are used when other treatments fail, when retention accompanies overflow leakage and for long-term management in care homes. Rising life expectancy and obesity increase the number of people affected. Awareness and willingness to seek care have improved, helped by telehealth visits and supply services that reduce embarrassment. Health systems are also adding bladder management programs for older adults at risk of falls and infections. These factors keep incontinence the largest source of catheter use.
Spinal cord injury is the fastest growing application, as survival after trauma improves and more patients live for decades with neurogenic bladder. These patients rely on daily intermittent catheterization and need large, regular supplies. Rehabilitation centers teach self-catheterization early, and coverage policies are widening for closed-system and hydrophilic products. Benign prostatic hyperplasia is another important driver because enlarged prostates cause retention, particularly in men over 60. Surgical use of indwelling catheters after prostate, bladder and gynecologic procedures also adds demand, although enhanced recovery protocols aim to remove catheters sooner.
⮞In April 2025, the U.S. National Institute of Diabetes and Digestive and Kidney Diseases noted that 90% of men over the age of 80 show histological evidence of benign prostatic hyperplasia. The finding underlines the large pool of older men at risk of urinary retention.
By End User, Hospitals Dominates the Urinary Catheters Market and Home Care Grows Fastest
Hospitals lead because acute care uses catheters during surgery, critical illness, emergency admission and recovery. Large systems buy through group purchasing contracts, which gives them access to a wide range of Foley and intermittent products. Nurses place and manage catheters under strict protocols, and infection control teams review each device's use. Hospitals are also where new catheters are tested and introduced, which influences later home use. Surgical volumes are rising as populations age, and prostate, gynecologic and orthopedic procedures often require short-term catheterization. These patterns sustain the segment's high share even as care shifts toward lower cost sites.
Home care is the fastest growing setting, since patients with chronic bladder dysfunction manage catheterization themselves. Supply services deliver catheters to homes and help with insurance claims, and telehealth reduces the need for clinic visits. Health systems encourage home management to free beds and cut hospital-acquired infections. Long-term care facilities and clinics add steady demand, supported by staffing programs and catheter reduction initiatives. Manufacturers design compact, discreet and easy-to-use products for travel and work, and they provide training and support apps. Reimbursement frameworks in several countries have widened coverage for home-based intermittent catheterization.
⮞In July 2025, the National Institute for Health and Care Excellence published guidance on intermittent catheters, which the MS Trust summarized as noting that over 95 million intermittent catheters are prescribed each year in the NHS. The volume shows the scale of home-based catheter use.
By Gender, Male Dominates the Urinary Catheters Market and Female Grows Fastest
Male patients lead because prostate disease, urethral strictures and age-related retention are common in men, and men account for many spinal cord injury cases. Male catheters are longer and often need coude tips or special designs, which increases the value per unit. Sheath-type external devices are also widely used by men with incontinence. Urologists treat prostate cancer, benign prostatic hyperplasia and post-surgical retention with catheters at high rates. Men are often introduced to intermittent catheterization after hospital stays, and they remain on therapy for long periods. These factors make male users the larger revenue base.
Female users are the fastest growing group as products designed for women improve. Compact, discreet catheters that fit in a handbag and shorter lengths make self-catheterization practical for women with neurogenic bladder, multiple sclerosis or pelvic floor disorders. Female external catheters have opened a new market for women with incontinence who would not use internal devices. Greater awareness, clinical guidelines for women and targeted marketing are increasing adoption. Companies are developing products that suit anatomy and dexterity needs, including gripping aids and sleeved formats. Growth is strongest where reimbursement covers women-specific catheter designs.
⮞In August 2026, Convatec reported in its first-half results that revenue from GentleCath Air for Women more than doubled. The growth shows rising demand for catheters designed for female users.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
83.12 |
|
Europe |
Germany |
28.46 |
|
Asia Pacific |
China |
34.84 |
|
Latin America |
Brazil |
62.17 |
|
Middle East & Africa |
Saudi Arabia |
26.53 |
North America Urinary Catheters Market Insights
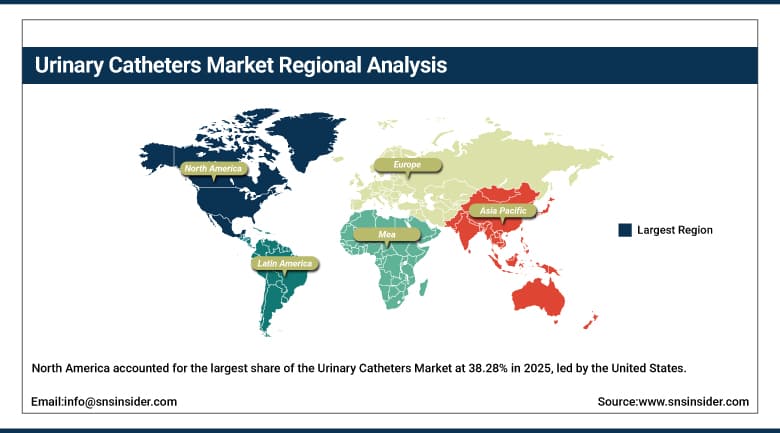
North America accounted for the largest share of the Urinary Catheters Market at 38.28% in 2025, led by the United States. High incontinence and prostate disease rates, broad insurance coverage and early adoption of hydrophilic and external catheters support spending. Direct-to-consumer suppliers deliver catheters to homes and manage claims, which builds recurring revenue. The region is home to several leading manufacturers, including BD, Hollister and Cardinal Health, and their research and marketing budgets shape product trends. Canada adds demand through provincial programs and an aging population.
Infection prevention rules shape purchasing. Medicare payment policies penalize hospital-acquired conditions, so hospitals reduce catheter use and prefer products with lower infection risk. The Food and Drug Administration reviews catheters through 510(k) clearance, and recalls occasionally disrupt supply. Reimbursement changes, such as separate coding for hydrophilic catheters, are altering product mix. Female external catheters and closed-system kits are gaining coverage. Nursing home operators and ambulatory surgical centers are also expanding purchases of catheter kits. Supply chain consolidation and tariffs on imported medical disposables are pushing manufacturers to review sourcing and pricing.
⮞In November 2025, Hollister said that from January 2026 every Medicare beneficiary diagnosed with a spinal cord injury would qualify for a closed system intermittent catheter, after it pursued a coverage change with the durable medical equipment Medicare administrative contractors. The change widens access to closed system products in the United States.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Urinary Catheters Market Insights
Europe is the second largest region and is led by Germany, the United Kingdom, France, Italy and the Nordic countries. National health systems and insurers reimburse intermittent catheters, so use among people with neurogenic bladder is high. Denmark, Sweden and the United Kingdom host leading manufacturers, including Coloplast, Wellspect and Convatec, which gives the region strong research and clinical education. Clinical guidance from bodies such as the European Association of Urology promotes intermittent catheterization and limits long-term indwelling use. National guidelines in the United Kingdom, Germany and France also set training standards for nurses and patients.
Regulation and cost control are central. The Medical Device Regulation increases certification requirements, and phase-outs of certain plasticizers push producers to reformulate PVC products. Tenders and framework agreements favor suppliers with proven supply reliability. Hospitals aim to reduce catheter-associated infections, which supports external and coated catheters. Sustainability policies are encouraging recyclable packaging. Home delivery services are expanding in the United Kingdom, Germany and the Nordic countries. Eastern European countries are widening reimbursement and hospital capacity, which should extend access to modern products over the forecast period.
⮞In September 2026, the UK Health Security Agency reported that 48.6% of E. coli bacteraemia cases in England in 2025 to 2026 had a urinary tract as the most likely primary focus. The burden of urinary infection keeps pressure on hospitals to limit catheter use and choose lower-risk devices.
Asia Pacific Urinary Catheters Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 7.14% during 2026-2035. China, Japan, India, South Korea and Australia lead demand. Japan has one of the oldest populations in the world, which drives use of catheters in hospitals and long-term care. China is expanding hospital capacity and local production of Foley and hydrophilic catheters. India has a large patient pool with prostate disease and spinal injuries, and producers such as Poly Medicure supply low-cost products. Rising incomes and insurance coverage increase access to intermittent catheters.
Price remains the main purchase criterion in many markets, so uncoated and PVC catheters keep a high share in public hospitals. Global suppliers are partnering with local distributors and building regional manufacturing to compete. Education of patients and nurses on self-catheterization is still limited, and reimbursement for home use is narrow in many countries. Medical device approvals are becoming faster in China and India, which helps new entrants. Medical tourism hubs in Thailand, Singapore and Malaysia add demand for advanced urology products. Government programs for elderly care are expected to raise volumes.
⮞In September 2026, Japan's Ministry of Internal Affairs and Communications reported that residents aged 65 or older reached a record 29.6% of the population. The aging trend supports long-term demand for urinary catheters in Japan.
MEA & Latin America Urinary Catheters Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Chile. Public systems purchase basic Foley catheters through tenders, while access to hydrophilic and intermittent products depends on municipal programs with set dispensing limits, court orders and private insurance. Rising chronic disease and a growing private hospital sector support demand. Local manufacturing is limited, so imports remain important, and exchange rate swings can affect prices. Distributors bundle catheters with bags and accessories, and public hospitals negotiate annual tenders that favor large suppliers. Patient associations and rehabilitation centers are raising awareness of self-catheterization, which is gradually shifting demand toward intermittent products.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar, Kuwait and South Africa lead demand. Gulf states are investing in hospitals and specialty care, and they import advanced catheters from global suppliers. Healthcare-associated infection control is a policy priority, which supports adoption of infection-reducing products and staff training. Across much of Africa, access to catheters is limited, and reusable or improvised devices are still used. Donor programs and spinal injury rehabilitation centers are working to improve supply.
⮞In August 2025, a study in the journal Microorganisms found that catheter-associated urinary tract infections accounted for 47.5% of healthcare-associated infections in intensive care units in the Aljouf region of Saudi Arabia. The result highlights the need for infection control in Gulf hospitals.
Market Dynamics:
Growth Drivers: Population Aging and Prostate Disease Burden Drive Growth in the Urinary Catheters Market
The increase in aging population is also associated with an increase in the cases of incontinence, retention, and prostrate diseases. Older individuals are prone to having dementia, stroke, diabetes, and limited mobility problems, which lead to difficulties in controlling their bladders. Also, older people are subject to more surgical operations such as orthopedic, cardiovascular and urology procedures, which involve catheterization. With the increase in life expectancy, patients will remain using intermittent catheterization for several years, which will lead to increased use throughout their lifetime. Governments invest in home and long-term care facilities, which will increase institutional use of catheters and drainage bags. Awareness about bladder health issues also promotes early detection and treatment.
Increase in the number of spinal cord injuries, multiple sclerosis, diabetes, and prostate cancer cases will attract young and middle-aged consumers. As rehabilitation treatments advance, patients will prefer intermittent catheterization to indwelling ones. Reimbursement for hydrophilic and closed system products is increasing, and also, suppliers provide education and delivery services, which help to increase compliance among patients. Emerging markets are developing hospital capacities and increasing insurance coverage, which increases access to catheters that were previously not affordable.
⮞In October 2025, the World Health Organization stated that by 2030, one in six people in the world will be aged 60 years or over. The shift enlarges the population with bladder and prostate conditions that require catheters.
Restraints: Infection Risk, Recalls and Reimbursement Pressure Restrain Growth in the Urinary Catheters Market
Catheter-associated UTI is the primary clinical risk. Prolonged use can cause biofilm formation, bacteriuria and sepsis, and hospitals incur penalties and must meet quality goals for preventable infections. Hence, healthcare providers tend to withdraw the catheter as soon as possible and use alternative devices, including external catheters, bladder scanners and timed voiding. This reduces catheter utilization per patient and allows reducing the volume of classic Foley catheters. Pain, urethral injury and social stigma also have an adverse impact on patients' adherence to intermittent catheterization. Lack of training among nurses and different insertion technique also increase the number of complications in hospitals and care facilities.
Recalls and regulations also create additional cost and risk factors. Manufacturing defect, such as contamination with foreign substances or protrusion of catheter tips, can provoke product recall and negatively influence supply chain and reputation. Reimbursement policies vary significantly in other countries, and public insurance usually does not cover premium hydrophilic and external products. Price pressure from cheaper Chinese producers narrows margins, while phase-out of certain plasticizers makes re-formulation necessary. Clinical testing and regulatory compliance is expensive, and small manufacturers cannot afford to do that in some product categories. Lack of professional nurses hampers implementation of self-catheterization.
⮞In June 2026, Medline Industries recalled convenience kits containing Bard Silastic Foley catheters after the catheter manufacturer reported an increased amount of raw material on the surface of the catheter. The Class 2 recall shows the quality and supply risks in catheter kits.
Opportunities: Female External Catheters and Smart Infection Detection Create Opportunities in the Urinary Catheters Market
Female external catheters and other non-invasive designs are creating new demand among patients who avoid internal devices. Hospitals adopt them to reduce catheter days and infections, and nursing homes use them to lower staff workload and skin injury. Wider reimbursement in the United States and Europe would extend use to home care. Manufacturers can add value through improved adhesion, wicking materials, compact pumps and discreet packaging. Early evidence of lower infection rates helps hospitals justify the higher unit price compared with simple drainage devices. Suppliers that pair products with nurse education can secure long-term contracts with hospital groups and home care providers.
Smart catheters and sensors represent another avenue of opportunity. Scientists are working on developing sensors that will help in detecting presence of bacteria or blood in urine and alerting phones and monitors. Such innovations will enable early treatment and reduction of complications among long-term catheter users. Anti-microbial coating, biofilm resistance and bladder measurement technologies are some of the technologies being researched. Collaboration between catheter manufacturers, health facilities and IT firms is important in ensuring rapid market uptake. Growth in emerging markets represents a potential opportunity due to increased income levels, expansion of hospitals’ infrastructure and development of insurance programs for catheter products.
⮞In February 2026, Texas A&M University engineers reported a sensor that detected E. coli in a laboratory bladder model at lower levels than traditional methods in as few as three to nine hours. The preclinical result points to future smart catheter and diagnostic features.
Recent Developments:
-
In October 2026, Urolution Medical received U.S. FDA 510(k) clearance for its OpenFlo Urinary Catheter, an indwelling catheter for urinary tract drainage in adult patients for indwell periods of up to 30 days. Clinical studies are still being prepared, which positions the product as an early-stage entrant in the Foley segment.
-
In May 2026, BD received U.S. FDA 510(k) clearance, through its C.R. Bard unit, for the BD Touchless Plus unisex pre-lubricated urethral catheter kit. The clearance extends the company's intermittent catheter range for home and hospital users.
-
In December 2025, Teleflex announced an agreement to sell its Acute Care and Interventional Urology businesses to Intersurgical for about USD 530 million. The Federal Trade Commission issued a second request in March 2026, and the sale was still pending when the company reported second quarter results in August 2026.
-
In September 2026, Convatec launched Cure Aqua, a ready-to-use hydrophilic intermittent catheter, initially in the United States and Canada, with other markets to follow. The launch widens the choice for people who self-catheterize and strengthens the company's coated catheter portfolio.
Urinary Catheters Market Key Players:
-
Coloplast A/S
-
Hollister Incorporated
-
Convatec Group plc
-
Wellspect HealthCare (Dentsply Sirona)
-
Becton, Dickinson and Company (C.R. Bard)
-
Teleflex Incorporated
-
B. Braun Melsungen AG
-
Cardinal Health, Inc.
-
Medline Industries, LP
-
Poiesis Medical LLC
-
HR Healthcare
-
Poly Medicure Ltd
-
Well Lead Medical Co., Ltd.
-
Guangdong Ecan Medical Co., Ltd.
-
Hangzhou Jimushi Meditech Co., Ltd.
-
Chengdu Daxan Innovative Medical Technology Co., Ltd.
-
Amsino International, Inc.
Urinary Catheters Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.53 Billion |
| Market Size by 2035 | USD 11.12 Billion |
| CAGR | CAGR of 5.47% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Intermittent Catheters, Indwelling Catheters, and External Catheters) • By Coating (Coated Catheters and Uncoated Catheters) • By Application (Urinary Incontinence, Benign Prostatic Hyperplasia, Spinal Cord Injury, Post-Surgical Urinary Retention, and Other Applications) • By End User (Hospitals, Home Care, Long-Term Care Facilities, and Clinics) • By Gender (Male and Female) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Coloplast A/S, Hollister Incorporated, Convatec Group plc, Wellspect HealthCare (Dentsply Sirona), Becton, Dickinson and Company (C.R. Bard), Teleflex Incorporated, B. Braun Melsungen AG, Cardinal Health, Inc., Medline Industries, LP, Poiesis Medical LLC, HR Healthcare, Poly Medicure Ltd, Well Lead Medical Co., Ltd., Guangdong Ecan Medical Co., Ltd., Hangzhou Jimushi Meditech Co., Ltd., Chengdu Daxan Innovative Medical Technology Co., Ltd., Amsino International, Inc. |

Frequently Asked Questions
Key players include Coloplast, Hollister, Convatec, Wellspect HealthCare (Dentsply Sirona), BD (C.R. Bard), Teleflex, B. Braun, Cardinal Health, Medline, Poiesis Medical, HR Healthcare, Poly Medicure, Well Lead Medical, Guangdong Ecan Medical, Hangzhou Jimushi Meditech, Chengdu Daxan Innovative Medical Technology and Amsino International.
Key opportunities include female external catheters, antimicrobial and ready-to-use coated catheters, smart infection-detecting catheters and home care supply services in emerging markets.
Population aging, rising prostate disease and incontinence, and the shift of catheter care to the home are the main growth factors.
By Product Type, the Intermittent Catheters segment dominated the market in 2025 with an estimated 57.82% share, supported by clinical guidelines that favor single-use catheterization.
North America dominated the market with a share of 38.28% in 2025, driven by high disease prevalence, broad insurance coverage and early adoption of advanced catheters.
