
Virtual Clinical Trials Market Report Scope & Overview:
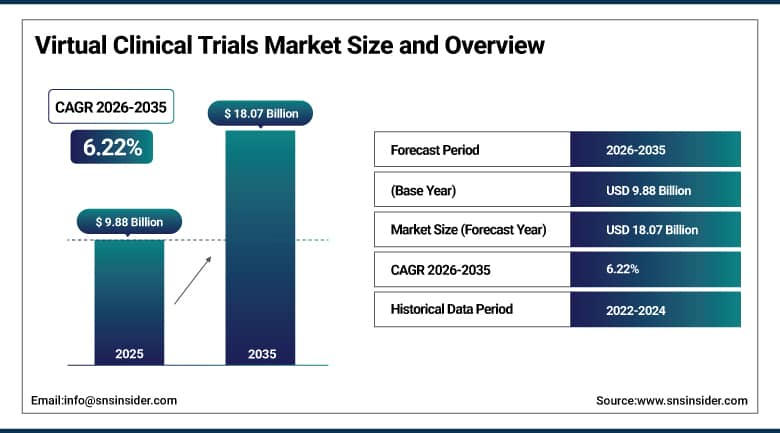
The Virtual Clinical Trials Market was valued at USD 9.88 Billion in 2025 and is expected to reach USD 18.07 Billion by 2035, growing at a CAGR of 6.22% from 2026-2035.
The Virtual Clinical Trials Market consists of approaches to decentralized clinical research based on digital technologies such as telemedicine, wearable sensors, electronic data capture, and e-consent, allowing one to perform the clinical study in its entirety or at least some of its parts remotely without the need to bring patients to centralized clinical trial sites. The demand for decentralized clinical trials is supported by the need for sponsors to speed up the drug development process, enhance enrollment diversity, and minimize patient burden, with the World Health Organization pointing out that decentralization and digitalization of clinical trials can help cut down patient dropouts by as much as 30%, thus increasing the reliability and efficiency of trials.
In March 2025, ICON plc became the first large clinical research organization to fully integrate Medidata's Clinical Data Studio into its clinical workflows, immediately deploying the platform across its studies to differentiate its data management and review capabilities. The integration, built on a partnership spanning more than 1,700 studies and over 400 active studies across oncology, central nervous system, and vaccine therapeutic areas, illustrates how leading CROs are consolidating previously separate data management and central monitoring functions into unified clinical data science platforms, a shift that is directly accelerating the operational efficiency gains sponsors expect from virtual and hybrid trial designs.
To Get More Information On Virtual Clinical Trials Market - Request Free Sample Report
Virtual Clinical Trials Market Trends
- Growing integration of unified clinical data science platforms combining data management and central monitoring.
- Rising adoption of hybrid trial designs combining in-person and remote data collection elements.
- Expanding use of AI-driven patient recruitment platforms to improve enrollment diversity and speed.
- Increasing deployment of wearable devices and remote monitoring tools for real-time trial data collection.
- Continued regulatory modernization clarifying decentralized trial conduct requirements in the U.S. and EU.
U.S. Virtual Clinical Trials Market Outlook
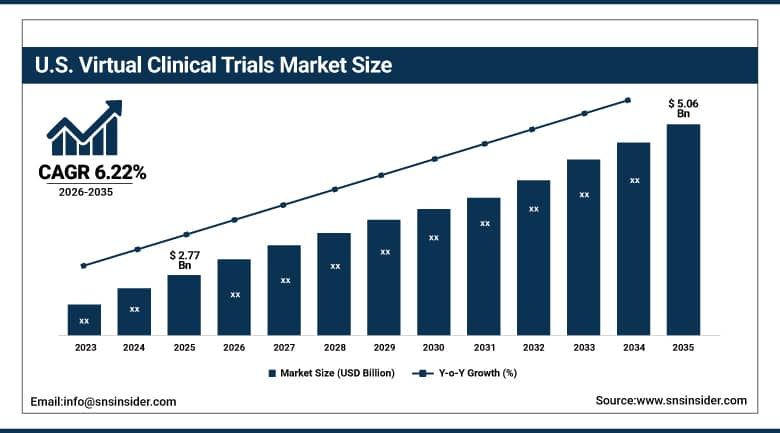
The U.S. Virtual Clinical Trials Market was valued at USD 2.77 Billion in 2025 and is expected to reach USD 5.06 Billion by 2035, growing at a CAGR of 6.22% from 2026-2035.
The United States continues to be a dominant market for virtual clinical trials, thanks to the high density of pharmaceutical sponsors, CROs, and providers of clinical technology, together with the evolving regulatory framework at the FDA that gives the sponsor guidelines on how to conduct virtual clinical trials. The use of wearable devices, mHealth apps, and remote monitoring technologies has made it easy for patients' data to be collected and transmitted instantly, thus improving data collection and increasing patient interaction. Technology companies in the domestic sector, like Medidata, Oracle, and Veeva Systems, have strong ties with both sponsors and CROs.
In October 2024, Medidata launched Medidata Rave Lite, a simplified data collection and management solution designed to help research teams conduct trials more efficiently while maintaining compliance with regulatory standards, followed in November 2024 by an expanded partnership between Medidata and Bioforum aimed at improving data management and trial efficiency. These product and partnership developments reflect a broader domestic trend of clinical technology vendors introducing streamlined, faster-to-deploy platform tiers alongside their flagship enterprise offerings, expanding decentralized trial technology access to smaller sponsors and mid-sized CROs that may lack the resources to implement full-scale enterprise platforms.
Virtual Clinical Trials Market Segment Analysis
- By Study Design, the Interventional segment dominated the Virtual Clinical Trials Market with approximately 46.80% share in 2025, while the Observational segment is the fastest growing with a CAGR of approximately 7.85%.
- By Therapeutic Area, the Oncology segment dominated the Virtual Clinical Trials Market with approximately 32.90% share in 2025, while the CNS segment is the fastest growing with a CAGR of approximately 8.20%.
- By Phase, the Phase II segment dominated the Virtual Clinical Trials Market with approximately 40.50% share in 2025, while the Phase III segment is the fastest growing with a CAGR of approximately 7.50%.
By Study Design, Interventional dominates, and Observational grows fastest
Interventional trials held the largest study-design share in 2025, reflecting their central role in evaluating the safety and efficacy of novel medications, therapies, and medical devices, which represents the core regulatory pathway sponsors must complete to bring new treatments to market regardless of trial delivery format.
Observational studies are the fastest-growing study-design segment as sponsors and academic researchers increasingly leverage digital tools, including electronic health records and remote monitoring, to conduct large-scale, long-duration real-world evidence studies that would be logistically difficult to execute through traditional site-based visits. The lower regulatory complexity of observational designs relative to interventional trials makes them a natural entry point for organizations building initial decentralized trial capability.
By Therapeutic Area, Oncology dominates, and CNS grows fastest
Oncology held the largest therapeutic-area share in 2025, reflecting the sheer volume of active cancer drug development programs globally and oncology sponsors' growing use of decentralized elements to improve enrollment access for patients who may live far from specialized cancer treatment centers.
CNS is the fastest-growing therapeutic-area segment as neurological and psychiatric drug development increasingly incorporates remote cognitive assessment tools, digital biomarkers, and wearable-based motor function monitoring that can capture clinically meaningful data outside traditional clinic visits. This capability is particularly valuable for CNS conditions where symptom fluctuation and functional status are difficult to fully capture during infrequent in-person visits.
By Phase, Phase II dominates, and Phase III grows fastest
Phase II trials held the largest phase share in 2025, driven by their critical role in assessing treatment efficacy and safety signals before sponsors commit to larger, more expensive Phase III programs, making Phase II a natural point for sponsors to pilot decentralized trial elements before scaling them further.
Phase III is the fastest-growing phase segment as sponsors increasingly apply decentralized elements to large-scale confirmatory trials to automate data collection, increase patient engagement and retention, and access more diverse patient populations across broader geographies. Pharmaceutical companies are increasingly conducting virtual elements alongside traditional on-site visits in Phase III and Phase IV programs specifically to capture additional real-world data from diverse patient populations.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
83.20 |
|
Europe |
Germany |
27.45 |
|
Asia Pacific |
China |
36.60 |
|
Middle East & Africa |
United Arab Emirates |
31.90 |
|
Latin America |
Brazil |
44.75 |
North America Virtual Clinical Trials Market Insights
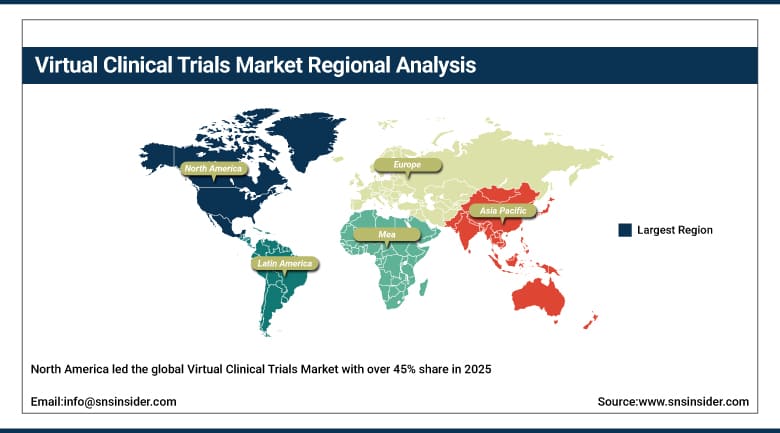
North America led the global Virtual Clinical Trials Market with over 45% share in 2025, generating substantial regional revenue, driven by increasing demand for decentralized clinical research, rising adoption of digital health technologies, and the concentration of major pharmaceutical sponsors and clinical technology vendors headquartered in the region. The United States accounted for the substantial majority of regional demand, supported by an evolving FDA regulatory framework that provides sponsors with formal guidance on decentralized trial conduct.
Canada contributes additional regional demand through its own growing clinical research infrastructure and academic medical center participation in decentralized trial networks. Continued technology platform innovation from leading North American vendors is expected to sustain the region's leading market position through the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Virtual Clinical Trials Market Insights
Asia Pacific emerges as the most rapidly growing regional market in the Virtual Clinical Trials Market, growing at a compound annual rate of about 8.45% through the forecast period of 2026-2035 owing to increasing investments in drug discovery and development activities along with increasing digital health technology adoption in countries such as China, India, and Japan. Increasing adoption of decentralized technologies in clinical trial programs in the growing domestic biopharmaceuticals industry of China is driving the regional demand.
Increasing demand for virtual/hybrid clinical trials in order to effectively recruit dispersed patient populations owing to the presence of large and diverse patient pools along with investments in clinical research infrastructure in India is driving incremental demand in the region. Increasing regulatory reforms and investments in digital health infrastructure in the region are expected to drive the demand further in the coming years.
Europe Virtual Clinical Trials Market Insights
Europe represents a significant virtual clinical trials market, supported by strong clinical research infrastructure, regulatory modernization, and increasing investment in digital health technologies across Germany, the United Kingdom, France, Italy, Spain, and the Netherlands. Germany leads regional demand, supported by its large pharmaceutical and biotechnology research base.
The European Commission's updated recommendation paper on decentralized elements, published in October 2025, alongside ICH E6(R3)'s decentralized-specific annex becoming legally effective across the EU in January 2027, is providing sponsors with an increasingly clear regulatory pathway for remote trial conduct. Continued regulatory harmonization is expected to support steady regional demand growth through the forecast period.
MEA & Latin America Virtual Clinical Trials Market Insights
The Middle East & Africa virtual clinical trials market is at an early but growing stage of development, with the United Arab Emirata driving regional demand as the country invests in clinical research infrastructure and positions itself as a regional hub for pharmaceutical trial activity as healthcare systems continue to modernize.
Latin America is witnessing growing adoption of remote clinical research technologies as healthcare systems continue to modernize, with Brazil representing the region's primary point of engagement given its established clinical research infrastructure and large, diverse patient population attractive to global sponsors seeking geographic enrollment diversity.
Market Dynamics
Growth Drivers: Drug Development Acceleration and Enrollment Diversity
Accelerating the development process and lowering costs involved in developing novel therapeutic options still constitute the key factors behind virtual clinical trials' adoption because the decentralized components of such projects can help lower participant dropout and enhance data integrity compared to the conventional site-based trial design, which is helpful for faster completion of clinical research programs.
Increasing focus on enrolling a diverse study population based not only on the regulatory requirements but also on sponsor's understanding that the geographic restriction of the conventional site-based trial recruitment procedure might affect the study population negatively makes the mentioned factor even stronger for promoting the adoption of virtual clinical trials.
Restraints: Data Security Concerns and Technology Integration Complexity
Data security and privacy concerns associated with collecting sensitive health information through remote digital platforms remain a meaningful restraint, as sponsors and technology vendors must navigate complex regulatory requirements, including 21 CFR Part 11 compliance in the United States, while ensuring participant data remains protected throughout the trial lifecycle.
The complexity of integrating multiple decentralized trial technology components, spanning e-consent, remote monitoring devices, telemedicine platforms, and electronic data capture systems, into a single coherent trial workflow continues to constrain adoption among smaller sponsors and CROs lacking dedicated digital trial technology expertise. This integration complexity is a key factor motivating the platform consolidation trend among leading clinical technology vendors.
Opportunities: AI-Driven Recruitment and Unified Data Science Platforms
The integration of AI-driven patient recruitment and matching platforms presents a significant opportunity to reduce trial enrollment timelines, which remain one of the most significant sources of delay and cost in clinical drug development, by more efficiently identifying and engaging eligible patients across broader geographic areas than traditional site-based recruitment can reach.
The consolidation of previously separate data management, central monitoring, and clinical data review functions into unified clinical data science platforms, exemplified by ICON's full integration of Medidata's Clinical Data Studio, presents a further opportunity for CROs and technology vendors to capture higher-value, platform-based service revenue. Vendors and CROs successfully executing this platform consolidation are positioned to capture a growing share of sponsor technology spending as decentralized and hybrid trial adoption continues to expand.
Recent Developments:
- 2026- IQVIA and Duke Clinical Research Institute announced a strategic collaboration combining IQVIA's analytics, AI, and clinical technology infrastructure with DCRI's academic research expertise to improve trial design and real-world evidence development.
- 2025- The European Commission published an updated Recommendation Paper on decentralized elements in clinical trials, ahead of ICH E6(R3)'s decentralized-specific annex becoming legally effective in the EU in January 2027.
- 2024- Medidata and Bioforum strengthened their partnership to improve data management, optimize trial efficiency, and support development of innovative treatments.
Virtual Clinical Trials Market Key Players
- ICON plc
- Parexel International Corporation
- IQVIA Holdings Inc.
- Labcorp Drug Development (Covance)
- Medidata Solutions (Dassault Systèmes)
- Oracle Corporation
- Clinical Ink, Inc.
- Medable, Inc.
- Signant Health
- Veeva Systems Inc.
- WCG Clinical, Inc.
- Science 37, Inc.
- Castor
- THREAD
- Illingworth Research Group
- ActiGraph LLC
- Cardinal Health, Inc.
- Clario (Thermo Fisher Scientific)
- LEO Innovation Lab
- Halo Health Systems
Virtual Clinical Trials Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.88 Billion |
| Market Size by 2035 | USD 18.07 Billion |
| CAGR | CAGR of 6.22% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Study Design (Interventional, Observational, and Expanded Access) • By Therapeutic Area (Oncology, CNS, Cardiovascular Disease, Autoimmune/Inflammation, Infectious Disease, and Metabolic/Endocrinology) • By Phase (Phase I, Phase II, Phase III, and Phase IV) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | ICON plc; Parexel International Corporation; IQVIA Holdings Inc.; Labcorp Drug Development (Covance); Medidata Solutions (Dassault Systèmes); Oracle Corporation; Clinical Ink, Inc.; Medable, Inc.; Signant Health; Veeva Systems Inc.; WCG Clinical, Inc.; Science 37, Inc.; Castor; THREAD; Illingworth Research Group; ActiGraph LLC; Cardinal Health, Inc.; Clario (Thermo Fisher Scientific); LEO Innovation Lab; Halo Health Systems. |
Frequently Asked Questions
Key players in the Virtual Clinical Trials Market include ICON plc, Parexel International Corporation, IQVIA Holdings Inc., Labcorp Drug Development, and Medidata Solutions, among others.
Key opportunities lie in AI-driven patient recruitment platforms that reduce enrollment timelines, and in unified clinical data science platforms that consolidate data management and central monitoring functions.
Sponsors' need to accelerate drug development timelines and improve enrollment diversity, supported by evolving decentralized trial regulatory frameworks, is the major growth factor.
By Study Design, the Interventional segment dominated the Virtual Clinical Trials Market with approximately 46.80% share in 2025.
North America dominated the Virtual Clinical Trials Market with over 45% share in 2025, supported by a dense concentration of pharmaceutical sponsors and clinical technology vendors.
