
Acne Treatment Market Report Scope & Overview:
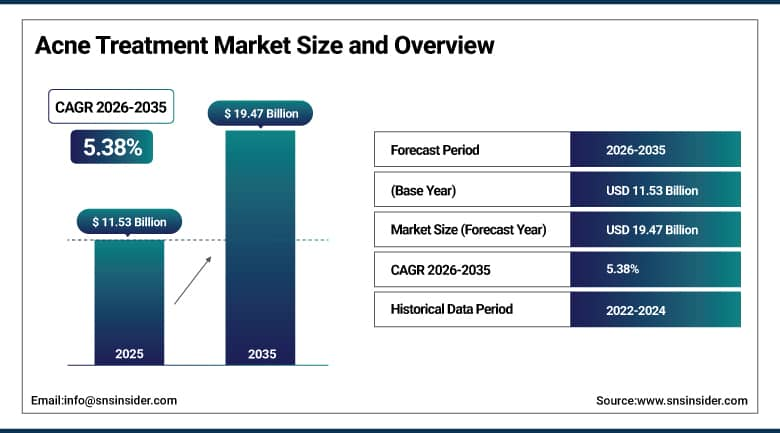
The Acne Treatment Market was valued at USD 11.53 Billion in 2025 and is estimated at USD 12.15 Billion in 2026. It is projected to reach USD 19.47 Billion by 2035, advancing at a CAGR of 5.38% from 2026 to 2035. Acne vulgaris is among the most common skin conditions worldwide, and it drives steady purchases of topical and oral medicines, from over-the-counter cleansers and gels to prescription retinoids, antibiotics, and hormonal agents. New combination products, prescription-to-over-the-counter switches, and online dermatology services are widening access and keeping patients on treatment for longer.
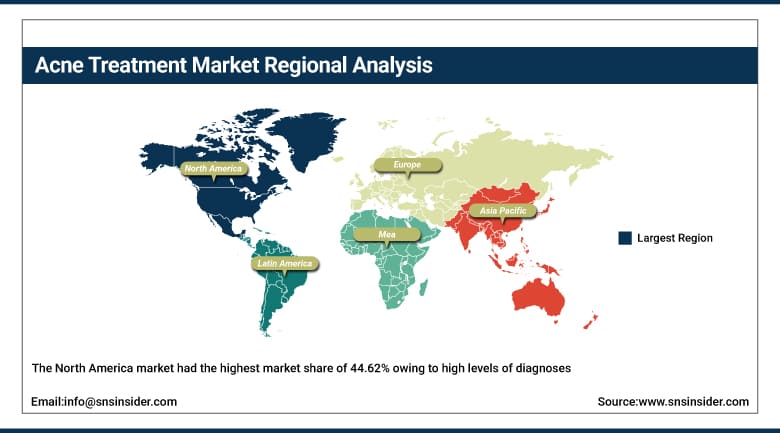
The North America region accounted for the largest share in 2025 at 44.62%. This is due to high treatments, insurance coverage, and presence of a sizable OTC segment. The European region follows, with a well-developed system of dermatology in place. However, the most rapid growth in the forecast period will be observed in the Asia Pacific, where increasing incomes coupled with the awareness of skin care needs in China, India, and South East Asia will propel growth. Latin America and MEA are relatively smaller, but are benefiting from the growth of retail pharmacies as well as rising demands for dermatology consultations in metropolitan areas.
To Get More Information On Acne Treatment Market - Request Free Sample Report
Key Report Takeaways:
-
By drug class, antibiotics held a 26.40% share in 2025, while retinoids are the fastest growing.
-
By route of administration, topical products accounted for a 51.67% share in 2025, while oral treatments are the fastest growing.
-
By acne type, inflammatory acne represented a 54.17% share in 2025, while non-inflammatory acne is the fastest growing.
-
By distribution channel, retail pharmacies commanded a 47.93% share in 2025, while online pharmacies are the fastest growing.
-
By region, North America led with a 44.62% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights:
Prescription-to-over-the-counter switches are widening the consumer market. Combination gels that once required a prescription are reaching pharmacy shelves, which lets patients begin treatment earlier and shifts part of the spending from clinics to retail channels, while manufacturers invest in brand building and dermatologist education.
Fixed-dose combination topicals are replacing multi-step regimens. Products that pair benzoyl peroxide, a retinoid, and an antibiotic in one tube simplify routines and support adherence, and developers are reformulating older molecules into foams, gels, and microencapsulated forms that reduce irritation and improve tolerability.
Non-antibiotic and hormone-targeted options are gaining attention as prescribers limit long courses of oral antibiotics. Androgen receptor inhibitors applied to the skin, newer retinoids, and research into the skin microbiome are broadening the range of choices and giving dermatologists alternatives for patients who cannot tolerate or no longer respond to existing drugs.
Telehealth and e-commerce are changing how treatment is delivered. Online dermatology platforms, subscription pharmacies, and image-based assessment tools allow patients to receive prescriptions without waiting for a clinic visit, and they create a steady refill pattern that supports recurring revenue for suppliers.
Drivers Impact Analysis:
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising Acne Prevalence Among Adolescents and Adults |
+2.18% |
Global |
Long term (4 years or more) |
|
New Approvals and Product Launches |
+1.92% |
North America, Europe, and Asia Pacific |
Medium term (2 to 4 years) |
|
Over-the-Counter Expansion and Online Dermatology |
+1.57% |
North America and Europe |
Short term (2 years or less) |
|
Skin-Health Awareness and Social Media Influence |
+1.26% |
Global |
Medium term (2 to 4 years) |
|
Rising Disposable Income in Emerging Economies |
+1.04% |
Asia Pacific, Latin America, and Middle East & Africa |
Long term (4 years or more) |
Rising Acne Prevalence Among Adolescents and Adults
Acne begins in adolescence for most people, and it increasingly persists into adulthood, especially among women. The American Academy of Dermatology reports that acne affects up to 50 million Americans a year, and similar patterns appear in Europe and Asia. Hormonal change, stress, diet, and cosmetic use are cited as contributing factors. Because treatment often lasts months or years and relapse is common, patients return to pharmacies and clinics repeatedly, which sustains volume across prescription and over-the-counter products and supports demand for maintenance therapy.
New Approvals and Product Launches
The pipeline of acne products has become more active, with novel mechanisms and improved formulations reaching patients. The European Commission authorized clascoterone cream for acne vulgaris in October 2025, giving prescribers a non-antibiotic topical option in a large market, and U.S. regulators approved a two-ingredient gel for over-the-counter use. China has also widened access to a newer oral antibiotic designed for acne. Each approval draws marketing support, physician education, and payer attention, and expands the number of products competing for patients.
Over-the-Counter Expansion and Online Dermatology
Consumers increasingly manage mild and moderate acne without a clinic visit, buying gels, washes, and spot treatments from pharmacies, mass retailers, and e-commerce platforms. Switches from prescription to over-the-counter status extend this behavior to stronger actives, while teledermatology services shorten the time between symptom onset and treatment. Online pharmacies add convenience, subscription refills, and wider product choice. These channels lower the barrier to starting therapy, attract younger patients who prefer digital interactions, and help brands build loyalty through direct engagement.
Skin-Health Awareness and Social Media Influence
The use of social media has brought out issues related to skin appearance in teenagers and young adults, prompting interest in evidence-based therapies. The medical community, including dermatologists and educators, exchange knowledge and reviews of products that encourage people to visit for earlier treatment, despite the fact that there is misinformation out there. With more awareness, people adhere to skincare regimens, seek prescriptions and try innovations. Companies target this market through influencers and education and thus promote their products, resulting in expansion in mature as well as developing countries.
Rising Disposable Income in Emerging Economies
Growing middle-class populations in Asia Pacific, Latin America, and the Middle East & Africa are spending more on health and personal care, including dermatology. Urbanization, pollution, and changing diets are linked to higher acne rates, while expanding retail pharmacy chains and private clinics make treatment easier to find. Local manufacturers and global suppliers are introducing products at several price points, and regulatory approvals in large countries are opening additional channels. These shifts support steady volume growth from 2026 through the end of the forecast period.
Restraints Impact Analysis:
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Side Effects and Tolerability Concerns |
-0.94% |
Global |
Long term (4 years or more) |
|
Antibiotic Resistance and Stewardship Pressure |
-0.78% |
North America and Europe |
Medium term (2 to 4 years) |
|
Poor Treatment Adherence and Discontinuation |
-0.51% |
Global |
Long term (4 years or more) |
|
Isotretinoin Access Rules and Dermatology Capacity Limits |
-0.36% |
North America |
Short term (2 years or less) |
Side Effects and Tolerability Concerns
Many effective acne medicines cause dryness, redness, peeling, or sun sensitivity, and some oral drugs carry warnings about liver effects or pregnancy risk. Patients who experience irritation often stop treatment early or switch products, which reduces repeat purchases and slows the uptake of stronger actives. Manufacturers invest in gentler vehicles and counseling materials, but concerns about safety and appearance during treatment continue to limit use, especially among younger patients and those with sensitive skin. Clinicians counsel patients about expected side effects and suggest gradual introduction, though early dropout still affects sales of newer prescription brands.
Antibiotic Resistance and Stewardship Pressure
Use of long-term topical and systemic antibiotics has caused resistance among bacteria, and there is a call by the professionals to limit the duration of these drugs. The American Academy of Dermatology recently revised its guideline on the treatment of acne in February 2024, where it recommends using benzoyl peroxide, retinoids, and combinations as the primary treatment and limiting the use of oral antibiotics. Doctors have started opting for other forms of medication; hence, this limits the usage of old antibiotics as well as affects the prices of generic drugs, despite new drugs being available.
Poor Treatment Adherence and Discontinuation
Acne treatment demands consistent use for weeks before improvement appears, and many patients stop early because results seem slow or routines feel complicated. Missed doses and abandoned prescriptions lower the revenue that each patient generates over a treatment course. Simplified regimens, fixed-dose combinations, reminders, and telehealth follow-up are intended to improve persistence, but adherence remains a structural limit on category growth, particularly among adolescents who manage treatment on their own. Adolescents often rely on parents for refills, and cost or inconvenience can end a course before benefits appear. Producers therefore test packaging that tracks dosing and supports caregivers.
Isotretinoin Access Rules and Dermatology Capacity Limits
Isotretinoin remains the most effective option for severe acne, yet its use in the United States is governed by a risk management program that requires registration, monitoring, and pregnancy prevention steps. The Food and Drug Administration approved modifications to ease the program, although implementation has been delayed. Long waits to see a dermatologist in many regions add friction for patients who need prescriptions, which slows access to advanced therapy and pushes some patients toward lower-cost products. Telehealth is easing some of these barriers but not all.
Acne Treatment Market Segment Analysis:
By Drug Class, Antibiotics Dominate Acne Treatment Market; Retinoids to Register Fastest Growth.
The share of antibiotics was 26.40% in 2025 due to the use of topical clindamycin and oral tetracycline-based medications that are frequently prescribed for inflammatory acne. The generic form keeps the cost low, and doctors have much experience in prescribing them. They are combined with benzoyl peroxide in order to avoid resistance, which facilitates the continuation of prescriptions. Recommendations to prescribe them in shorter terms are decreasing the volume, but the drug class is still the most popular one. Pharmacists recommend them as an inexpensive initial option, thus prescriptions are still high among all age categories.
The highest CAGR of 6.62% in 2026-2035 belongs to the retinoids market segment. Topical retinoids can be used to treat comedones and inflammation, and recent forms increase the tolerance level. Isotretinoin is still considered the drug of choice in severe cases. Guidelines and over-the-counter drugs containing adapalene increase the number of users, and there is some demand coming from the use of benzoyl peroxide, hormonal agents, and combination medications. Dermatologists often combine retinoids with other drugs in order to achieve quicker results.
By Route of Administration, Topical Dominates Acne Treatment Market; Oral to Register Fastest Growth.
Topical products accounted for a 51.67% share in 2025 because most acne is mild to moderate and is treated with gels, creams, lotions, and foams applied directly to the skin. They are available over the counter and by prescription, carry fewer systemic risks, and are recommended as first-line therapy. Innovation in vehicles and combinations keeps this route central to treatment pathways and patient preference. Pharmacies stock many strengths, so patients can step up treatment without delay. Self-care is common.
Oral treatments are expected to register the fastest growth, with a CAGR of 6.41% from 2026 to 2035. Patients with moderate to severe or widespread acne turn to oral antibiotics, hormonal agents, and isotretinoin when topical care fails. Growth in telehealth prescribing and newer oral options supports uptake. Injectable and other routes remain small, but they serve patients with cystic lesions who need rapid relief from pain and swelling. Dermatologists weigh pregnancy risk and monitoring needs when selecting these options.
By Acne Type, Inflammatory Acne Dominates Acne Treatment Market; Non-Inflammatory Acne to Register Fastest Growth.
Inflammatory acne represented a 54.17% share in 2025 because papules, pustules, and nodules cause visible lesions, discomfort, and scarring risk that motivate patients to seek treatment. These cases usually require prescription products, often combining antimicrobial and retinoid actives, and they involve repeat visits. Higher spending per patient makes this type the largest contributor to category value across both topical and oral therapy. Scarring risk further raises the urgency of treating these lesions promptly. Prescribers act quickly on them.
Growth is estimated to be rapid for non-inflammatory acne at a CAGR of 6.04% between 2026 and 2035. The prevalence of comedonal acne, a type that affects mostly teenagers, has been increasing and treatment includes OTC retinoids, salicylic acid, and benzoyl peroxide. Increased awareness about skincare routines along with the early use to prevent acne have been expanding this segment of consumers, which consists mostly of retail and online pharmacy buyers. Parents and schools play a role in early purchases.
By Distribution Channel, Retail Pharmacies Dominate Acne Treatment Market; Online Pharmacies to Register Fastest Growth.
Retail pharmacies held a 47.93% share in 2025 since most people receive medications through neighborhood and retail chain pharmacies. Pharmacists give advice, and insurance companies also route payments through these pharmacies. Large availability of branded washes and gels on shelves also helps generate impulse and repeat buying, making retail pharmacies better than hospital pharmacies where the volume is lower and limited to serious conditions. Loyalty programs from large chains also contribute to this channel remaining ahead of the hospital pharmacy channel in most countries.
Online pharmacies have been estimated to have the highest growth rate of 7.78% from 2026 to 2035. Subscription refills, teledermatology tie-ins, discount plans, and home delivery will attract younger buyers that feel more comfortable with online buying. Brands are also developing direct-to-consumer websites and marketplaces to cater to these demands. Hospital pharmacies will continue catering to patients on isotretinoin and other complex regimens, but with a slower growth rate. Mail order will also be promoted in some countries by payers in an effort to save money.
Geography Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.30% |
|
Europe |
Germany |
22.47% |
|
Asia Pacific |
China |
31.58% |
|
Latin America |
Brazil |
44.11% |
|
Middle East & Africa |
Saudi Arabia |
26.83% |
North America Acne Treatment Market
The North America market had the highest market share of 44.62% owing to high levels of diagnoses, adequate insurance coverage, and sizeable over-the-counter categories. The USA had the highest regional demand with a 2025 valuation of USD 4.39 Billion, projected to have an average annual growth rate of 5.54% between 2026 and 2035. Demand in Canada benefits from public plan coverage of new products. Which brands are covered is influenced by pharmacy benefit managers and commercial insurance companies, so manufacturers negotiate rebates and provide savings card.
There are many branded and generic products available to dermatologists in the region. Manufacturers spend heavily on advertising and sampling. Switching from prescription to over-the-counter medications leads to higher sales through retailers, as well as telehealth systems broaden the scope of availability in rural regions. Long waiting periods for consultations with specialists drive patients to online portals and pharmacies' recommendations. Thus, there is steady growth in refills and repeat purchase. There are also marketing activities aimed directly at consumers and social media outreach that increase teenagers' and parents' awareness, so sales of branded and over-the-counter products are steady.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Acne Treatment Market
Europe is a mature market with universal healthcare coverage in most countries and a strong tradition of dermatology care. Germany, the United Kingdom, France, Italy, and Spain account for most regional spending. Authorization of a new topical hormone-targeted option across the European Union has added a prescription alternative, and launches are rolling out country by country. Spain and Italy also show growing demand for pharmacy-based dermocosmetic acne ranges, which sit alongside prescription therapy for mild and moderate cases. Rules are broadly similar across the bloc.
Reimbursement rules vary widely, and several countries limit coverage for cosmetic skin concerns, which keeps part of the market in self-pay and pharmacy channels. Antibiotic stewardship programs encourage alternative treatments, while online pharmacies are growing in Germany and the Nordic countries. Cosmetic and dermocosmetic brands also compete strongly in mild acne, adding pressure on prices. Smaller markets in Eastern Europe are catching up gradually as local pharmacies expand their dermatology ranges and clinicians adopt updated guidelines. Price competition intensifies as patents expire.
Asia Pacific Acne Treatment Market
The Asia Pacific region will be the fastest-growing regional market with a CAGR of 7.03% during 2026-2035. There are a significant number of adolescents and youth in China and India, and increasing disposable income has increased expenditures on dermatology. Regulatory approval of products in China has increased the availability of new prescription products, while Japan and South Korea continue their advanced practice in dermatology and skincare culture. The volume contribution from India comes from a high volume of generics produced and increasing online pharmacies. Demand is concentrated in cities.
The importance of e-commerce channels cannot be underestimated, and a significant number of people purchase acne treatments from online retailers and through social media commerce. The availability of lower-cost generics and herbal treatment options by local producers, along with collaborations between global vendors and regional licensees, helps attract new patients. High levels of urban pollution and changes in dietary habits have been correlated to increase acne prevalence and support demand in metropolitan areas. Several countries have government-sponsored healthcare initiatives that include dermatology training for healthcare professionals, thus expanding the base of prescribers.
Latin America Acne Treatment Market
Latin America is a developing market where spending comes mainly from Brazil and Mexico. Cultural interest in physical appearance, developed private dermatology sector, and increased chain pharmacies play a role in driving demand. Consumers buy directly from pharmacists and the local producers provide affordable generics for both topical and oral treatment options. Mexico also makes its contribution due to the increasing number of private clinics and affordable pharmacy chains providing consultations along with medications. The hospitals in Sao Paulo and Mexico City also operate dermatology clinics that impact the prescribing practices around the country.
Exchange rate fluctuations and cost of imports may impact the pricing for the branded drugs while the level of governmental insurance of the condition is low. Nonetheless, growing incomes, social media impact, and expansion of online pharmacies contribute to the increase of the number of patients. Demand from Argentina, Colombia, and Chile is also increasing while regional distributors assist international players in navigating the regulatory process of registration and distribution. The regional dermatology associations conduct educational campaigns promoting early treatment while the international players are increasingly localizing their packaging and pricing.
Middle East & Africa Acne Treatment Market
The Middle East & Africa represents the lowest proportion but demand is growing due to increased adoption of private hospitals, medical tourism, and retail pharmacies in Gulf nations. Saudi Arabia and UAE are leading in dermatology prescriptions, backed by high expenditure on personal care items and young demographics. South Africa continues to dominate in sub-Saharan Africa markets. Turkey and Egypt contribute consistently with larger population base and growing number of private pharmacies stocking foreign brands. The younger generations are responsible for higher demand for premium brands.
Weather and sunlight determine the choice of products, and clinicians focus on tolerance and sunscreen in retinoid formulations. Access to dermatologists is restricted in most areas other than major cities, making pharmacy stores very important in terms of recommendation and sales. Foreign players collaborate with local distributors for obtaining registration, and the growth can be expected from a relatively small base. Teledermatology and online pharmacies are also becoming more popular among consumers in smaller cities, thus slowly increasing the addressable base.
Competitive Landscape:
The competitive landscape combines global dermatology specialists, diversified pharmaceutical companies, generic manufacturers, and consumer health brands. Leading suppliers compete on novel mechanisms, fixed-dose combinations, tolerability, and the ability to move products from prescription to over-the-counter status, while generic producers compete on price in antibiotics, retinoids, and benzoyl peroxide. Concentration is moderate, because several branded franchises coexist with many regional makers.
Strategies center on lifecycle management, regional licensing, and partnerships that extend reach into Europe, China, and Canada. Companies pursue acquisitions of small dermatology brands, invest in telehealth and direct-to-consumer channels, and run clinical programs aimed at adolescents and adult women. Smaller firms differentiate through novel delivery systems, microencapsulation, and non-antibiotic mechanisms that appeal to prescribers seeking alternatives.
Acne Treatment Market Industry Leaders:
1. Galderma: Dermatology specialist whose Differin adapalene and Epiduo franchises span prescription and over-the-counter acne care.
2. Bausch Health: Parent of Ortho Dermatologics, which markets Cabtreo, a triple-combination gel of clindamycin, adapalene, and benzoyl peroxide.
3. Sun Pharma: Indian drug maker that holds rights to Winlevi (clascoterone) in North America and sells a broad dermatology portfolio.
4. Almirall: Spanish dermatology company that markets Seysara (sarecycline), an oral antibiotic approved for moderate to severe acne.
5. Glenmark Pharmaceuticals: Indian pharmaceutical company that licenses Winlevi for Europe and South Africa and sells dermatology products across emerging markets.
Companies Covered in this Report:
-
Galderma
-
Bausch Health
-
Sun Pharma
-
Almirall
-
Glenmark Pharmaceuticals
-
Cosmo Pharmaceuticals
-
Journey Medical
-
Mayne Pharma
-
Sol-Gel Technologies
-
Cipher Pharmaceuticals
-
Cutia Therapeutics
-
Biofrontera
Recent Industry Developments:
-
April 2025: Mayne Pharma acquired exclusive U.S. rights to the acne products Epsolay and Twyneo from their developer.
-
July 2025: Bausch Health Canada secured public plan coverage for Cabtreo in Ontario and Nova Scotia.
-
October 2025: Cosmo Pharmaceuticals received European Commission authorization for Winlevi (clascoterone) in acne vulgaris.
-
January 2026: Almirall announced China approval of Seysara (sarecycline) with its partner Sinomune.
-
February 2026: Sol-Gel Technologies obtained marketing approval for Twyneo in Israel.
-
March 2026: Biofrontera reported positive Phase 2b results for Ameluz photodynamic therapy in moderate to severe acne.
-
May 2026: Galderma received U.S. FDA approval for Differin Epiduo Acne Gel as an over-the-counter treatment.
-
June 2026: Glenmark Pharmaceuticals launched Winlevi in the Nordic countries, Central and Eastern Europe, and Spain.
Scope and Research Methodology
This report defines the Acne Treatment Market as the commercial value of prescription and over-the-counter medicines used to treat acne vulgaris, including topical and oral antibiotics, retinoids, benzoyl peroxide, hormonal agents, and combination products. Cleansers and cosmetics sold only for skin care, light-based devices, and procedures such as peels are excluded. Values are stated in USD at manufacturer selling prices for prescription products and at retail sell-out for over-the-counter products. The base year is 2025 and the forecast runs from 2026 to 2035. Veterinary products and nutritional supplements marketed for skin health are also excluded from the estimates. Free samples are not counted.
Primary research comprised interviews with dermatologists, pharmacists, hospital pharmacy managers, distributors, and executives at branded and generic manufacturers. Secondary research drew on regulatory approvals, health agency statistics, clinical guidelines, company filings, product labels, and professional society publications. Prescription volumes were linked to acne prevalence, diagnosis rates, and treatment patterns in each country, then converted to value using price points and channel mix. Each interview followed a structured guide covering prescribing habits, formulary decisions, price points, switching behavior, and adoption barriers, and responses were coded by region and by clinician type so that patterns could be compared across countries.
A bottom-up build by drug class, route, and country was cross-checked against a top-down view based on dermatology spending and population. Forecasts apply growth rates by segment that reflect launches, generic erosion, over-the-counter switches, and pricing trends, with scenarios for regulatory change. Regional shares were validated against pharmacy density and dermatologist availability, and the five regions sum to the global figure. Findings were reviewed by internal analysts and external experts before release. Where estimates differed, analysts revisited assumptions on prescription counts and prices and consulted additional experts until the figures converged. Final forecasts were approved after internal peer review of every regional table.
Acne Treatment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.53 Billion |
| Market Size by 2035 | USD 19.47 Billion |
| CAGR | CAGR of 5.38% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Drug Class (Antibiotics, Retinoids, Benzoyl Peroxide, Hormonal Agents, and Combination and Other Drugs) • By Route of Administration (Topical, Oral, and Others) • By Acne Type (Inflammatory and Non-Inflammatory) • By Distribution Channel (Retail Pharmacies, Hospital Pharmacies, and Online Pharmacies) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Galderma, Bausch Health, Sun Pharma, Almirall, Glenmark Pharmaceuticals, Cosmo Pharmaceuticals, Journey Medical, Mayne Pharma, Sol-Gel Technologies, Cipher Pharmaceuticals, Cutia Therapeutics, Biofrontera |

Frequently Asked Questions
The market was valued at USD 11.53 Billion in 2025 and is estimated at USD 12.15 Billion in 2026. It is forecast to reach USD 19.47 Billion by 2035.
The market is projected to expand at a CAGR of 5.38% from 2026 to 2035.
North America led with a 44.62% share in 2025, while Asia Pacific is the fastest-growing region, with a CAGR of 7.03% from 2026 to 2035.
Antibiotics held the largest share, at 26.40% in 2025, while retinoids are expected to grow fastest.
Online pharmacies are expected to record the fastest growth, with a CAGR of 7.78% from 2026 to 2035.
The market is projected to expand at a CAGR of 5.38% from 2026 to 2035.
Rising acne prevalence, new approvals and launches, over-the-counter expansion and online dermatology, skin-health awareness, and rising incomes in emerging economies.
Side effects, antibiotic resistance and stewardship pressure, poor adherence, and isotretinoin access rules and dermatology capacity limits
