
Architectural, Engineering, And Construction Services Market Report Scope & Overview:
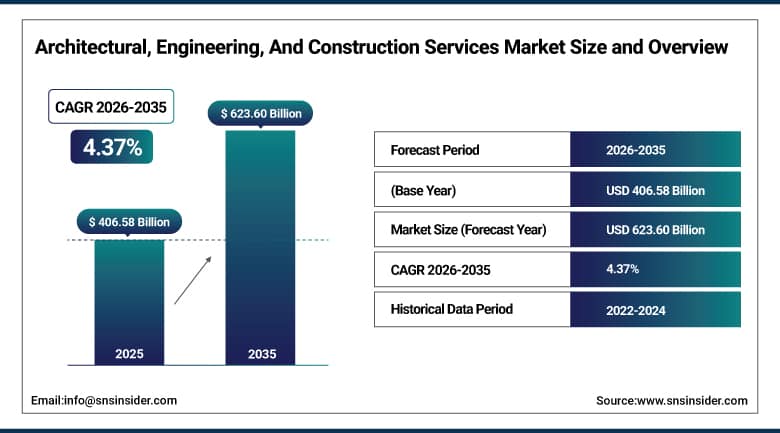
The Architectural, Engineering, And Construction Services Market size was valued at USD 406.58 Billion in 2025 and is expected to reach USD 424.35 Billion in 2026, rising to USD 623.60 Billion by 2035. The market is forecast to expand at a CAGR of 4.37% during 2026–2035. These services cover the design, engineering, planning, project management and construction oversight that owners buy to deliver buildings, transport networks, energy plants, water systems and industrial facilities. Public agencies, developers, utilities and industrial companies hire specialist firms to manage technical risk, meet codes and complete projects on time and within budget.
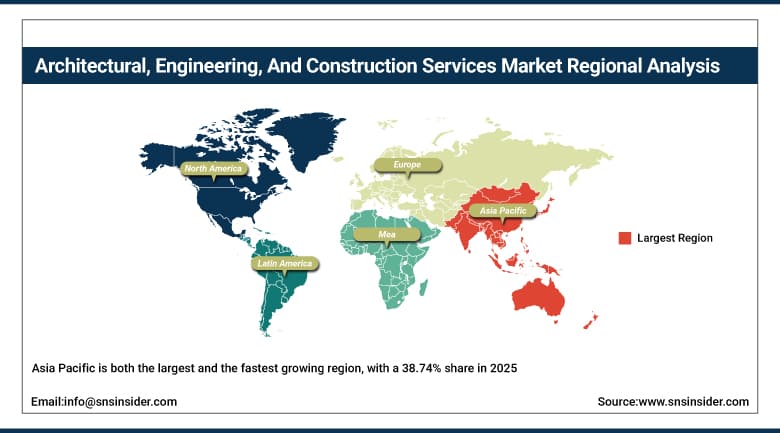
Asia Pacific accounted for the largest share of the market, at 38.74% in 2025, because of heavy spending on housing, transport, industrial parks and urban development in China, India and Southeast Asia. North America follows, supported by infrastructure funding, data center and energy projects, and a large base of established engineering firms. Asia Pacific is also the fastest growing region, as governments raise public investment and more owners outsource design and delivery. Europe contributes through renovation, rail and energy transition work, while Middle East & Africa and Latin America add large projects.
To Get More Information On Architectural, Engineering, And Construction Services Market - Request Free Sample Report
Key Report Takeaways
- By service type, construction and project management held 32.46% in 2025, while engineering services are the fastest growing.
- By end use, residential held 33.72% in 2025, while infrastructure and energy is the fastest growing.
- By delivery model, design-bid-build held 41.62% in 2025, while design-build is the fastest growing.
- By client type, private clients held 58.43% in 2025, while public clients are the fastest growing.
- By region, Asia Pacific held 38.74% in 2025 and is also the fastest growing.
Market Trends and Insights
Firms are moving from drawings and site supervision toward integrated advisory work that includes energy modeling, carbon accounting, program management and digital delivery. Owners increasingly select partners that can follow a project from concept through commissioning, and large firms use acquisitions to add specialist engineering teams.
Building information modeling, digital twins, drone surveys and generative design tools are shortening design cycles and reducing rework. Prefabrication and modular methods are also changing how designers and project managers coordinate work, and demand is rising for data centers, grid upgrades, water systems and resilience projects.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising infrastructure and urbanization investment |
+1.82% |
Asia Pacific and Middle East & Africa |
Long term (4 years or more) |
|
Energy transition and data center construction |
+1.47% |
North America and Asia Pacific |
Medium term (2 to 4 years) |
|
Adoption of digital design, BIM and digital twins |
+1.21% |
Global |
Medium term (2 to 4 years) |
|
Sustainability and green building regulation |
+0.96% |
Europe and North America |
Long term (4 years or more) |
|
Outsourcing of design and project management by public agencies |
+0.62% |
Global |
Short term (2 years or less) |
Rising Infrastructure and Urbanization Investment
Governments are funding roads, rail, ports, airports, water systems and affordable housing to support growing cities and replace aging assets. Large national programs in India, China, Saudi Arabia and Southeast Asia, together with renewal budgets in the United States and Europe, create a long pipeline of work. Each project requires planning, design, cost control and supervision, so spending on assets translates directly into fees for architectural, engineering and construction management firms. Development banks and sovereign funds provide financing that keeps these projects moving.
Energy Transition and Data Center Construction
Utilities and developers are building transmission lines, substations, solar and wind farms, storage plants, hydrogen facilities and large data centers. These projects involve complex electrical, civil and environmental design, and owners rely on specialist engineers to manage permits, grid connection and schedule risk. Rapid growth in digital infrastructure and power demand is lifting engineering workloads, and firms with energy and technology expertise are gaining share. Owners also hire consultants early to secure land, power and approvals, which lengthens engagements and raises fees per project.
Adoption of Digital Design, BIM and Digital Twins
Building information modeling, cloud collaboration, digital twins and artificial intelligence tools allow teams to detect clashes early, estimate quantities and simulate performance before construction starts. Public agencies and large owners increasingly require digital models in tenders, which raises standards for design firms. Better data also supports facility management after handover, creating additional service lines for firms that can offer digital advisory work. Cloud platforms also let teams in different countries work on one model, which helps firms take on larger and more complex projects without adding staff.
Sustainability and Green Building Regulation
Energy codes, carbon reporting rules, green building certifications and climate resilience requirements are raising the technical content of design and engineering work. Owners seek help with life cycle assessment, retrofit planning, low carbon materials and net zero strategies. Renovation of older buildings is a growing source of fees, particularly in Europe, where large stocks of inefficient buildings must be upgraded. Insurers, lenders and tenants also ask for evidence of resilience and low emissions, so certification and performance modeling are becoming standard parts of the design scope on large projects.
Outsourcing of Design and Project Management by Public Agencies
Public agencies often lack the staff to deliver large capital programs, so they hire consultants for program management, design review, inspection and cost control. Framework contracts and multi-year agreements give firms visible revenue, and governments increasingly use private sector expertise to deliver projects faster. This trend supports firms with large teams, strong records and the financial capacity to bid for major programs. Concession and partnership models add to outsourcing, because investors want independent advisers to review designs, costs and progress on behalf of lenders.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Skilled labor shortage and wage pressure |
-0.94% |
Global |
Medium term (2 to 4 years) |
|
Project delays, cost overruns and interest rate pressure |
-0.58% |
North America and Europe |
Short term (2 years or less) |
|
Fee pressure and competitive bidding |
-0.12% |
Global |
Short term (2 years or less) |
|
Fragmented regulation and permitting delays |
-0.07% |
Global |
Long term (4 years or more) |
Skilled Labor Shortage and Wage Pressure
Firms compete for licensed architects, civil, structural, electrical and mechanical engineers, and experienced project managers, and many of these professionals are approaching retirement. Higher salaries squeeze margins, and a lack of staff can delay delivery or force firms to decline work. Training new engineers takes years, so labor constraints are likely to remain a limit on how quickly firms can expand. Firms respond with graduate programs, offshore delivery centers and automation of routine drawing work, but experienced engineers remain scarce and costly to replace.
Project Delays, Cost Overruns and Interest Rate Pressure
High financing costs, tariffs and material price swings lead developers to delay or cancel projects, which reduces demand for design and management services. The American Institute of Architects reported that its Architecture Billings Index stood at 48.3 in April 2026, down from 49.8 in March, and a reading below 50 means more firms saw billings fall than rise. Commercial and office work has been weakest. Contractors also face supply chain delays that stretch schedules, and public agencies sometimes pause approvals.
Fee Pressure and Competitive Bidding
Public tenders and large owners often award contracts on price, and fixed-fee agreements expose firms to cost overruns if scope expands. New entrants, regional firms and in-house teams add competition, while clients push for lower rates on repeat work. Firms must balance growth with profitability, and weak bids can erode margins even when order books look strong. Clients increasingly ask for success-based fees and cost guarantees, and one misjudged estimate on a fixed-price contract can erase the profit of a whole program.
Fragmented Regulation and Permitting Delays
Building codes, licensing rules and approval processes differ across countries, states and cities, which complicates work for firms that operate across borders. Slow permitting and environmental review can pause projects for years, delaying fees. Professional liability and insurance costs also vary by region, and firms must invest in compliance teams to manage these differences. Slow approvals raise holding costs for developers, who then postpone new commissions, so delays in one part of the chain reduce order flow for design firms.
Architectural, Engineering, And Construction Services Market Segment Analysis
By End Use, Residential Dominates Architectural, Engineering, And Construction Services Market; Infrastructure and Energy to Register Fastest Growth.
Residential accounts for 33.72% of the market in 2025 because housing is built in every country, and developers use architects, engineers and managers on apartment blocks, townhouses, communities and renovation projects. Urbanization in Asia, Africa and the Middle East, along with housing shortages in North America and Europe, keeps project volumes high. Developers also commission urban planning and interior design alongside the main building design, which broadens the fee base for full-service practices working on large mixed-use projects.
Infrastructure and energy is expected to expand at a CAGR of 6.12% from 2026 to 2035. Roads, rail, ports, airports, water systems, transmission lines and renewable plants are funded by public budgets and development banks, and each project requires large design and management teams. Energy transition spending adds work that grows faster than building construction. Government funding for decarbonization and resilience adds further work, and project timelines of several years give providers steady backlog. Backlogs stay strong and visible.
By Service Type, Construction and Project Management Dominates Architectural, Engineering, And Construction Services Market; Engineering to Register Fastest Growth.
Construction and project management accounts for 32.46% of the market in 2025 because owners need experts to manage cost, schedule, quality and contractors on projects of every size. Fees are tied to the value of construction, so rising project volumes raise revenue. Public agencies and developers hire these teams for programs that run across several years. Large owners also hire project managers to represent them during procurement, which adds to fees for firms with strong delivery records. Fees follow budgets.
Engineering services are projected to grow at a CAGR of 5.47% during 2026–2035. Power, transport, water and industrial projects need civil, structural, electrical and environmental design, and energy transition programs require specialist skills. Firms with strong technical teams benefit from the long lead times of these projects. Demand also comes from owners who need independent inspection and quality oversight, and the shortage of skilled engineers makes experienced teams more valuable. Energy and water skills are especially valued by clients.
By Delivery Model, Design-Bid-Build Dominates Architectural, Engineering, And Construction Services Market; Design-Build to Register Fastest Growth.
Design-bid-build holds a 41.62% share in 2025 because public agencies have used the model for decades, and procurement rules in many countries still require it. Owners like the clear separation between designers and contractors, and design firms earn fees early in the project. The method is familiar to firms, lenders and regulators. Fixed procurement rules and long-standing contract forms mean many smaller projects continue to follow the traditional route, which keeps the model dominant in public work. Public work follows.
Design-build is projected to grow at a CAGR of 5.93% during 2026–2035. A single team handles design and construction, which shortens schedules and reduces disputes, and owners value the single point of responsibility. Wider legal acceptance for public projects and the rise of data centers and industrial plants support adoption. Experienced teams also win repeat work because owners value reliable delivery, and early contractor involvement improves cost certainty on complex facilities. Owners also appreciate faster mobilization on urgent projects.
By Client Type, Private Clients Dominate Architectural, Engineering, And Construction Services Market; Public Clients to Register Fastest Growth.
Private clients account for 58.43% of the market in 2025 because developers, industrial companies, utilities, hospitals and commercial owners commission most buildings and plants. They award work on technical ability and relationships, and repeat engagements are common. Private investment in logistics, housing and data centers keeps volumes high. Large corporate owners often keep long-term relationships with a few preferred firms, which supports recurring revenue across multiple sites and regions. Corporate clients value speed and pay more for specialist advice.
Public clients are expected to grow at a CAGR of 5.08% from 2026 to 2035. Governments are funding transport, water, energy and social infrastructure and are outsourcing more program management and design review. Multi-year framework contracts give firms steady revenue and make public work attractive even at lower margins. Development banks and national funds also co-finance projects, and this brings in international firms with experience in complex procurement. Public programs follow national budgets and long-term development plans, which aids visibility.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
87.94% |
|
Europe |
Germany |
18.47% |
|
Asia Pacific |
China |
41.23% |
|
Middle East & Africa |
Saudi Arabia |
36.58% |
|
Latin America |
Brazil |
44.26% |
Asia Pacific Architectural, Engineering, And Construction Services Market
Asia Pacific is both the largest and the fastest growing region, with a 38.74% share in 2025 and a projected CAGR of 5.62% over 2026–2035. China leads the region, with large programs in housing, rail, power and urban renewal, and local firms operate alongside global consultants. Government spending keeps project pipelines full. Singapore and Hong Kong are regional hubs for design and engineering talent, and global firms use them to serve projects across the wider region. Large cities lead demand.
India is expanding highways, metros, airports and housing, and its engineering firms win work at home and abroad. Japan, South Korea and Australia are mature markets with strong renovation and energy demand, while Indonesia, Vietnam and Singapore add projects tied to industrial parks, ports and data centers. Rapid urban population growth in Southeast Asia and South Asia creates demand for transit, sanitation and affordable housing that local and international consultants share. Public transit expansion is a priority in most large cities, and consultants win work on stations and depots.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Architectural, Engineering, And Construction Services Market
North America held 27.68% of the market in 2025, led by the United States. The U.S. market was valued at USD 98.97 Billion in 2025 and is expected to register a CAGR of 3.86% during 2026–2035. Federal infrastructure funding, data centers, power grid upgrades and industrial reshoring support demand, and a deep base of design and engineering firms serves it. The country also has a large base of mid-sized engineering firms that serve state departments of transportation, utilities and school districts across the nation.
Canada adds demand through energy, mining, transport and housing programs, and many U.S. firms operate across the border. Mexico is counted in Latin America, although manufacturing investment links it closely to North American supply chains. High interest rates have slowed commercial building, but public and energy work remains strong. State and local governments award a large share of design contracts, and the pipeline of water, transit and bridge projects supports firms with public sector experience. Contractors and owners compete for skilled staff.
Europe Architectural, Engineering, And Construction Services Market
Europe accounted for 23.11% of the market in 2025, with Germany as the leading country. The region has a mature construction sector, strong engineering traditions and some of the largest consulting firms in the world. Demand is driven by renovation of aging buildings, rail and grid investment, and climate rules. Large engineering groups from the region also bid for projects in Asia, Africa and the Middle East, using their records on complex buildings and transit systems. Austria and Switzerland also have strong practices.
The United Kingdom, France, the Netherlands, the Nordic countries and Italy are important markets. European firms are active in sustainability consulting and often expand through acquisitions of smaller specialists, and they export services to other regions. Competition is strong, and clients expect firms to show experience with digital delivery and carbon reduction on their previous projects. Spain and Poland are growing markets for infrastructure funded by regional programs, and Eastern European countries are upgrading roads, rail and energy systems with European funds.
Middle East & Africa Architectural, Engineering, And Construction Services Market
Middle East & Africa held 5.84% of the market in 2025. Saudi Arabia and the United Arab Emirates lead regional demand, with giga-projects, new cities, airports, energy plants and tourism developments that need design and program management on a large scale. Global consultants hold major roles. Public investment funds back most large projects, and international firms often partner with local companies to meet requirements for in-country participation. Saudi Arabia has awarded multi-year program management contracts for new cities and transport networks, and international firms form joint ventures with local companies.
Qatar, Egypt, Kuwait and Oman add projects, and South Africa, Nigeria and Kenya are active in Africa. Development banks fund roads, power and water systems, although financing gaps and political risk affect timing. Egypt is building new administrative and transport hubs, and Gulf states are investing in desalination, rail and renewable energy that require specialist design and program management. Morocco, Algeria and Tanzania are investing in ports and rail, and consulting firms are opening regional offices to serve clients that are expanding their national infrastructure programs over the next decade.
Latin America Architectural, Engineering, And Construction Services Market
Latin America accounted for 4.63% of the market in 2025, with Brazil as the leading country. Brazil has a large construction sector with demand from housing, roads, ports, sanitation and energy. Mexico is the second major market, supported by industrial plants, logistics parks and nearshoring investment. Public-private partnerships and concessions are common, and international lenders require independent engineers, which creates steady demand for technical advisory firms. Argentina has a long record of engineering consultancies that serve energy and mining clients, while currency swings slow decisions.
Chile, Colombia, Peru and Argentina add mining, energy and transport projects. Public budgets and currency swings affect the pace of work, and private concessions are an important source of infrastructure delivery. Mining and energy projects in Chile and Peru require specialized engineering, and growing urban transport systems in Bogota and Santiago add further work for consultants. Panama and Costa Rica add canal, port and tourism development, while governments in the region increasingly use concession models to bring in private capital and international design firms for major roads and airports.
Competitive Landscape
The Architectural, Engineering, And Construction Services Market is fragmented. A group of global consulting firms handle large infrastructure, energy and building programs, while thousands of regional and local practices serve housing, commercial and municipal work. Competition rests on technical expertise, reputation, price, delivery record and the ability to field large teams.
Vendors pursue acquisitions of specialist firms, digital tools, sustainability advisory services and long-term framework contracts.
Architectural, Engineering, And Construction Services Market Industry Leaders
1. AECOM: U.S. infrastructure consulting firm with global design and program management teams.
2. Jacobs: U.S. engineering and technology services company.
3. WSP Global: Canadian professional services firm in engineering and design.
4. Stantec: Canadian design and engineering company.
5. Arcadis: Dutch design and consultancy firm for natural and built assets.
Companies Covered in this Report
- AECOM
- Jacobs
- WSP Global
- Stantec
- Arcadis
- Tetra Tech
- Sweco
- Kimley-Horn
- HDR
- Gensler
Recent Industry Developments
- April 2025: AECOM acquired Allen Gordon, a Scotland-based water and energy consultancy.
- January 2026: Tetra Tech acquired Halvik Corp., a federal technology and digital transformation services firm.
- May 2026: Jacobs completed the acquisition of the remaining stake in PA Consulting.
- July 2026: WSP Global made a takeover offer for Arcadis.
- July 2026: Kimley-Horn agreed to acquire Belka Engineering Associates, an electrical engineering firm.
- July 2026: Atwell acquired NEI Electric Power Engineering, a transmission, substation and power systems engineering firm.
Scope and Research Methodology
This study estimates the Architectural, Engineering, And Construction Services Market for 2025 as the base year and forecasts it through 2035. The scope covers professional architectural design, engineering design, program and construction management, and related advisory services sold to owners and developers. Values are reported in USD at the point of sale by service providers. Physical construction work, building materials and design software licenses are outside the scope. Segmentation covers service type, end use, delivery model, client type and region, and both public and private commissions are included. All values are rounded to two decimals. Prices exclude taxes.
Secondary research included company annual reports, investor presentations and filings, government and regulator databases, professional association data, tender records and peer-reviewed and industry publications. Primary research consisted of structured interviews and surveys with executives, practice leaders, project directors, owners and procurement managers. These inputs were used to validate fee levels, project volumes and the share of each service line. Interviews covered practice leaders, project directors, public agency officials and private developers, which allowed assumptions on fee rates, backlog and win rates to be tested against practice. Responses were cross-checked against filings.
Market size was built from the bottom up using firm revenue, project pipelines and fee rates, and was cross-checked from the top down against construction spending in each region. Triangulation across these views fixed the base year value. Forecasts consider public investment, interest rates, material costs and labor supply, and segment and regional shares were assigned from activity patterns in each setting. An analyst quality review checked consistency before release. The forecast was run under conservative, base and optimistic cases, and growth rates for each segment were set so that the parts remain consistent with the whole. Estimates are reviewed periodically as new data becomes available. Peer comparisons were also reviewed. Documentation is retained.
Architectural, Engineering, And Construction Services Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 406.58 Billion |
| Market Size by 2035 | USD 623.60 Billion |
| CAGR | CAGR of 4.37% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type (Construction and Project Management, Engineering, Architectural Design, and Others) • By End Use (Residential, Commercial, Industrial, and Infrastructure and Energy) • By Delivery Model (Design-Bid-Build, Design-Build, Construction Management at Risk, and Integrated Project Delivery) • By Client Type (Private and Public) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | AECOM, Jacobs, WSP Global, Stantec, Arcadis, Tetra Tech, Sweco, Kimley-Horn, HDR, Gensler |

Frequently Asked Questions
The market was valued at USD 406.58 Billion in 2025 and is projected to reach USD 623.60 Billion by 2035, growing at a CAGR of 4.37% during 2026–2035.
Asia Pacific leads, with a 38.74% share in 2025, and is also expected to grow fastest, at a CAGR of 5.62% during 2026–2035.
Construction and project management, residential, design-bid-build and private clients lead, while engineering, infrastructure and energy, design-build and public clients grow fastest.
Infrastructure investment, the energy transition, data centers, digital design tools and sustainability rules drive demand.
AECOM, Jacobs, WSP Global, Stantec and Arcadis lead, along with Tetra Tech, Sweco, Kimley-Horn, HDR and Gensler.
Labor shortages, project delays and high interest rates, fee pressure and fragmented regulation restrain faster growth.
