
Autonomous Ocean Wave Monitor Market Report Scope & Overview:
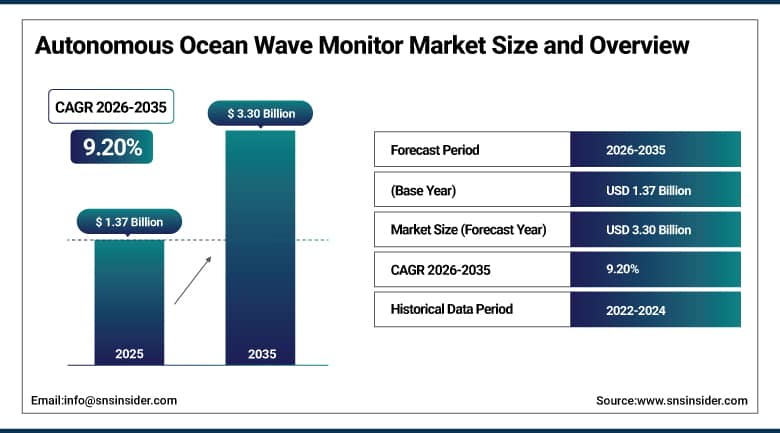
The Autonomous Ocean Wave Monitor Market was valued at USD 1.37 Billion in 2025 and is expected to reach USD 3.30 Billion by 2035, growing at a CAGR of 9.20% from 2026-2035.
Autonomous ocean wave monitors constitute a specialized category within marine and oceanographic instrumentation, integrating surface buoys, subsurface sensors, and satellite communication systems used to measure wave height, period, and direction across deep-sea and coastal environments without requiring continuous human operation. Growing offshore energy project investment, rising maritime safety awareness, and expanding climate and marine research funding continue to broaden the end-user base requiring these systems. Government agencies, research institutes, and an expanding base of offshore energy operators rely on autonomous wave monitors to support navigation safety, inform offshore structure design, and advance long-term oceanographic and climate research. Sustained growth is being shaped by continued advancement in energy-harvesting sensor technology extending unattended operational life, rising integration of satellite communication enabling real-time data transmission from remote ocean locations, and expanding deployment density supporting hurricane prediction and climate monitoring networks, reinforcing this market's position as a durable, technology-led segment of the wider marine technology industry.
In 2025, Sofar Ocean continued expanding its Spotter wave buoy network, integrating solar-powered sensors and satellite connectivity to provide real-time wave, wind, and sea surface temperature data supporting both commercial and research oceanographic applications. The company stated the continued network expansion reflects growing customer demand for scalable, low-maintenance ocean monitoring infrastructure across distributed deployment sites.
To Get More Information On Autonomous Ocean Wave Monitor Market - Request Free Sample Report
Autonomous Ocean Wave Monitor Market Trends
-
Growing use of sophisticated monitoring systems designed for deep-sea and coastal and offshore activities.
-
Rising adoption of energy-harvesting techniques extending sensor operational life in remote, inaccessible locations.
-
Expanding integration of satellite communication enabling real-time data transmission from distributed buoy networks.
-
Increasing deployment of integrated wave monitoring systems combining multiple sensor types within single platforms.
-
Rising investment in climate and marine research programs expanding global ocean observation network density.
-
Growing offshore energy sector demand for wave data supporting structure design and operational safety planning.
U.S. Autonomous Ocean Wave Monitor Market Overview
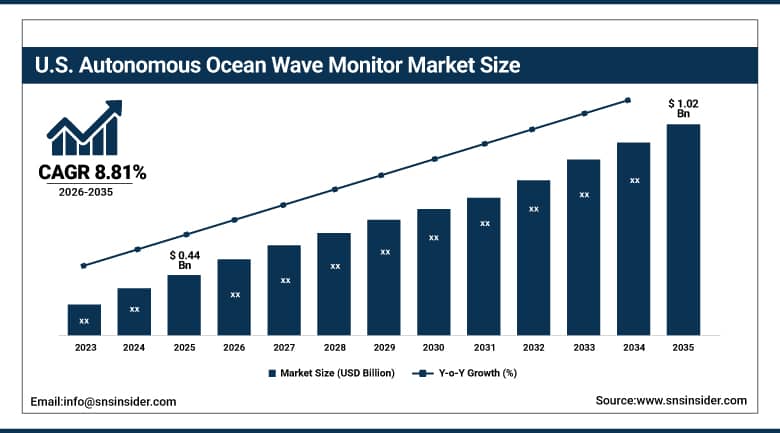
The U.S. Autonomous Ocean Wave Monitor Market was valued at USD 0.44 Billion in 2025 and is expected to reach USD 1.02 Billion by 2035, growing at a CAGR of 8.81% from 2026-2035.
The United States' demand is still driven by continuing government investment in ocean observation infrastructure combined with the increasing activity of the offshore energy industry, which needs dependable wave measurements in its operations across the entire coastal and deep-water observation systems in the country. Major companies keep developing their line of satellite-based buoys, responding to increased demand for real-time access to oceanographic information from the government bodies and scientific organizations, while ongoing investments in energy-generating sensors keep improving the competitive position of players. Increased attention to maritime safety also drives market growth in the U.S. due to increased requirement for wave monitoring equipment by shippers and offshore companies.
In 2023, U.S. Naval Oceanography and Sofar Ocean established a five-year research agreement focused on improving ocean-weather forecasting and data collection, expanding applications for autonomous sensing technologies in maritime operations.
Autonomous Ocean Wave Monitor Market Segment Analysis
-
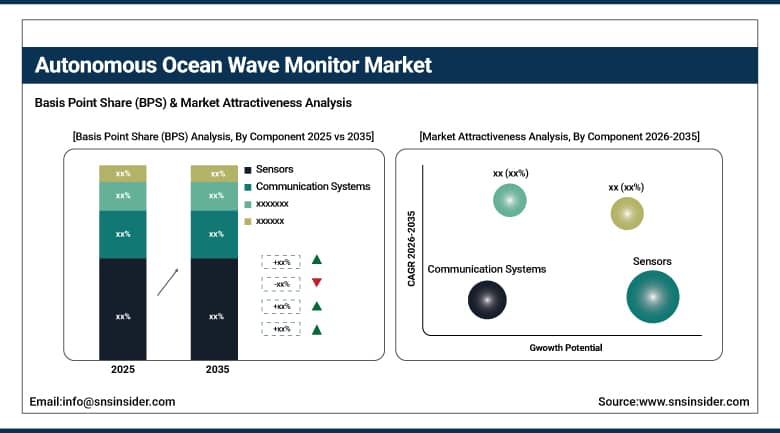
By Component, the Sensors segment dominated the market with a 50.64% share in 2025, while the Communication Systems segment is the fastest growing with a CAGR of 7.80% during 2026-2035.
-
By Product, the Surface Wave Monitors segment dominated the market with a 45.31% share in 2025, while the Integrated Wave Monitoring Systems segment is the fastest growing with a CAGR of 6.50% during 2026-2035.
-
By End User, the Government & Defense segment dominated the market with a 42.60% share in 2025, while the Research Institutes segment is the fastest growing with a CAGR of 8.20% during 2026-2035.
By Component, Sensors Dominates the Autonomous Ocean Wave Monitor Market and Communication Systems Grow Fastest
Sensors constitute the largest component segment owing to the fact that these sensors serve the basic purpose of measurement technology in any self-sustaining wave monitoring system which can provide precise measurements of surface and subsurface waves forming the basic data output of the systems. This role as the basic measurement technology continues to be the key reason behind sensors being the dominant segment of the components used in almost all kinds of wave monitoring platforms irrespective of the design of the systems.
Communication systems have been growing at the fastest pace among the component segments due to increasing need for the transmission of data via satellite on a real time basis from the remote locations where these systems are deployed. The demand for such satellite data transmission as opposed to delayed data acquisition through physical collection of buoys has been increasing faster than other component segments.
By Product, Surface Wave Monitors Dominates the Autonomous Ocean Wave Monitor Market and Integrated Systems Grow Fastest
Surface wave monitors continue to command the largest product share, a position built on their proven deployment simplicity, established measurement accuracy, and decades of accumulated operational track record across both coastal and open-ocean monitoring applications. Operators favour this product category precisely because it delivers dependable, well-understood wave measurement performance without the added deployment complexity that subsurface or fully integrated systems can introduce, sustaining recurring replacement and expansion demand across established ocean observation networks worldwide.
Integrated wave monitoring systems are recording the fastest growth among product categories, reflecting increasing acceptance in research and defense industries alongside offshore energy applications that increasingly require simultaneous, correlated measurement across multiple oceanographic parameters from a single platform. As research institutions and offshore operators increasingly prioritize comprehensive, multi-parameter data collection over single-purpose instruments, integrated systems continue to close the gap with standalone surface monitors in overall market demand.
By End User, Government & Defense Dominates the Autonomous Ocean Wave Monitor Market and Research Institutes Grow Fastest
Government and defense agencies represent the leading end-user category, given their central role funding and operating national ocean observing networks supporting navigation safety, weather forecasting, and national security applications requiring comprehensive, continuously maintained wave monitoring coverage across both territorial waters and broader ocean regions. This foundational funding and operational role continues to sustain government and defense as the dominant end-user category across the broader market.
Research institutes are expanding at the fastest pace among end-user categories, driven by increasing investment in climate and marine research globally as universities and scientific organizations expand ocean observation capability supporting long-term climate change and marine ecosystem studies. As governments and private foundations continue increasing climate research funding worldwide, research institutes continue closing the gap with government and defense in overall market demand.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
78.94% |
|
Asia Pacific |
China |
40.86% |
|
Europe |
Germany |
32.47% |
|
Latin America |
Brazil |
45.73% |
|
Middle East & Africa |
United Arab Emirates |
27.19% |
North America Autonomous Ocean Wave Monitor Market Insights
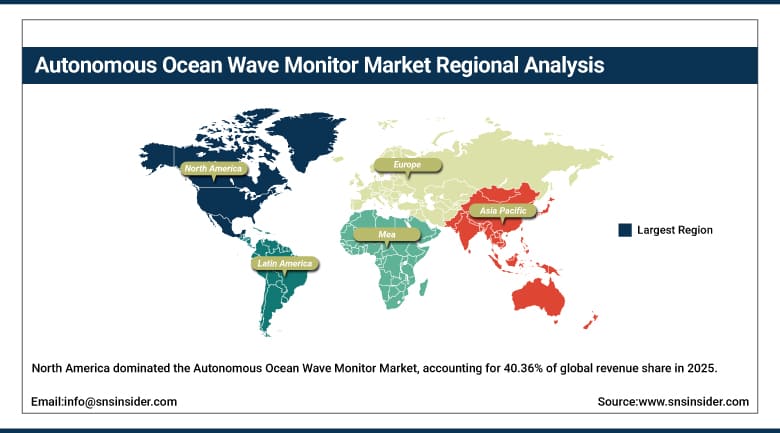
North America dominated the Autonomous Ocean Wave Monitor Market, accounting for 40.36% of global revenue share in 2025, a leadership position supported by sustained federal ocean observing program investment and a dense concentration of leading wave monitoring technology manufacturers headquartered within the region. The United States shapes regional demand through its extensive coastal and open-ocean monitoring network and substantial offshore energy sector activity requiring reliable wave data.
Canada contributes additional regional demand through its participation in North American oceanographic research and coastal monitoring programs. Continued federal investment in climate and ocean observation infrastructure is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets building out offshore energy and research monitoring capacity from a considerably smaller existing base.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Autonomous Ocean Wave Monitor Market Insights
Asia Pacific is expected to witness the fastest growth in the Autonomous Ocean Wave Monitor Market over the forecast period, with a projected CAGR of 9.86% during 2026-2035, due to rising investments in offshore energy projects and environmental monitoring programs across the region. China continues to anchor regional demand as domestic research institutions and offshore energy developers expand wave monitoring deployment across both established coastal zones and rapidly developing offshore wind and energy project sites.
Japan's extensive coastline and well-established marine research infrastructure continue to support substantial regional demand, while India's expanding offshore energy ambitions and growing climate research investment add further regional depth. South Korea and Australia contribute additional demand through active offshore wind development programs, positioning the wider region to sustain the fastest percentage growth of any global market through 2035.
Europe Autonomous Ocean Wave Monitor Market Insights
Europe represents a significant stake in the global market, which is driven by the significant presence of a large number of marine technology manufacturing companies and developments in offshore wind energy that require complete wave resource assessment facilities. The presence of Germany, which possesses significant marine technology and offshore energy infrastructure, is responsible for the driving force behind the regional market demand.
Other nations such as the United Kingdom, Norway, and others in Europe provide demand from the regional maritime markets, since research and offshore energy production companies develop their wave monitoring technologies.
MEA & Latin America Autonomous Ocean Wave Monitor Market Insights
Latin America's market is anchored by Brazil, where a sizeable domestic offshore energy sector and growing marine research investment sustain steady equipment demand across both commercial and scientific applications. Chile and Mexico contribute further incremental growth as coastal monitoring and offshore energy exploration activity continues expanding across the broader region.
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where expanding offshore energy and maritime infrastructure investment is increasingly driving demand for reliable wave monitoring technology. South Africa continues to anchor demand on the African continent, supported by its extensive coastline and growing marine research programs.
Market Dynamics
Growth Drivers: Offshore Energy Expansion and Maritime Safety Awareness
The growing use of sophisticated monitoring systems designed for deep-sea and coastal and offshore activities stands as a primary growth driver, as offshore wind, oil, and gas developers increasingly require comprehensive wave resource data to inform structure design and ongoing operational safety planning. This dynamic is reinforced by rising maritime safety awareness, as shipping operators and coastal authorities increasingly recognize the value of real-time wave data in supporting navigation decisions and reducing weather-related maritime incidents.
The rise in importance of defense applications provides an additional significant source of demand, as national security agencies increasingly incorporate wave monitoring into broader maritime domain awareness programs. Growing investment in climate and marine research globally, paired with expanding offshore renewable energy project development, continues to reinforce sustained market expansion across both established Western markets and rapidly developing regions.
Restraints: High Deployment Costs and Harsh Environment Durability Challenges
Expenses in deployment and maintenance continue to be a true market restraint, as autonomous wave monitoring systems deployed to the remote parts of the ocean continue to have special needs for the deployment of the vessels and maintenance visits, which might significantly increase the overall expenses of such system compared to land-based environmental monitoring system of similar class. Such expense constraints apply especially to smaller research organizations and new companies of the industry that have limited budget for maintaining their fleets.
Durability under harsh conditions is another market restraint, as salt water corrosion, storms and biofouling still continue to limit the longevity of the sensors and communication systems used in open sea conditions. This puts the need on continuous investment in materials and engineering from the side of manufacturers to increase the platform longevity.
Opportunities: Energy-Harvesting Technology and Expanding Ocean Observation Networks
Continued advancement of energy-harvesting techniques offers a substantial opportunity, as manufacturers developing systems capable of extending operational life in remote, inaccessible locations without requiring battery replacement stand to capture meaningful new demand from operators seeking reduced maintenance visit frequency. The continued expansion of global ocean observation networks presents a further avenue for growth, as governments and research institutions worldwide increasingly invest in denser monitoring coverage supporting improved hurricane prediction and climate change research capability.
Recent Developments:
-
2022: Backyard Buoys received a $4.98 million NSF cooperative agreement, supporting Indigenous-led deployment of Sofar Ocean Spotter wave buoys across Alaska, the Pacific Northwest, and Pacific Islands for localized ocean monitoring.
-
2026: Obscape introduced the compact OBS-BUOY 7 WATT, a 15-kilogram autonomous wave-monitoring buoy designed for hand deployment, solar-powered operation, and professional-grade real-time measurements without heavy deployment infrastructure.
Autonomous Ocean Wave Monitor Market Key Players
-
Sofar Ocean Technologies, Inc.
-
Fugro N.V.
-
Sonardyne International Ltd.
-
Valeport Ltd.
-
Blue Ocean Monitoring
-
HydroMet
-
BioSonics, Inc.
-
Teledyne Marine
-
Nortek AS
-
RBR Ltd.
-
AXYS Technologies Inc.
-
Xylem Inc.
-
Kongsberg Gruppen ASA
-
Seabird Scientific
-
Liquid Robotics (Boeing)
-
NKE Instrumentation
-
Datawell BV
-
Campbell Scientific, Inc.
-
OSIL (Ocean Scientific International Ltd.)
-
Mobilis SAS
Autonomous Ocean Wave Monitor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.37 Billion |
| Market Size by 2035 | USD 3.30 Billion |
| CAGR | CAGR of 9.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Surface Wave Monitors, Subsurface Wave Monitors, Integrated Wave Monitoring Systems) • By Component (Sensors, Communication Systems, Power Systems, Data Processing Units, Others) • By End User (Government & Defense, Research Institutes, Offshore Energy Operators, Maritime Shipping, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Sofar Ocean Technologies, Inc., Fugro N.V., Sonardyne International Ltd., Valeport Ltd., Blue Ocean Monitoring, HydroMet, BioSonics, Inc., Teledyne Marine, Nortek AS, RBR Ltd., AXYS Technologies Inc., Xylem Inc., Kongsberg Gruppen ASA, Seabird Scientific, Liquid Robotics (Boeing), NKE Instrumentation, Datawell BV, Campbell Scientific, Inc., OSIL (Ocean Scientific International Ltd.), Mobilis SAS |
Frequently Asked Questions
Key players include Sofar Ocean, Fugro, Sonardyne International, Valeport, Blue Ocean Monitoring, HydroMet, BioSonics, Teledyne Marine, Nortek, and RBR, among others.
Continued advancement of energy-harvesting techniques and the continued expansion of global ocean observation networks represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by the growing use of sophisticated monitoring systems designed for deep-sea and coastal and offshore activities, combined with rising maritime safety awareness.
By Component, Sensors dominated the market with a 50.64% share in 2025, reflecting their essential role providing precise surface and subsurface wave measurements.
North America dominated the market, accounting for 40.36% of global revenue share in 2025, supported by sustained federal ocean observing program investment.
