
Battery Electrolyte Market Report Scope & Overview:
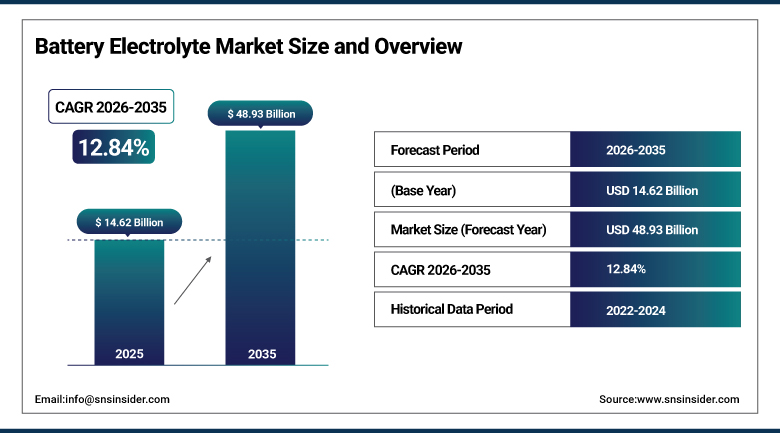
The Battery Electrolyte Market was valued at USD 14.62 Billion in 2025 and is expected to reach USD 48.93 Billion by 2035, growing at a CAGR of 12.84% from 2026-2035.
Battery Electrolyte Market is expanding rapidly owing to rapid expansion in manufacturing of electric vehicles and grid scale energy storage systems along with rising consumer electronics demand. The electrolyte acts as the medium to facilitate transport of ions from cathode to anode which directly affects capacity, charge rate, safety, cycle life and performance under extreme temperatures. Lithium hexafluorophosphate in combination with carbonate-based solvents is the standard electrolyte used in lithium-ion batteries while advances in electrolytes with use of LiFSI as lithium salt and other additives have increased voltage stability and fast charge rate in battery systems. Increasing collaboration between electrolyte manufacturers and battery cell manufacturers for development of electrolytes for new generation of batteries is also witnessed in the market.
To Get more information Battery Electrolyte Market - Request Free Sample Report
⮞Global electrolyte supply chain expansion advanced when Capchem announced, in January 2026, a USD 260 million investment in an electrolyte solvent plant in Yanbu, Saudi Arabia, with planned annual capacity of 200,000 tons of carbonate solvents, alongside a 50,000-ton electrolyte expansion at its Śrem, Poland facility.
Battery Electrolyte Market Trends
-
Rising adoption of LiFSI and dual-salt formulations for fast-charging batteries.
-
Growing electrolyte demand from lithium iron phosphate energy storage batteries.
-
Expanding localization of electrolyte production near North American and European gigafactories.
-
Increasing development of sulfide and oxide solid electrolytes for solid-state batteries.
-
Rising commercialization of sodium-ion battery electrolytes.
-
Growing use of functional additives to improve high-voltage and low-temperature performance.
U.S. Battery Electrolyte Market Outlook
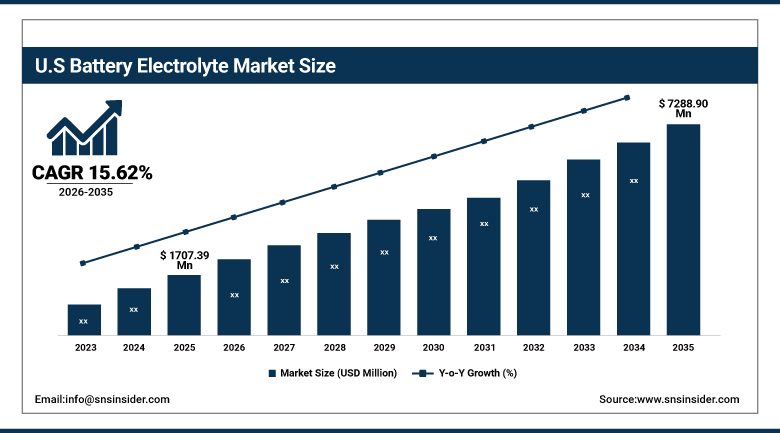
The U.S. Battery Electrolyte Market was valued at USD 1,707.39 Million in 2025 and is expected to reach USD 7,288.90 Million by 2035, growing at a CAGR of 15.62% from 2026-2035.
The U.S. Battery Electrolyte Market continues to grow rapidly on the strength of new battery gigafactories, rapid energy storage deployment, and federal incentives that reward locally produced battery components. Cell plants operated by LG Energy Solution, Samsung SDI, SK On, Panasonic Energy, Toyota, Ford, and Ultium Cells across Michigan, Tennessee, Kentucky, Georgia, Ohio, and Kansas require large and reliable electrolyte supplies. Korean, Japanese, and Chinese electrolyte makers, including Dongwha Electrolyte, Enchem, Soulbrain, Mitsubishi Chemical, and Capchem, have built or announced U.S. plants to serve these customers. The Advanced Manufacturing Production Credit supports electrolyte production, while restrictions on foreign entities of concern are reshaping sourcing decisions. Energy storage battery production for utility and data center projects is increasing demand for lithium iron phosphate electrolytes. Several electrolyte producers have also signed long-term supply agreements with cell makers in the Southeast.
⮞Electrolyte localization in the United States advanced when Dongwha Electrolyte shipped, in July 2026, its first commercial batch from its 86,000-metric-ton-per-year Tennessee plant to a local battery cell factory producing cells for energy storage systems, positioning the company to benefit from the Advanced Manufacturing Production Credit.
Battery Electrolyte Market Segment Analysis
-
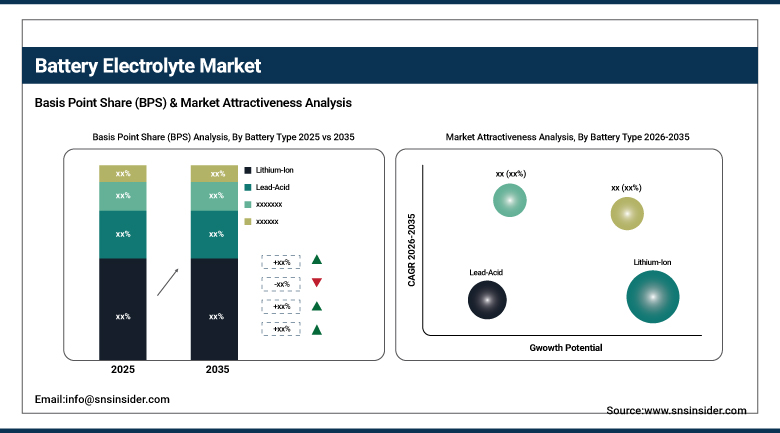
By Battery Type, the Lithium-Ion segment dominated the Battery Electrolyte Market with approximately 81.42% share in 2025, while the Others segment, led by sodium-ion batteries, is the fastest growing with a CAGR of approximately 24.36%.
-
By Electrolyte Type, the Liquid segment dominated the Battery Electrolyte Market with approximately 89.64% share in 2025, while the Solid segment is the fastest growing with a CAGR of approximately 34.82%.
-
By Material, the Lithium Salts segment dominated the Battery Electrolyte Market with approximately 41.36% share in 2025, while the Additives segment is the fastest growing with a CAGR of approximately 14.92%.
-
By End-Use, the Electric Vehicles segment dominated the Battery Electrolyte Market with approximately 58.42% share in 2025, while the Energy Storage Systems segment is the fastest growing with a CAGR of approximately 16.84%.
By Battery Type, Lithium-Ion Dominates the Battery Electrolyte Market and Others Grow Fastest
Lithium-ion batteries held market leadership in 2025 due to the fact that almost all electric cars as well as most grid-scale energy storage systems and consumer electronics devices are driven by them. Usually, electrolytes are developed along with the battery cells for the new battery architecture. Lithium-ion electrolytes are premium formulations, including lithium salts, carbonates, and additives, which are designed specifically for particular battery chemistry. The increase in lithium iron phosphate and nickel-based battery cell production is growing electrolyte volume in China, South Korea, Japan, Europe, and North America. Further gigafactory investments, declining battery costs, and widening uses will ensure the lithium ion battery market leader position in the battery electrolyte market.
Others are comprised primarily of sodium-ion batteries, which form the fastest-growing battery type with their increasing production in entry-level vehicles, two-wheelers, and stationary storage. The electrolytes of sodium-ion batteries can make use of cheaper aluminum current collectors on both electrodes. In contrast to lithium-ion batteries, sodium-ion batteries use sodium hexafluorophosphate and other sodium salts in carbonate electrolytes, thus not being reliant on lithium. Chinese producers such as CATL and BYD are scaling up their sodium-ion batteries, thus generating additional demand for electrolytes. Sodium-ion batteries have very good characteristics at low temperatures and high safety, thus facilitating their usage in cold climates and stationary applications.
⮞In April 2026, CATL unveiled its Naxtra sodium-ion battery at its Super Technology Day in Beijing, confirming GWh-scale industrialization and plans for full-scale mass production by year-end, supporting commercialization of alternative battery chemistries.
By Electrolyte Type, Liquid Dominates the Battery Electrolyte Market and Solid Grows Fastest
Liquid electrolytes dominated the market in 2025 since they serve as the industry standard for lithium-ion batteries and offer high ionic conductivity, efficient wettability with electrodes, and compatibility with current manufacturing processes. The majority of the gigafactories being constructed worldwide are still focused on producing cells with liquid electrolytes. Liquid electrolytes are commercially available from such companies as Tinci, Capchem, Soulbrain, Enchem, and Mitsubishi Chemical among others and can be purchased at affordable prices. Enhanced salt, solvent, and additive technology has increased the capacity and fast charging efficiency of the products. The widespread use of liquid electrolyte cells in electric vehicles and energy storage makes the liquid electrolytes the most prevalent electrolyte segment in the market.
⮞In December 2025, Orbia Fluor & Energy Materials completed the expansion of its custom electrolyte manufacturing facility in Madison, Wisconsin, increasing production capacity by approximately 300% to support lithium-ion and emerging battery chemistries.
Solid electrolytes are the fastest-growing type as automakers and battery makers advance solid-state batteries that promise higher energy density, faster charging, and improved safety. Solid electrolytes can also enable lithium-metal anodes. Sulfide, oxide, and polymer solid electrolytes are moving from laboratory research to pilot production at companies such as Toyota, Idemitsu Kosan, Samsung SDI, QuantumScape, Solid Power, and Chinese battery makers. Lithium sulfide and argyrodite-type sulfide electrolyte plants are being built to supply early vehicle programs. Although commercial volumes remain small, rising investment in materials, manufacturing equipment, and vehicle validation continues to drive the fastest growth among electrolyte type segments in the market.
By Material, Lithium Salts Dominate the Battery Electrolyte Market and Additives Grow Fastest
Lithium salts dominated the market in 2025 due to the fact that lithium hexafluorophosphate is the highest valued component of traditional lithium-ion electrolytes, representing a considerable portion of the cost of electrolyte materials. LiFSI is being used more and more together with LiPF6 in high-performance batteries. LiPF6 has decent conductivity and forms an effective passivation film on aluminum electrodes, which makes it the industry benchmark salt. Major companies, such as Tinci, Do-Fluoride, and Stella Chemifa, have large-scale production facilities for LiPF6 salts, while new lithium salts, such as LiFSI, are being widely adopted. The crucial function of lithium salts in all lithium-ion electrolytes guarantees their dominance in battery electrolyte materials market.
Additives are currently the fastest-growing material category, as battery producers depend on special formulations to achieve better cycle life, high voltage stability, fast charging, and safety. The use of additives per cell has been increasing as the demands on battery technology have increased. These include additives like vinylene carbonate, fluoroethylene carbonate, and lithium difluorophosphate that provide protective interphase layers and prevent degradation. Nickel-based cathodes, silicon-based anodes, and high voltage batteries need better formulations of additives. Differentiating the electrolytes by the use of special additives has become a strategy used by electrolyte producers in collaboration with the cell producers. The demand for additives is therefore growing very rapidly.
⮞In June 2026, Zhejiang Yongtai Technology disclosed an agreement to supply CATL with 20,000 tonnes of vinylene carbonate electrolyte additive in 2027, increasing to 40,000 tonnes in 2029, supporting lithium-ion battery performance requirements.
By End-Use, Electric Vehicles Dominate the Battery Electrolyte Market and Energy Storage Systems Grow Fastest
The electric vehicles were the dominating product category in 2025 since they dominate the lithium-ion battery cell manufacturing on volume basis. The commercial vehicles also need large batteries. Every electric vehicle needs a large battery cell with tens of kilos of electrolyte. The automotive category is thus the largest one in terms of demand for battery electrolytes. In 2025, there were more than 20 million electric cars sold across the world, with China, Europe, and US being the front runners. There are also electric buses, trucks, and two wheelers which are increasing the volume numbers.
Energy storage systems are the fastest-growing end use as utilities, independent power producers, data centers, and commercial users deploy large volumes of lithium iron phosphate batteries for renewable integration, grid stability, and backup power. Storage projects increasingly require multi-hour discharge durations. Energy storage cells are designed for long cycle life, requiring stable electrolyte formulations that minimize degradation over thousands of cycles. Battery makers are converting production lines to energy storage cells, increasing electrolyte demand. Rapid growth in solar and wind capacity, together with rising electricity demand from AI data centers, continues to drive the fastest growth in the energy storage segment over the forecast period.
⮞In June 2026, CATL introduced its TENER Sodium Energy Storage System in Munich, announcing RMB 5 billion invested in expanding sodium-ion production at its Fuding facility, adding 40 GWh of annual capacity for commercial energy storage applications.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
84.26% |
|
Asia Pacific |
China |
78.64% |
|
Europe |
Germany |
28.42% |
|
Latin America |
Brazil |
38.64% |
|
Middle East & Africa |
Saudi Arabia |
34.28% |
North America Battery Electrolyte Market Insights
North America accounted for approximately 13.86% of the global Battery Electrolyte Market in 2025 and is the fastest-growing regional market, expanding at a CAGR of approximately 15.38% from 2026 to 2035. Several of these plants have begun commercial shipments, creating a more resilient regional supply base for cell makers. Growth is supported by new battery gigafactories, federal production incentives, and requirements for locally sourced battery components. Electrolyte makers including Dongwha Electrolyte, Enchem, Soulbrain, Mitsubishi Chemical, and Capchem have built or announced plants in Tennessee, Georgia, Indiana, Ohio, and other states, positioning supply close to cell manufacturers serving electric vehicle and storage markets across the region.
The United States anchors regional demand through cell plants operated by LG Energy Solution, Samsung SDI, SK On, Panasonic Energy, Toyota, Ford, and Ultium Cells, along with new energy storage cell lines. Local supply also reduces hazardous material shipping requirements. Canada is building a battery supply chain in Ontario and Quebec, attracting cathode, cell, and electrolyte investments supported by critical mineral resources. Mexico is attracting battery component investments that serve North American vehicle assembly. Although changes to electric vehicle incentives have slowed some projects, growing energy storage production and supply chain localization are expected to keep North America the fastest-growing regional market.
Get Customized Report as per Your Business Requirement - Enquiry Now
⮞In September 2026, Capchem USA announced the groundbreaking of its lithium-ion battery electrolyte manufacturing facility in Ironton, Ohio, establishing its first large-scale North American battery chemicals production base to serve electric vehicle and energy storage customers.
Europe Battery Electrolyte Market Insights
Europe holds a significant share of the Battery Electrolyte Market, supported by gigafactories operated by LG Energy Solution, Samsung SDI, SK On, CATL, ACC, and PowerCo across Poland, Hungary, Germany, France, and Spain. European cell makers increasingly prefer suppliers with local production, strong quality systems, and the ability to support new cell chemistries, encouraging further electrolyte investment across Central and Eastern Europe. Germany is the leading country market, driven by strong automotive demand and battery plants that serve Volkswagen, BMW, and Mercedes-Benz. Producers of electrolytes like Capchem, Enchem, Soulbrain, Dongwha Electrolyte, and BASF are either operating or setting up plants in Poland, Hungary, and other countries to service the cell manufacturers and reduce transportation costs.
⮞In July 2026, Germany’s E-Lyte Innovations and PCC Thorion signed a joint development agreement to advance and commercialize the Scionb electrolyte additive platform for lithium-ion and sodium-ion batteries, strengthening European electrolyte materials innovation.
There are several provisions under the EU Battery Regulation related to carbon footprint, recycled content, and due diligence which will have an impact on electrolyte supply and production. There are also moves being made by European chemical companies to partner with Asian electrolyte suppliers for building local capacities. Restrictions under European chemical regulations for fluorinated chemicals could potentially drive future electrolyte formulation and motivate research into salt and solvent alternatives. European research programs are focusing on solid-state and sodium-ion batteries, thus creating opportunities for electrolyte chemistries. Despite the delay in some gigafactory projects, investments in battery production and localization are expected to maintain Europe's position as a regional market for battery electrolytes.
Asia Pacific Battery Electrolyte Market Insights
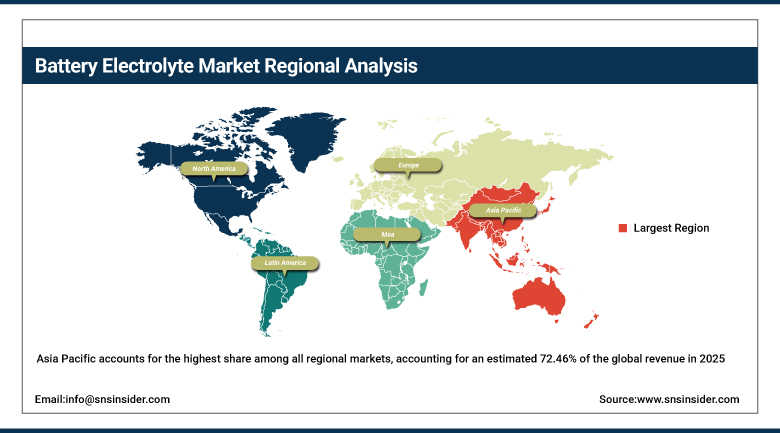
The Asia Pacific accounts for the highest share among all regional markets, accounting for an estimated 72.46% of the global revenue in 2025, while growing at a CAGR of approximately 12.42% during 2026 to 2035. China is the leading manufacturer of essential electrolyte raw materials such as lithium carbonate, fluorine chemicals, and solvent precursors, thus providing a substantial cost advantage to its producers over their counterparts. The dominance of this region can be attributed to the domination of the lithium-ion batteries and electrolyte producers in China, with some of the key companies being Tinci, Capchem, Guotai Huarong, Shanshan, and Zhejiang Yongtai.
⮞In August 2026, Asahi Kasei signed a non-exclusive licensing agreement with HighChem Shanghai to manufacture and sell its acetonitrile-containing Acetolyte electrolyte in China, expanding local access to formulations designed for improved battery temperature performance.
South Korea and Japan contribute advanced electrolyte technology through Soulbrain, Enchem, Dongwha Electrolyte, Panax Etec, Mitsubishi Chemical, Central Glass, and UBE Corporation, which supply leading cell manufacturers with high-performance formulations. Regional producers are also expanding overseas plants to follow their customers into new markets. Japan is also a leader in solid-state electrolyte development through Toyota and Idemitsu Kosan. India is building battery and electrolyte capacity under its production-linked incentive scheme, while Indonesia, Thailand, and Malaysia are attracting battery supply chain investments. Rapid battery production growth across the region is expected to keep Asia Pacific the largest regional market over the forecast period.
MEA & Latin America Battery Electrolyte Market Insights
The Middle East & Africa region can be classified as an emerging market driven by Saudi Arabia, United Arab Emirates, and Morocco. The government is offering incentives to draw battery material investments into the area, which is coupled with new industrial regions near ports, providing easy access to export destinations. In the case of Saudi Arabia, there are several battery material investment opportunities associated with the country’s efforts toward economic diversification, for example, Capchem’s electrolyte solvent plant in Yanbu. At present, Morocco is becoming a battery materials center for the European market, drawing in investments in cathodes, anodes, and electrolytes from China and Korea.
⮞In October 2026, NESR signed an agreement with Saudi Aramco to develop a direct lithium extraction demonstration project using its LiThara platform, targeting annual production of 2,000 tonnes of battery-grade lithium carbonate from late 2027.
Latin America continues to develop on the back of developments in Brazil, Mexico, Chile, and Argentina. Battery recycling developments in Latin America are emerging too. Brazil and Mexico are making strides in EV and battery manufacturing, exemplified by the presence of BYD battery manufacturing in Brazil, thereby creating an early demand for batteries and battery parts. Chile and Argentina have significant lithium deposits and are looking at ways to exploit them in lithium chemicals and battery materials. Solar and wind energy storage installations in Chile and Mexico are increasing the demand for batteries. While there are not many electrolyte manufacturers in the region, there should be some steady growth in batteries and battery components.
⮞In February 2026, Brazil’s development bank BNDES approved R$280 million in financing for WEG to construct a battery energy storage system manufacturing facility in Itajaí, Santa Catarina, supporting domestic storage equipment production and renewable energy integration.
Market Dynamics
Growth Drivers: Rapid Growth in Electric Vehicle and Energy Storage Battery Production and Battery Supply Chain Localization
The rapid increase in manufacturing capacity of electric vehicles and energy storage batteries serves as the major factor influencing the expansion of Battery Electrolyte Market due to the requirement of electrolytes in each lithium-ion cell manufactured. The development in battery chemistry leads to an increase in the need for electrolytes having a specific formulation. There is a continual rise in battery manufacturing capacity across the globe owing to the development of new gigafactories in North America, Europe, and Asia besides the existing ones in China. Energy storage battery production is rising fast due to renewable energy generation and AI data centers.
⮞In August 2026, LG Energy Solution commenced battery cell production at its Lansing, Michigan, facility, targeting more than 35 GWh of annual capacity at full scale to serve electric vehicle and energy storage markets.
Localizing battery supply chains continues to drive market growth because of government incentives in countries like the United States, Europe, India, and many others in different regions that promote the manufacturing of battery components domestically. There are also long-term supply contracts being made between electrolytes manufacturers and cell manufacturers in different regions. Governments through incentives like the U.S. Advanced Manufacturing Production Credit, the EU battery industrial policy, and India production-linked incentives program provide support for electrolyte plants to be located close to cell plants. Cell manufacturers favor electrolytes from nearby locations to reduce logistics expenses, handle the challenge of transporting hazardous materials, and comply with local content needs.
Restraints: Raw Material Price Volatility and Safety and Environmental Concerns
Price fluctuations in raw materials continue to be a major constraint for the Battery Electrolyte Market, given that the prices of electrolytes are highly contingent on lithium carbonate, lithium hexafluorophosphate, and fluorine chemicals. The low prices have resulted in consolidation of small electrolyte manufacturers in China. There have been significant price fluctuations in lithium due to which there have been fluctuations in the prices of electrolytes as well. There is excess supply of LiPF6 as well as electrolytes in China, which has made the prices highly competitive and unprofitable for electrolyte producers.
Further limitations of market growth are safety and environmental issues since the use of liquid electrolytes is flammable and may result in a thermal runaway of the batteries if there are any problems with them. Moreover, there are flame retardant additives and non-flammable solvents that enhance battery safety. The issue of battery fires in electric cars and power storage systems raised concerns about the safety of electrolytes. The production of LiPF6 and other fluorinated additives uses hazardous chemicals like hydrogen fluoride. The future regulation of per- and polyfluoroalkyl substances in Europe and the USA will create additional challenges for some electrolytes' components.
Opportunities: Solid-State Battery Electrolytes and Advanced Salts and Fast-Charging Formulations
Solid-state battery electrolytes offer substantial potential for the Battery Electrolyte Market as automobile manufacturers and battery manufacturers develop solid-state batteries in the coming years. There will be an increase in solid electrolyte contracts as more vehicle platforms become ready for launch. Solid electrolytes include sulfide, oxide, and polymer types which need new chemistry and manufacturing methods as well as supply chain solutions, hence providing opportunities for chemical firms and specialty materials providers. There are also joint ventures between companies such as Toyota and Idemitsu Kosan and Samsung SDI and EcoPro BM among others which have been developing capacity for solid electrolytes.
⮞In August 2026, Anthro Energy broke ground on a commercial-scale advanced polymer electrolyte manufacturing facility in Louisville, Kentucky, representing an investment exceeding $40 million to expand domestic electrolyte production for next-generation battery applications.
Salts that have been advanced and fast charging formulations provide another avenue that should be explored since customers need to get cars that take only minutes to charge rather than hours. Fast charging is becoming a crucial consideration when buying an electric vehicle. New lithium salts like LiFSI have higher conductivity, increased thermal stability and enhanced performance under high voltage and low temperatures. Electrolyte manufacturers have started to come up with high concentration localized electrolytes, solvent combinations and additives that facilitate very fast charging and prolonged life cycles. Companies that collaborate closely with the manufacturers of cells with new technologies can get premium prices and long-term agreements from top battery makers.
Recent Developments:
-
July 2026: Tinci Materials reported that its electrolyte and LiPF6 facilities were operating near full capacity on rising energy storage battery demand, with its planned 35,000-tpy LiPF6 capacity expansion on track for commissioning in the second half of 2026.
-
January 2026: Toyota Motor Corporation and Idemitsu Kosan advanced their solid-state battery partnership with groundbreaking for a lithium sulfide production facility, a key raw material for sulfide solid electrolytes planned for use in Toyota's first solid-state battery electric vehicles.
Battery Electrolyte Market Key Players
-
Guangzhou Tinci Materials Technology Co., Ltd.
-
Shenzhen Capchem Technology Co., Ltd.
-
Soulbrain Co., Ltd.
-
Mitsubishi Chemical Group Corporation
-
Central Glass Co., Ltd.
-
ENCHEM Co., Ltd.
-
UBE Corporation
-
BASF SE
-
LG Chem Ltd.
-
Zhangjiagang Guotai Huarong New Chemical Materials Co., Ltd.
-
Dongwha Electrolyte Co., Ltd.
-
Ningbo Shanshan Co., Ltd.
-
Morita Chemical Industries Co., Ltd.
-
Zhejiang Yongtai Technology Co., Ltd.
-
Panax Etec Co., Ltd.
-
Jiangsu Chunbo Technology Co., Ltd.
-
Stella Chemifa Corporation
-
Do-Fluoride New Materials Co., Ltd.
-
Idemitsu Kosan Co., Ltd.
-
Solid Power, Inc.
Battery Electrolyte Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 14.62 Billion |
| Market Size by 2035 | USD 48.93 Billion |
| CAGR | 12.84% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Battery Type: Dominant – Lithium-Ion (81.42% share in 2025); Fastest-Growing – Others, led by sodium-ion batteries (CAGR 24.36%) • By Electrolyte Type: Dominant – Liquid (89.64% share in 2025); Fastest-Growing – Solid (CAGR 34.82%) • By Material: Dominant – Lithium Salts (41.36% share in 2025); Fastest-Growing – Additives (CAGR 14.92%) • By End-Use: Dominant – Electric Vehicles (58.42% share in 2025); Fastest-Growing – Energy Storage Systems (CAGR 16.84%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Guangzhou Tinci Materials Technology Co., Ltd., Shenzhen Capchem Technology Co., Ltd., Soulbrain Co., Ltd., Mitsubishi Chemical Group Corporation, Central Glass Co., Ltd., ENCHEM Co., Ltd., UBE Corporation, BASF SE, LG Chem Ltd., Zhangjiagang Guotai Huarong New Chemical Materials Co., Ltd., Dongwha Electrolyte Co., Ltd., Ningbo Shanshan Co., Ltd., Morita Chemical Industries Co., Ltd., Zhejiang Yongtai Technology Co., Ltd., Panax Etec Co., Ltd., Jiangsu Chunbo Technology Co., Ltd., Stella Chemifa Corporation, Do-Fluoride New Materials Co., Ltd., Idemitsu Kosan Co., Ltd., Solid Power, Inc. |

Frequently Asked Questions
Key players include Guangzhou Tinci Materials Technology Co., Ltd., Shenzhen Capchem Technology Co., Ltd., Soulbrain Co., Ltd., Mitsubishi Chemical Group Corporation, Central Glass Co., Ltd., ENCHEM Co., Ltd., and UBE Corporation, among other global electrolyte manufacturers.
Solid-state battery electrolytes, along with advanced salts and fast-charging formulations, represent the primary opportunities.
Growth is primarily driven by rapid growth in electric vehicle and energy storage battery production combined with battery supply chain localization.
By Electrolyte Type, Liquid dominated the market with approximately 89.64% share in 2025, reflecting its role as the industry standard for lithium-ion battery production.
