
Beverage Carton Packaging Machinery Market Report Scope & Overview:
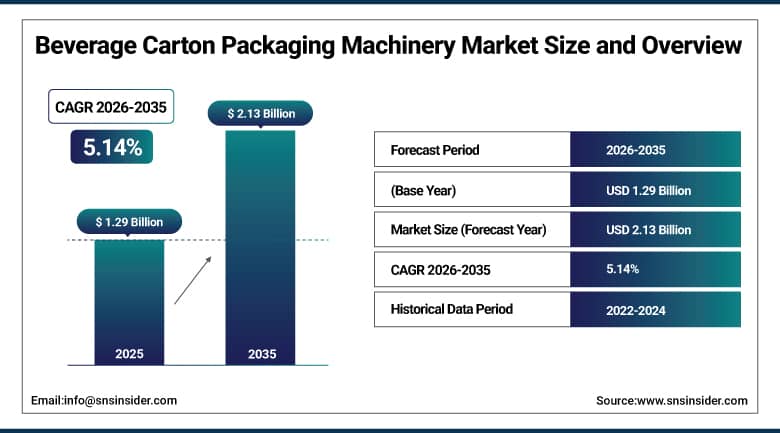
The Beverage Carton Packaging Machinery Market was valued at USD 1.29 Billion in 2025 and is expected to reach USD 2.13 Billion by 2035, growing at a CAGR of 5.14% from 2026-2035.
Beverage carton packaging machinery plays an essential role in modern beverage production by automating carton forming, filling, sealing, labeling, and palletizing operations. These systems enable manufacturers to process large beverage volumes efficiently while maintaining product quality, hygiene, and packaging consistency. Market demand is supported by increasing consumption of alcoholic beverages, health drinks, electrolyte beverages, dairy products, and other packaged beverages. The growing adoption of sustainable packaging materials is also encouraging manufacturers to shift from conventional plastic containers toward carton-based packaging formats. Dairy processing represents a significant application area due to the substantial volume of milk and related products requiring efficient packaging infrastructure. According to FAO data, global milk production has exceeded 944 million tonnes, reinforcing the need for high-capacity aseptic filling and packaging systems capable of supporting continuous, large-scale dairy operations.
SIG is investing €60 million into the construction of its first aseptic carton plant in India, a facility expected to reach a production capacity of 4 billion packs per annum once fully operational. It's a substantial bet on a single market, and it reflects how carton packaging machinery suppliers are increasingly chasing growth wherever beverage consumption is expanding fastest rather than concentrating investment in already-mature Western markets. Building that kind of capacity from scratch in a new region also signals confidence that demand for aseptic, shelf-stable carton packaging will keep climbing well beyond current production levels.
To Get More Information On Beverage Carton Packaging Machinery Market - Request Free Sample Report
Beverage Carton Packaging Machinery Market Trends
-
Rising adoption of digital twin technology enabling real-time optimization of carton packaging production lines.
-
Growing shift toward renewable and biodegradable carton materials requiring specialized, purpose-built packaging machinery.
-
Expanding integration of AI-driven quality control systems reducing defect rates across high-speed filling operations.
-
Increasing demand for aseptic filling capacity supporting the global dairy industry's shelf-stable packaging requirements.
-
Rising machinery investment supporting the rapid growth of plant-based and alternative beverage categories.
-
Growing manufacturer focus on PFAS-free and aluminium-free packaging structures reshaping machinery compatibility requirements.
U.S. Beverage Carton Packaging Machinery Market Outlook
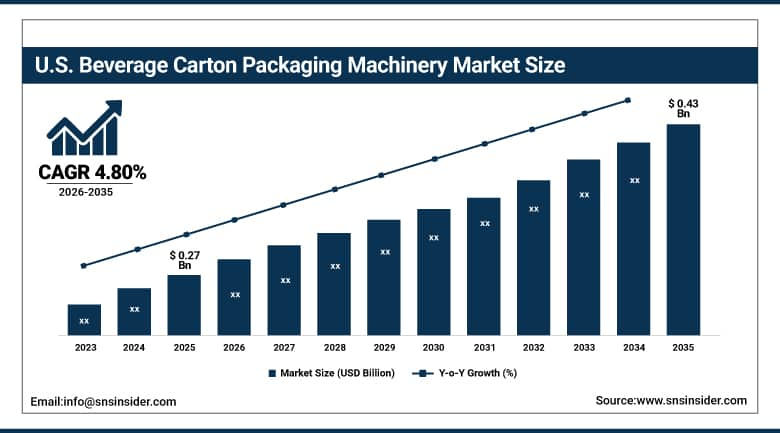
The U.S. Beverage Carton Packaging Machinery Market was valued at USD 0.27 Billion in 2025 and is expected to reach USD 0.43 Billion by 2035, growing at a CAGR of 4.80% from 2026-2035.
American dairy and beverage producers have leaned hard into carton packaging in recent years, partly on cost grounds and partly because cartons carry a genuine sustainability advantage over plastic bottles that resonates with increasingly eco-conscious retailers and consumers. That shift has kept domestic demand for high-speed filling and sealing machinery steady even as overall population growth in the region moderates, since existing dairy and beverage producers keep upgrading equipment to handle new product formats and tighter hygiene requirements. The Coca-Cola Company's 2024 rollout of 100% recycled PET bottles across more than 40 markets is a reminder of just how central sustainable packaging commitments have become across the broader beverage industry, and carton packaging, with its inherently renewable fiber-based structure, continues to benefit from that same sustainability push.
Elopak opened a new production facility in Little Rock, Arkansas, a move the company has described as key to expanding its North American market share, and the investment appears to be paying off quickly, with the company's Americas segment posting organic revenue growth of 23.1% in the first quarter of 2025 alone. That kind of growth rate for a single regional segment is striking, and it suggests domestic beverage producers are actively shifting business toward suppliers who can offer local production capacity and faster turnaround rather than relying solely on European manufacturing and long-distance shipping.
Beverage Carton Packaging Machinery Market Segment Analysis
-
By Machine Type, the Filling & Sealing Machines segment dominated the Beverage Carton Packaging Machinery Market with approximately 44.60% share in 2025, while the Labeling Machines segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Carton Type, the Aseptic Cartons segment dominated the Beverage Carton Packaging Machinery Market with approximately 54.60% share in 2025, while the Others (renewable/biodegradable) segment is the fastest growing with a CAGR of approximately 6.60%.
-
By End-Use Application, the Dairy segment dominated the Beverage Carton Packaging Machinery Market with approximately 38.60% share in 2025, while the Plant-Based Beverages segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Level of Automation, the Fully Automated segment dominated the Beverage Carton Packaging Machinery Market with approximately 68.60% share in 2025, and is also the fastest growing with a CAGR of approximately 6.40%.
By Machine Type, Filling & Sealing Machines Dominates the Beverage Carton Packaging Machinery Market and Labeling Machines Grows Fastest
Filling and sealing machines represent the largest and most essential category in this market, and for good reason, this is the equipment actually responsible for getting product into the carton and ensuring it stays fresh and contamination-free until it reaches a consumer. Given the hygiene and shelf-stability requirements that dairy and juice producers operate under, these machines command a premium relative to other equipment types and represent the single largest capital investment most beverage packaging lines make.
Labeling machines are growing fastest, which reflects a broader industry push toward smarter packaging and better traceability rather than pure filling capacity. As brand owners increasingly want packaging that can carry QR codes, batch tracking information, and consumer-facing sustainability messaging, labeling equipment capable of handling this added complexity at production-line speed is becoming a more significant investment priority than it was in years past.
By Carton Type, Aseptic Cartons Dominates the Beverage Carton Packaging Machinery Market and Others Grows Fastest
Aseptic cartons dominate this market because they solve a genuinely valuable problem for beverage producers: extending shelf life without refrigeration, sometimes for up to twelve months, by sterilizing both the product and packaging before sealing. That capability is enormously valuable for dairy and juice distribution, particularly in markets without robust cold-chain infrastructure, and it's why machinery supporting aseptic filling remains the backbone of this industry.
Renewable and biodegradable carton materials are experiencing rapid growth as beverage manufacturers respond to stricter environmental regulations and increasing consumer demand for sustainable packaging. Processing these materials requires specialized machinery capable of maintaining packaging integrity, production efficiency, and product protection despite variations in material properties. Consequently, equipment manufacturers are investing in advanced forming, filling, and sealing technologies. Suppliers offering machinery compatible with renewable materials are benefiting from growing demand as sustainability targets increasingly influence packaging investments across the global beverage industry.
By End-Use Application, Dairy Dominates the Beverage Carton Packaging Machinery Market and Plant-Based Beverages Grows Fastest
Dairy remains the anchor application for this entire market, simply because of the sheer scale of global milk production and the packaging infrastructure required to move it from farm to shelf. With FAO data showing global milk production exceeding 944 million tons and continued growth concentrated in Asia and Africa, dairy processors represent a customer base that keeps expanding its machinery needs almost independent of broader economic cycles.
Plant-based beverages are where the growth energy is concentrated as oat, soy, almond, and other alternative milk categories continue winning shelf space once reserved almost entirely for dairy. These products often require carton packaging equipment configured somewhat differently than traditional dairy lines, given differences in viscosity and shelf-life requirements, and machinery suppliers who can serve this rapidly scaling category well are positioned to capture a disproportionate share of new equipment orders.
By Level of Automation, Fully Automated Dominates the Beverage Carton Packaging Machinery Market and Also Grows Fastest
Fully automated machinery holds a commanding share of this market, and that dominance keeps strengthening as beverage producers, facing rising labor costs and unforgiving hygiene standards, increasingly view full automation as the only realistic path to high-volume production. These systems deliver the consistency, speed, and reduced human contact with product that modern food safety expectations essentially demand.
Fully automated machinery also shows fastest growth in this market, as semi-automated lines get progressively retired in favor of fully automated equivalents capable of handling everything from filling through palletizing with minimal manual intervention. As labor availability tightens in many manufacturing regions and quality expectations keep rising, full automation looks set to keep extending its lead over partially manual alternatives.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.60% |
|
Europe |
Germany |
29.60% |
|
North America |
United States |
84.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Beverage Carton Packaging Machinery Market Insights
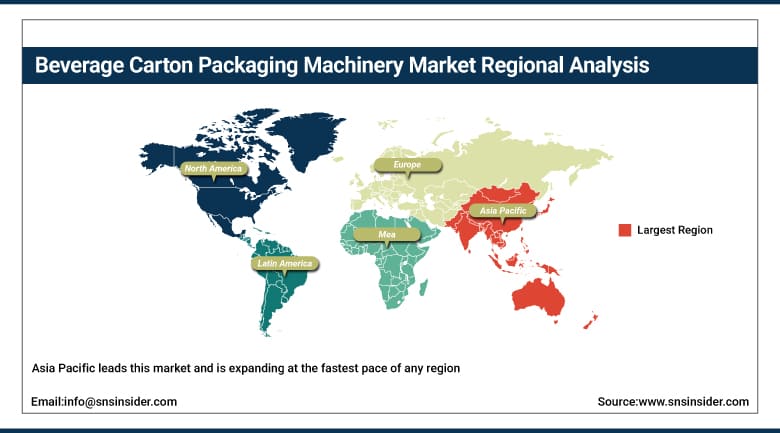
Asia Pacific leads this market and is expanding at the fastest pace of any region, a combination driven by changing lifestyles, rising beverage consumption, and dairy production that continues growing rapidly across China and India in particular. As disposable incomes rise across the region, consumers are shifting toward packaged, branded beverages rather than loose or informally sold products, and that shift is pulling enormous volumes of new machinery investment into the region.
China's massive domestic beverage manufacturing base continues to anchor regional demand, while India's rapidly modernizing dairy and juice industries are becoming an increasingly important growth driver in their own right. SIG's decision to build its first Indian aseptic carton plant with capacity for 4 billion packs annually is a direct reflection of just how much confidence global suppliers now place in the region's long-term growth trajectory, and that kind of investment should keep Asia Pacific firmly in the lead through 2035.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Beverage Carton Packaging Machinery Market Insights
Europe represents a substantial and mature share of this market, home to several of the industry's most established machinery suppliers and a long-standing consumer preference for carton-packaged dairy and juice products. The region's stringent sustainability regulations continue pushing machinery innovation toward materials with lower environmental footprints, keeping European suppliers at the technical forefront of the industry even as growth here moderates relative to faster-expanding emerging markets.
Germany's manufacturing base anchors regional demand, while the broader European market continues to benefit from deeply established carton recycling infrastructure that reinforces consumer and regulatory confidence in the packaging format itself. That infrastructure advantage helps sustain steady machinery replacement and upgrade demand even in a mature, slower-growing regional market.
North America Beverage Carton Packaging Machinery Market Insights
North America represents a significant share of the global market, anchored by the United States' substantial dairy and beverage manufacturing base and a growing consumer and retailer preference for sustainable, carton-based packaging over plastic alternatives. Domestic producers continue investing in equipment upgrades to handle both traditional dairy products and the rapidly expanding plant-based beverage category.
Canada is contributing incremental regional demand as its own beverage manufacturing sector continues to modernize. Continued domestic manufacturing capacity investment, exemplified by new production facilities aimed specifically at serving the North American market, is expected to sustain steady regional growth through the forecast period.
MEA & Latin America Beverage Carton Packaging Machinery Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing beverage consumption across the United Arab Emirates and Saudi Arabia sustains demand for modern packaging machinery. Regional dairy and juice production capacity continues to develop gradually, supported by government investment in food processing infrastructure.
Latin America's market is led by Brazil, where a substantial domestic dairy and beverage industry sustains steady demand for carton packaging machinery. Mexico is contributing growth as regional beverage manufacturing continues to expand alongside broader nearshoring-driven industrial investment across the region.
Market Dynamics
Growth Drivers: Sustainable Packaging Demand and Rising Beverage Consumption
Rising focus on sustainable packaging represents one of the strongest forces behind this market's growth, as beverage producers and regulators alike increasingly favor fiber-based carton packaging over plastic alternatives. That preference translates directly into machinery demand, since every producer making the switch to carton packaging needs the equipment to actually run that packaging format at production scale.
Growing consumption of alcohol, health drinks, and electrolyte beverages adds further momentum, as an expanding range of beverage categories increasingly adopt carton formats previously reserved mainly for dairy and juice. This diversification of carton-packaged products continues to broaden the addressable market for packaging machinery well beyond its traditional dairy-centric base.
Restraints: High Capital Investment and Complex Machinery Integration
High capital investment requirements represent a meaningful restraint, as fully automated carton packaging lines command substantial upfront cost that can be genuinely difficult for smaller beverage producers to justify, particularly in price-sensitive emerging markets where production volumes may not yet support the investment.
Machinery integration complexity adds a further challenge, since modern packaging lines increasingly need to work seamlessly with digital quality control systems, traceability software, and evolving sustainable packaging materials, all of which require careful engineering coordination that can extend installation timelines and increase total project cost beyond the machinery price tag alone.
Opportunities: Plant-Based Beverage Growth and Digital Twin Technology
The rapid expansion of plant-based beverages represents a substantial opportunity, as this fast-growing category continues requiring dedicated packaging machinery investment from both established dairy processors adding new product lines and dedicated plant-based beverage companies scaling production. Suppliers who can serve this category's somewhat distinct processing requirements well are positioned to capture meaningful new business.
Adoption of digital twin technology offers a further avenue for growth, as manufacturers increasingly use real-time virtual modeling to optimize packaging line performance before making physical changes to equipment. Suppliers who can build this kind of digital optimization capability into their machinery offerings are well positioned to differentiate themselves as beverage producers look for every possible efficiency gain in an increasingly competitive packaging landscape.
Recent Developments:
-
In 2025, Koenig & Bauer acquired a niche startup specializing in AI-driven quality control systems for packaging machinery, aiming to enhance product consistency and reduce defect rates.
-
SIG announced its intent to develop a full-barrier, aluminium-free aseptic packaging structure with at least 90% fiber content by 2030, targeting an interim milestone of at least 85% by 2025.
-
Elopak continued its investment in Blue Ocean Closures for fiber-based caps, strengthening its position in sustainable closure technology for carton packaging.
Beverage Carton Packaging Machinery Market Key Players
-
Tetra Pak International S.A.
-
SIG Combibloc Group AG
-
Elopak ASA
-
Syntegon Technology GmbH
-
KHS GmbH
-
Krones AG
-
R.A. Jones & Co. (Coesia)
-
Robert Bosch GmbH
-
Mitsubishi Electric Corporation
-
ACG Worldwide
-
Jacob White Packaging Ltd.
-
Bradman Lake Group Ltd.
-
Econocorp, Inc.
-
IMA Group
-
GEA Group Aktiengesellschaft
-
Serac Group
-
ProMach, Inc.
-
Koenig & Bauer AG
-
Nichrome India Pvt. Ltd.
-
Evergreen Packaging LLC
Beverage Carton Packaging Machinery Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.29 Billion |
| Market Size by 2035 | USD 2.13 Billion |
| CAGR | CAGR of 5.14% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Machine Type (Filling & Sealing Machines, Carton Forming Machines, Labeling Machines, Palletizing Machines) • By Carton Type (Aseptic Cartons, Gable-Top Cartons, Others) • By End-Use Application (Dairy, Juices & Soft Drinks, Plant-Based Beverages, Alcohol, Water, Others) • By Level of Automation (Fully Automated, Semi-Automated) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tetra Pak International S.A., SIG Combibloc Group AG, Elopak ASA, Syntegon Technology GmbH, KHS GmbH, Krones AG, R.A. Jones & Co. (Coesia), Robert Bosch GmbH, Mitsubishi Electric Corporation, ACG Worldwide, Jacob White Packaging Ltd., Bradman Lake Group Ltd., Econocorp, Inc., IMA Group, GEA Group Aktiengesellschaft, Serac Group, ProMach, Inc., Koenig & Bauer AG, Nichrome India Pvt. Ltd., Evergreen Packaging LLC |

Frequently Asked Questions
Key players include Tetra Pak International S.A., SIG Combibloc Group AG, Elopak ASA, KHS GmbH, Krones AG, Syntegon Technology GmbH, and Robert Bosch GmbH, among other packaging equipment manufacturers.
Growth in the plant-based beverage category and adoption of digital twin technology for real-time production line optimization represent the biggest opportunities for equipment suppliers.
Growth is driven mainly by rising focus on sustainable packaging solutions, alongside growing consumption of alcohol, health drinks, and electrolyte beverages across global markets.
By Carton Material, Aseptic Cartons held approximately 54.60% share in 2025, reflecting their ability to extend shelf life without refrigeration for up to twelve months.
Asia Pacific led with approximately 39.60% share in 2025, driven by changing lifestyles and rising beverage consumption across China and India.
