
Carbon Fiber Reinforced Plastics (CFRP) Market Report Scope & Overview:
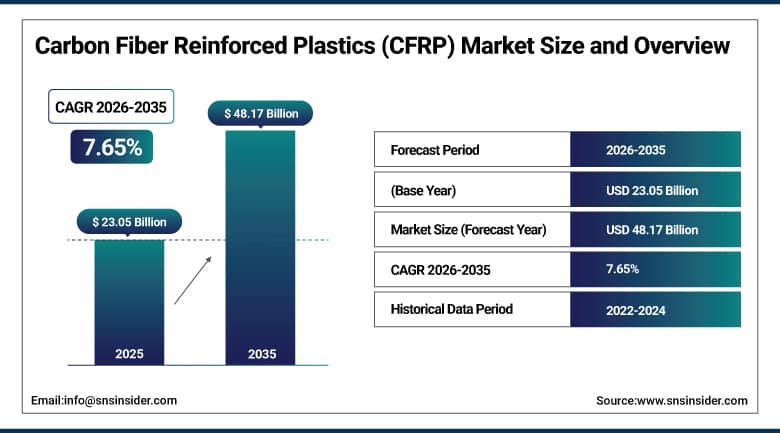
The Carbon Fiber Reinforced Plastics (CFRP) Market was valued at USD 23.05 Billion in 2025 and is expected to reach USD 48.17 Billion by 2035, growing at a CAGR of 7.65% from 2026-2035.
The Carbon Fiber Reinforced Plastics (CFRP) Market is witnessing growth owing to the rising need for lightweight and high-strength materials in aerospace, automotive, wind energy, and industrial sectors. Companies are resorting to CFRP to reduce the weight of the components and improve fuel efficiency, performance, and decrease energy consumption. The rising production of electric vehicles will drive demand as lightweight composite parts can help increase the driving range and efficiency of the vehicles. Furthermore, increased investment in renewable energy sources like wind turbines will increase the use of carbon fiber composite in large and high-performance structures.
⮞In March 2026, Composites United reported that global carbon fiber demand averaged about 148,500 tonnes in 2025, up about 17.4% on 2024, with a 2020-2025 growth rate of 10.79% a year. The jump in tonnage shows how fast composite use is spreading across industries.
To Get More Information On Carbon Fiber Reinforced Plastics (CFRP) Market - Request Free Sample Report
Carbon Fiber Reinforced Plastics (CFRP) Market Trends
-
Thermoplastic composites for faster, welded and recyclable aerostructures
-
Large-tow carbon fiber for wind blades and industrial uses
-
Recycled carbon fiber recovered from production scrap and end-of-life parts
-
Automated dry-fiber placement and out-of-autoclave processes
-
Capacity expansion in China, Japan and Europe
U.S. Carbon Fiber Reinforced Plastics (CFRP) Market Outlook
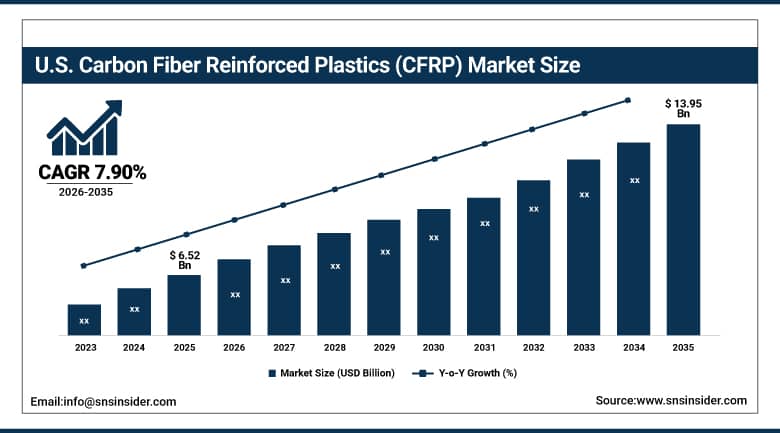
The U.S. Carbon Fiber Reinforced Plastics (CFRP) Market was valued at USD 6.52 Billion in 2025 and is expected to reach USD 13.95 Billion by 2035, growing at a CAGR of 7.90% from 2026-2035.
The U.S. Carbon Fiber Reinforced Plastics (CFRP) Market is expanding due to the rising demand for light and strong materials from various industries such as aerospace, automotive, defense, and renewable energy. The rising manufacture of electric cars has increased the adoption of CFRPs as a means of making cars light, efficient in energy consumption, and able to travel long distances. Moreover, the U.S. aerospace and defense industries are increasingly adopting advanced composites to improve the performance, durability, and efficiency of their planes. Investments in wind energy structures are also contributing to the rising demand for carbon fibers. Technological innovations in composite manufacturing automation and research in recyclable materials are also promoting the adoption of CFRPs.
⮞In December 2025, Boeing said 787 production stood at seven aircraft per month, with a planned rise to eight during 2026. The 787 is the largest U.S. user of carbon composite airframe structure, so build rates feed directly into fiber and prepreg orders.
Carbon Fiber Reinforced Plastics (CFRP) Market Segment Analysis
-
By Resin Type, the Thermoset segment dominated the Carbon Fiber Reinforced Plastics (CFRP) Market with approximately 78.71% share in 2025, while the Thermoplastic segment is the fastest growing with a CAGR of approximately 8.58%.
-
By Raw Material, the PAN-Based segment dominated the Carbon Fiber Reinforced Plastics (CFRP) Market with approximately 86.61% share in 2025, pitch-based carbon fiber segment is projected to be the fastest-growing segment, with an estimated CAGR of 6.5% from 2026 to 2035.
-
By Manufacturing Process, the Layup segment dominated the Carbon Fiber Reinforced Plastics (CFRP) Market with approximately 41.70% share in 2025, while the Filament Winding segment is the fastest growing with a CAGR of approximately 8.45%.
-
By End Use, the Aerospace and Defense segment dominated the Carbon Fiber Reinforced Plastics (CFRP) Market with approximately 49.32% share in 2025, while the Automotive segment is the fastest growing with a CAGR of approximately 8.88%.
By Resin Type, Thermoset Dominates the Carbon Fiber Reinforced Plastics (CFRP) Market and Thermoplastic Grows Fastest
Thermoset resins lead because epoxy systems bond well to carbon fiber, cure into stiff and strong laminates and have decades of certification in aircraft and wind blades. Aerospace programs lock in materials for the life of a platform, which keeps thermoset prepreg in demand. Designers and regulators know their behavior in fatigue, heat and moisture.
Thermoplastic CFRP is the fastest growing because it can be melted, welded and reshaped, which shortens cycle times and allows recycling. Polyetherketoneketone, polyaryletherketone and polyphenylene sulfide matrices suit aircraft brackets, fuselage parts and automotive components. Airframers are funding demonstrators, and tape-laying and stamping lines are moving toward serial production.
⮞In May 2026, Aernnova reported that the Clean Aviation project UPWING produced a 2-meter thermoplastic leading-edge demonstrator using carbon composite with welded stringers. The result shows thermoplastics advancing toward flight structure.
By Raw Material, PAN Dominates Carbon Fiber Reinforced Plastics Market; Pitch-Based Carbon Fiber to Register Fastest Growth
The PAN segment dominates the Carbon Fiber Reinforced Plastics (CFRP) Market owing to high strength to weight ratio, high tensile strength, and wide application across various applications. The carbon fiber reinforced plastics based on the PAN segment provide consistency in mechanical properties and are employed extensively in aerospace, automobiles, wind energy, sports goods, and industrial equipment sectors. Moreover, well-established manufacturing facilities, high process know-how, and commercial availability contribute to this segment's dominant market position. Apart from this, constant improvement in production efficiencies and fiber qualities is enabling its wide adoption by manufacturers for lightweight and high-performance composites.
The pitch-based carbon fiber segment is expected to grow rapidly driven by its extremely high stiffness, high thermal conductivity, and low coefficient of thermal expansion. These properties have rendered the pitch segment highly appropriate for applications requiring dimensional stability and effective heat dissipation. The rising requirement for advanced aerospace parts, satellites, thermal management systems, and high-performance industrial materials has created several opportunities in this regard. In addition, the growing interest in lightweight and specialized composite solutions is aiding the developments in this segment. Further advancements in precursor and fiber manufacturing technologies may add commercial value to this segment.
⮞In March 2025, Hera Group's Imola plant was reported to regenerate 160 tonnes a year of recycled carbon fiber with about 75% lower energy use than virgin fiber. Recycled fiber is emerging as a complement to virgin PAN supply.
By Manufacturing Process, Layup Dominates the Carbon Fiber Reinforced Plastics (CFRP) Market and Filament Winding Grows Fastest
Layup leads because hand and automated placement of prepreg is the standard route for aircraft skins, spars and large structures. Autoclave curing delivers the low void content that certification demands. Even as automation grows, layup remains the backbone of aerospace production, and suppliers invest in tape-laying and fiber placement machines.
Filament winding is the fastest growing as demand rises for pressure vessels, pipes, tanks and shafts. Hydrogen storage, compressed natural gas cylinders and offshore pipes use wound carbon composite for strength at low weight. Automated winding cells are repeatable and efficient for cylindrical parts, and new energy markets are adding orders.
⮞In September 2026, the University of Sheffield Advanced Manufacturing Research Centre reported a robotic dry-fiber cell running at about 200 kilograms an hour, against 20 to 50 kilograms an hour for fiber placement. The cell feeds a 2,400-ton matched-die press.
By End Use, Aerospace and Defense Dominates the Carbon Fiber Reinforced Plastics (CFRP) Market and Automotive Grows Fastest
Aerospace and defense leads because commercial jets, helicopters, military aircraft, missiles and satellites use large amounts of high-grade carbon composite. Lower weight cuts fuel burn and extends range, so airlines and manufacturers accept higher material prices. Long programs such as the A350 and 787 give suppliers stable multi-year volumes.
Automotive is the fastest growing as electric vehicle makers seek weight reduction to offset battery mass. Carbon composite is spreading from supercars to roof panels, structural parts, wheels and battery enclosures. Lower-cost large-tow fiber and faster molding are making wider use feasible. Regulation on emissions and efficiency adds pressure.
⮞In April 2026, the Global Wind Energy Council reported a record 165 gigawatts of new wind capacity installed in 2025, bringing cumulative capacity to 1,299 gigawatts. Longer blades rely on carbon fiber spar caps, which supports demand beyond aerospace.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
91.88 |
|
Europe |
Germany |
28.37 |
|
Asia Pacific |
China |
46.23 |
|
Latin America |
Mexico |
38.56 |
|
Middle East & Africa |
United Arab Emirates |
33.74 |
Asia Pacific Carbon Fiber Reinforced Plastics (CFRP) Market Insights
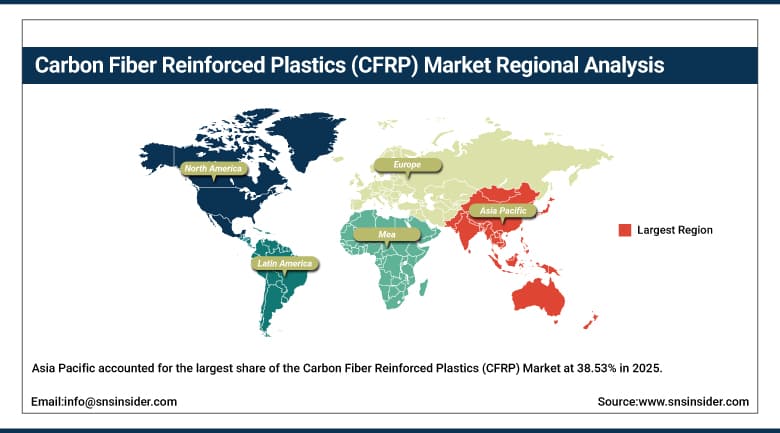
Asia Pacific accounted for the largest share of the Carbon Fiber Reinforced Plastics (CFRP) Market at 38.53% in 2025 and is also the fastest growing region, at a CAGR of 8.82% over 2026-2035. China, Japan, South Korea, India and Taiwan lead, hosting the largest fiber producers and fast-growing wind blade and electronics industries.
Chinese producers have added tens of thousands of tonnes of capacity and are moving into aerospace-grade fiber, which pressures global prices. Japanese firms keep technology leadership in high-performance grades. Quality consistency, export controls and price competition remain challenges for new entrants.
⮞In March 2026, Zhongfu Shenying reported 29,000 tonnes a year of PAN dry-jet wet-spun fiber capacity in operation and another 31,000 tonnes under construction. Capacity additions of this scale are reshaping global supply.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Carbon Fiber Reinforced Plastics (CFRP) Market Insights
North America held about 30.80% of the Carbon Fiber Reinforced Plastics (CFRP) Market in 2025, led by the United States and followed by Canada. Commercial aircraft, defense programs and space launch drive demand, and the region hosts major fiber, prepreg and aerostructure makers.
Federal research programs fund low-cost precursor development and recycling, and automakers are testing carbon composite in electric platforms. Trade tension with Asian suppliers has encouraged local capacity expansion. Aircraft rate increases, supply chain bottlenecks and certification timelines influence ordering.
⮞In July 2026, Hexcel reported that A350 and 787 programs reached their highest quarterly levels since before the pandemic and that it is restarting idled assets. Rising build rates are pulling carbon fiber and prepreg orders higher.
Europe Carbon Fiber Reinforced Plastics (CFRP) Market Insights
Europe held about 24.97% of the Carbon Fiber Reinforced Plastics (CFRP) Market in 2025 and is led by Germany, France, the United Kingdom, Spain and Italy. Airbus programs, wind turbine makers and premium automakers create steady demand, and the region has strong fiber, textile and resin suppliers.
Environmental rules and the Clean Aviation program push thermoplastics and recycling. High energy prices raise production costs for fiber makers, and competition from Asian suppliers is growing. Collaboration between universities, aerospace firms and materials makers keeps Europe at the forefront of composite technology.
⮞In July 2026, Airbus reported delivering 26 A350 aircraft in the first half of the year, with a rate of 12 a month still targeted for 2028. The A350 program is a large consumer of carbon composite structure.
MEA & Latin America Carbon Fiber Reinforced Plastics (CFRP) Market Insights
Latin America and the Middle East and Africa together hold about 5.70% of the Carbon Fiber Reinforced Plastics (CFRP) Market. In Latin America, Mexico, Brazil and Argentina lead through aerospace supply chains and wind projects. In the Middle East and Africa, the United Arab Emirates, Saudi Arabia and Turkey are building composite capacity.
Mexico hosts carbon fiber and aerostructure plants serving North American customers, while Brazil's aircraft industry buys composite parts. Gulf states are investing in aerospace manufacturing as part of diversification plans. Limited local fiber production and reliance on imports raise costs across both regions.
⮞In February 2026, the U.S. Department of Commerce reported that Mexico's aerospace sector grew from 100 manufacturing firms in 2004 to 368 by mid-2023, with exports growing about 14% a year over 2004-2024. Clusters in Baja California and Nuevo León include composites.
Market Dynamics
Growth Drivers: Aerospace Production Recovery and Wind Energy Expansion Drive Growth in the Carbon Fiber Reinforced Plastics (CFRP) Market
The recovery of aerospace production due to increased production by aircraft producers as well as efforts to overcome delivery backlogs is boosting demand for carbon fiber reinforced plastics. The use of carbon fiber composites in fuselages, wings, tail sections, and other aircraft parts is common because these materials have excellent strength, lightness, fatigue resistance, and corrosion resistance. Increased commercial air travel and upgrades to fleets are leading airlines to invest in fuel-efficient aircraft, creating sustained demand for advanced composites. Another major area of growth is wind energy.
Increased sizes of wind turbines call for longer and lighter blades for better energy generation and efficiency. Carbon fiber is being used increasingly in spar caps and other components where stiffness and weight are crucial. Moreover, the lightweighting of electric vehicles, hydrogen storage tanks, and industrial uses are increasing the pool of potential customers for CFRP manufacturers.
⮞In May 2026, Victrex reported that aerospace volumes rose about 9% in the six months to 31 March 2026 and that its aerospace composites program remained on track. Higher aerospace activity supports thermoplastic and carbon composite demand.
Restraints: High Energy Use and Production Cost Restrain Growth in the Carbon Fiber Reinforced Plastics (CFRP) Market
High energy expenditure during the production of carbon fibers is yet another market restraint. The production of carbon fiber entails the stabilization and carbonization process that involves high amounts of energy making production expensive to the manufacturers. Energy expenses coupled with varying price levels of electricity and precursors will make it difficult for producers to make profits and hinder the availability of affordable carbon fiber reinforced plastics parts.
Complex production process is an added constraint for CFRPs. Composite parts production may entail the use of specialized equipment, skilled workers, exacting production conditions and rigorous qualification process especially in aerospace and defense applications. The manufacturing process itself is accompanied by production losses while it is equally challenging to recycle the quality fiber from the composite parts. While recycling technology is being advanced, recycled fibers are not always suitable for demanding applications. As a result, there is stiff competition between glass fiber composites, aluminum and steel materials.
⮞In late 2025, Deakin University researchers writing in Advanced Composites and Hybrid Materials reported that virgin carbon fiber embodies 183 to 286 megajoules of energy per kilogram. The figure underlines the energy burden behind the material.
Opportunities: Recycled Fiber and Thermoplastic Composites Create Opportunities in the Carbon Fiber Reinforced Plastics (CFRP) Market
Recycled carbon fibers represent an essential opportunity for manufacturers of carbon fiber reinforced plastic (CFRP) to decrease materials’ cost, make resources more efficient, and deal with composite wastes. The fibers can be recovered using pyrolysis and other recycling techniques from manufacturing scrap, production cut-outs, and end-of-life composite parts. Reclaimed fibers can be included in chopped-fiber compound, nonwoven mat, and certain industrial products, which gives rise to potential applications in car parts, consumer products, construction industry, and equipment housings. Reliable collection systems along with higher-quality of fiber recovery could boost their market acceptance.
Thermoplastic composites represent another opportunity for future success due to the shorter cycle time, recyclability, and welding possibilities. Such attributes are beneficial for automotive manufacturers with high production volumes and aerospace suppliers that create lightweight structures. Enhanced automated forming, better material compatibility and design of composites could widen the range of their applications. Moreover, demands for sustainability and circular manufacturing contribute to the development of recycled composites and creation of materials recovery partnership.
⮞In August 2026, the European Union End-of-Life Vehicles Regulation entered into force, requiring at least 15% recycled plastic in new vehicles from September 2032 and 25% from September 2036. Recycled content rules favor recyclable composite materials.
Recent Developments
-
In March 2026, Toray Industries said Toray Carbon Fibers Europe in southwest France raised plant output from 5,000 to 6,000 tonnes a year, with full rate expected in the second half of 2026. The expansion adds aerospace-grade supply close to European customers.
-
In February 2026, Teijin launched Tenax Next HTS45 E23 24K, a standard-modulus carbon fiber that it said cuts carbon dioxide emissions by 36%. The company showed the fiber at JEC World as a drop-in material for existing processes.
-
In December 2025, Mitsubishi Chemical Group announced a phased expansion from 2025 to 2027 at Tokai in Japan and Sacramento in the United States. The company said the program roughly doubles carbon fiber capacity for high-end applications.
Carbon Fiber Reinforced Plastics (CFRP) Companies are:
-
Toray Industries, Inc.
-
Teijin Limited (Tenax)
-
Hexcel Corporation
-
Syensqo
-
SGL Carbon SE
-
Aksa Carbon
-
Park Aerospace Corp.
-
Victrex plc
-
Gurit Holding AG
-
Carbon Revolution
-
Aernnova Aerospace
-
Strata Manufacturing
Carbon Fiber Reinforced Plastics (CFRP) Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 23.05 Billion |
| Market Size by 2035 | USD 48.17 Billion |
| CAGR | CAGR of 7.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Resin Type (Thermoset and Thermoplastic) • By Raw Material (PAN, Pitch, Rayon, and Others) • By Manufacturing Process (Layup, Filament Winding, Pultrusion, Resin Transfer Molding, Compression Molding, Injection Molding, and Others) • By End Use (Aerospace and Defense, Automotive, Wind Energy, Sporting Goods, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Toray Industries, Inc., Teijin Limited (Tenax), Hexcel Corporation, Mitsubishi Chemical Group, Syensqo, SGL Carbon SE, Aksa Carbon, Park Aerospace Corp., Victrex plc, Arkema S.A., Gurit Holding AG, Carbon Revolution, Aernnova Aerospace, Strata Manufacturing |

Frequently Asked Questions
Key players include Toray Industries, Inc., Teijin Limited (Tenax), Hexcel Corporation, Mitsubishi Chemical Group, Syensqo, SGL Carbon SE, Aksa Carbon, Park Aerospace Corp., Victrex plc, Arkema S.A., Gurit Holding AG, Carbon Revolution, Aernnova Aerospace, Strata Manufacturing.
Key opportunities include recycled carbon fiber, thermoplastic composites, automotive and hydrogen storage uses and fast-growing Asia Pacific demand.
Aerospace production recovery and wind energy expansion are the main growth factors.
By Resin Type, the Thermoset segment dominated the market in 2025 with an estimated 78.71% share, supported by certified epoxy systems in aircraft and wind blades.
Asia Pacific dominated the market with a share of 38.53% in 2025, driven by large fiber capacity, wind blade production and growing industrial demand.
