
Cell Reprogramming Market Report Scope & Overview:
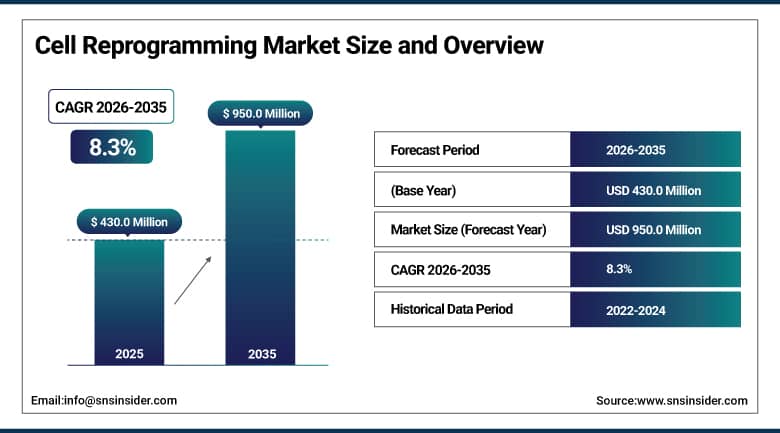
The Cell Reprogramming Market was valued at USD 430.0 Million in 2025 and is expected to reach USD 950.0 Million by 2035, growing at a CAGR of 8.3% from 2026–2035.
Cell reprogramming takes a mature, specialized cell, often skin or blood, and coaxes it back into an earlier, more flexible state, either fully pluripotent like an embryonic stem cell or directly converted into a different specialized cell type entirely. The technology traces back to Shinya Yamanaka's Nobel Prize-winning 2006 discovery that a handful of transcription factors could reprogram adult cells without touching an embryo, sidestepping the ethical debate that once defined stem cell research. Labs use reprogrammed cells to model disease, screen drug candidates, and increasingly manufacture actual cell therapies for patients.
In December 2025, Fate Therapeutics released updated clinical results for FT819, its iPSC-derived, off-the-shelf CAR T-cell program, reporting clinical response data alongside evidence that its manufacturing process could reliably scale to serve a broad patient population. The update matters beyond one company's pipeline: it's a real-world demonstration that cells reprogrammed from a single donor source can be manufactured at the volume and consistency a genuine commercial cell therapy business requires.
To Get More Information On Cell Reprogramming Market - Request Free Sample Report
Cell Reprogramming Market Trends
-
Non-integrating and small-molecule reprogramming methods continue gaining ground over older viral-vector approaches, as researchers and regulators alike prefer techniques that don't leave foreign genetic material permanently embedded in the reprogrammed cell.
-
Machine learning and AI tools are being integrated into reprogramming workflows to predict which cell lines will reprogram successfully, cutting down on the trial-and-error that has historically made the process slow and expensive.
-
Off-the-shelf, iPSC-derived cell therapies are moving from early clinical trials toward genuine commercial manufacturing scale, a shift that's reshaping how much of the industry's investment goes toward process development rather than pure discovery research.
-
Pharmaceutical and biotechnology companies are increasingly building or acquiring reprogramming capability in-house rather than relying entirely on academic collaborators, reflecting the technology's shift from a research tool toward a manufacturing platform.
-
Strategic joint ventures between pharmaceutical companies and industrial partners are emerging specifically to scale iPSC-based treatment manufacturing, combining pharma development expertise with engineering capability neither side typically has alone.
U.S. Cell Reprogramming Market Outlook
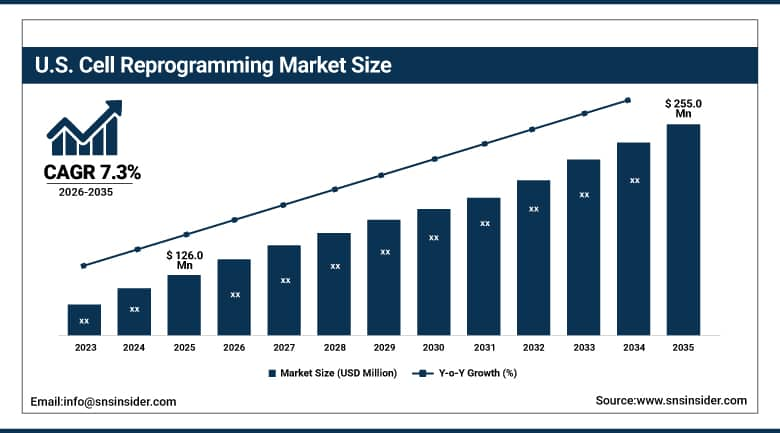
The U.S. Cell Reprogramming Market was valued at approximately USD 126.0 Million in 2025 and is expected to reach approximately USD 255.0 Million by 2035, growing at a CAGR of approximately 7.3%.
Demand in the United States is driven by a dense concentration of academic research institutions, biotechnology companies, and pharmaceutical developers working across the full spectrum of reprogramming applications, from basic disease modeling through clinical-stage cell therapy manufacturing. Growing NIH and private investment in regenerative medicine continues supporting steady research-stage demand, while an expanding pipeline of iPSC-derived cell therapies is pulling investment toward manufacturing-scale infrastructure. The country's deep venture capital base gives domestic biotech companies working on reprogramming-based therapeutics meaningfully better access to growth capital than most other markets.
In April 2025, Thermo Fisher Scientific opened an Advanced Therapies Collaboration Center in Carlsbad, California, giving researchers working on reprogramming-based cell and gene therapies dedicated access to process development, analytical, and manufacturing support under one roof. The facility reflects how much of the cell reprogramming industry's translational and manufacturing infrastructure remains concentrated in the United States even as basic research activity continues expanding globally.
Cell Reprogramming Market Segment Analysis
-
By Technology, the mRNA Reprogramming segment dominated the Cell Reprogramming Market with approximately 31.6% share in 2025, while the Small Molecule/Chemical segment is the fastest growing with a CAGR of approximately 11.4%.
-
By Product, the Instruments segment dominated the Cell Reprogramming Market with approximately 40.2% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 10.8%.
-
By Application, the Research segment dominated the Cell Reprogramming Market with approximately 64.9% share in 2025, while the Therapeutic segment is the fastest growing with a CAGR of approximately 11.2%.
-
By End User, the Research & Academic Institutes segment dominated the Cell Reprogramming Market with approximately 66.2% share in 2025, while the Biotechnology & Pharmaceutical Companies segment is the fastest growing with a CAGR of approximately 10.6%.
-
By Source of Cells, the Human Cells segment dominated the Cell Reprogramming Market with approximately 56.3% share in 2025, and is also the fastest growing with a CAGR of approximately 9.1%.
By Technology, mRNA reprogramming dominates, small molecule/chemical grows fastest
mRNA reprogramming held the largest share of the technology segment in 2025, favored for its integration-free profile and increasingly standardized, scalable workflows that don't leave any foreign genetic material behind in the reprogrammed cell. That safety advantage over older viral-vector methods has made mRNA the default choice for labs building toward eventual clinical translation rather than pure research use.
Small molecule and chemical reprogramming methods are growing fastest as researchers pursue an even simpler, potentially safer path to pluripotency that avoids introducing any genetic material, whether viral or mRNA, into the target cell at all. Success in this area would meaningfully lower both the cost and regulatory complexity of producing therapeutic-grade reprogrammed cells, which explains the intense research interest despite the technology still lagging mRNA and viral methods in reliability.
By Product, instruments dominate, services grow fastest
Instruments accounted for the largest product share in 2025, covering the specialized equipment, bioreactors, automated cell culture systems, and characterization instruments, that reprogramming labs need to run reproducible protocols at scale. Their essential role in every reprogramming workflow, combined with their high capital cost relative to consumable reagents, keeps instruments the largest single product category.
Services are growing fastest as pharmaceutical companies and smaller biotechs increasingly outsource reprogramming and iPSC line generation to specialized contract organizations rather than building in-house capability from scratch. That outsourcing trend is particularly pronounced among companies without the specialized expertise or capital to run reprogramming operations internally at the quality and scale clinical applications require.
By Application, research dominates, therapeutic grows fastest
Research applications accounted for the largest application share in 2025, spanning disease modeling, drug screening, and basic functional biology work conducted across academic and industry labs worldwide. The sheer breadth of ongoing basic and translational research activity keeps this the largest application by a wide margin even as therapeutic development accelerates.
Therapeutic applications are the fastest-growing category as iPSC-derived cell therapies advance from early-stage clinical trials toward genuine commercial manufacturing scale. Every successful clinical readout from a reprogramming-based therapy adds momentum to this shift, since positive results give both investors and regulators more confidence in the broader therapeutic approach.
By End User, research & academic institutes dominates, biotechnology & pharmaceutical companies grows fastest
Research and academic institutes accounted for the largest end-user share in 2025, reflecting the high volume of protocol development and discovery-stage experimentation that universities and research institutions conduct across the field. Much of the foundational technique development in cell reprogramming continues to originate from academic labs before commercial application follows.
Biotechnology and pharmaceutical companies are the fastest-growing end-user category as these organizations increasingly apply reprogramming techniques to drug discovery, personalized medicine, and therapeutic development. Patient-specific disease models built from reprogrammed cells let these companies test drug candidates with meaningfully better predictive accuracy than standard cell lines can offer, giving them a strong commercial incentive to expand internal reprogramming capability.
By Source of Cells, human cells dominates and grows fastest
Human cells held the largest share of the source-of-cells segment in 2025, reflecting the field's overwhelming focus on translational research and clinical applications directly relevant to human health and disease. Nearly every therapeutic-track reprogramming program works exclusively with human-derived cells, since animal models offer limited direct translational value for eventual clinical application.
Human cells are also the fastest-growing source category, an unusual case where the already-dominant segment continues gaining share rather than ceding ground to animal cell research. That continued acceleration reflects the field's broader shift from basic biological research, where animal models remain useful, toward clinical and commercial application, where human cells are essentially the only relevant source.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.0% |
|
Europe |
Germany |
25.0% |
|
Asia Pacific |
Japan |
36.0% |
|
Latin America |
Brazil |
37.0% |
|
Middle East & Africa |
UAE |
31.0% |
North America Cell Reprogramming Market Insights
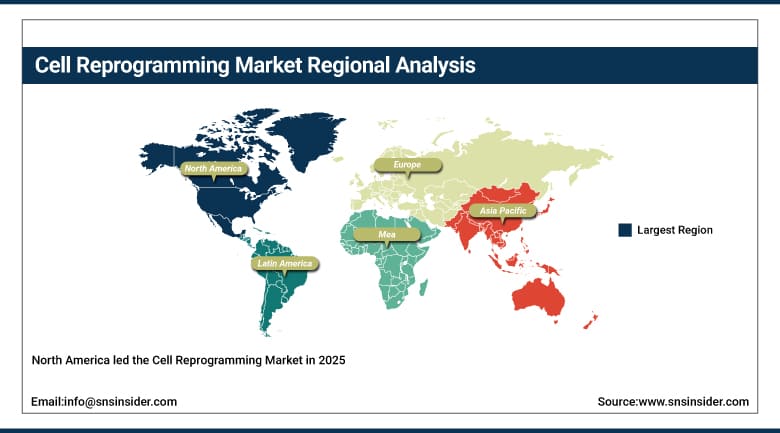
North America led the Cell Reprogramming Market in 2025, anchored by the United States' concentration of advanced research infrastructure, translational programs, and deep venture capital access for biotechnology companies developing reprogramming-based therapeutics. That combination of research depth and available growth capital keeps the region at the forefront of both basic research and clinical translation.
Canada contributes a meaningful share through its own strong academic research base and growing biotechnology sector, while Mexico's market remains largely nascent, dependent on collaboration with U.S. and Canadian research institutions. Cross-border research partnerships and investment activity tie much of North American demand together.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Cell Reprogramming Market Insights
The Asia Pacific region is projected to be the most rapidly growing region over the forecast period 2035, supported by the strong history of iPSC research in Japan due to Shinya Yamanaka's pioneering work done at Kyoto University and investments from the government in regenerative medicine. The rapid growth in the biotechnology industry in China along with domestic research investments is also adding fuel to Japan’s existing research platform.
Increasing South Korean biotech industry is contributing to more research programs and companies dedicated to reprogramming. The expanding pharmaceuticals and life science industry in India is also attracting early interest. Increasing investments in infrastructure for regenerative medicine in the region will continue driving the market growth in the future.
Europe Cell Reprogramming Market Insights
Europe represents a mature, research-intensive cell reprogramming market, supported by strong academic research infrastructure and a well-established regulatory framework for advanced therapy medicinal products. Germany anchors regional demand, home to several major life sciences companies and research institutions active in reprogramming technology development.
The United Kingdom, France, and Switzerland contribute meaningful research and commercial activity as well, each with strong biotechnology sectors and academic research programs focused on regenerative medicine. EU-level funding programs supporting advanced therapy development continue reinforcing research activity across the region.
MEA & Latin America Cell Reprogramming Market Insights
The Middle East and Africa host a smaller but rapidly developing share of the cell reprogramming market, with the UAE emerging as a notably fast-growing individual market as the country invests heavily in advanced healthcare and biotechnology infrastructure. Growth elsewhere in the region remains tied closely to the pace of broader healthcare and life sciences infrastructure development.
Latin America remains an early-stage market, with Brazil showing the clearest research and commercial interest given its scale as the region's largest life sciences and pharmaceutical sector. Argentina and Mexico are following developments closely, though commercial reprogramming activity across the broader region remains limited for now.
Market Dynamics
Growth Drivers: Expanding iPSC research and therapeutic pipeline growth fueling adoption
Expanding iPSC research activity across academic and industry labs is one of the clearest forces behind rising cell reprogramming demand, as disease modeling and drug screening workflows increasingly rely on patient-specific reprogrammed cells rather than standard immortalized cell lines. That shift toward more physiologically relevant research models is reshaping how pharmaceutical companies approach early-stage drug discovery.
Growing momentum in iPSC-derived cell therapy development adds a second major driver, as an expanding clinical pipeline of reprogramming-based therapeutics moves toward genuine commercial manufacturing scale. Every successful clinical milestone reinforces investor and pharmaceutical industry confidence in the broader therapeutic approach, pulling more capital and research activity into the field.
Restraints: High costs and manufacturing complexity limiting broader adoption
The high cost of cell reprogramming, spanning specialized reagents, instruments, and skilled technical labor, remains a real barrier for smaller academic labs and biotechnology companies working with limited research budgets. That cost sensitivity can slow adoption even among researchers who recognize reprogrammed cells' scientific advantages over conventional cell lines.
Manufacturing complexity adds a further restraint, particularly for therapeutic applications where producing clinical-grade reprogrammed cells at consistent quality and meaningful scale remains technically difficult and capital-intensive. Companies without deep process development expertise face a genuinely steep path from a successful lab-scale reprogramming protocol to a manufacturable commercial product.
Opportunities: Off-the-shelf cell therapy manufacturing and AI-driven optimization opening new growth avenues
Off-the-shelf, iPSC-derived cell therapy manufacturing represents a genuinely significant opportunity, letting companies produce a standardized therapeutic product from a single well-characterized donor source rather than manufacturing a personalized product for each individual patient. Companies that successfully scale this manufacturing model are positioned to capture substantial value as more reprogramming-based therapies reach commercial approval.
AI-driven workflow optimization offers a second significant opportunity, letting developers predict which cell lines and protocols will reprogram successfully before committing significant lab time and resources to a full experimental run. Companies that build genuine AI-driven optimization capability are positioned to meaningfully cut both the cost and timeline of reprogramming research and development relative to traditional trial-and-error approaches.
Recent Developments:
-
December 2024: Sumitomo Chemical and Sumitomo Pharma established RACTHERA Co., Ltd., a joint venture focused on regenerative medicine and cell therapy, aiming to accelerate the development and commercialization of iPSC-based treatments.
-
2025: Machine learning and artificial intelligence tools continued being integrated into reprogramming workflows, aimed at improving efficiency and predicting which cell lines will reprogram successfully before committing significant lab resources.
-
2025: Multiple developers advanced safer, non-integrating reprogramming methods, including small-molecule and chemical approaches, aimed at reducing the genomic integration risk associated with earlier viral-vector techniques.
-
July 2023: Pluristyx and the Advanced Regenerative Manufacturing Institute (ARMI) | BioFabUSA signed an agreement to scale production and distribution of clinical-grade induced pluripotent stem cells for gene and cell therapy manufacturing.
Cell Reprogramming Market Key Players
-
Thermo Fisher Scientific Inc.
-
Lonza Group AG
-
Merck KGaA
-
STEMCELL Technologies Inc.
-
REPROCELL Inc.
-
Bio-Techne Corporation
-
Fujifilm Holdings Corporation
-
Miltenyi Biotec B.V. & Co. KG
-
Takara Bio Inc.
-
Sartorius AG
-
bit.bio Ltd.
-
Fate Therapeutics, Inc.
-
Sumitomo Pharma Co., Ltd.
-
Cynata Therapeutics Limited
-
Ncardia
-
Cellectis S.A.
-
OriGene Technologies, Inc.
-
Creative Biolabs
-
Axol Bioscience Ltd.
-
Cell Applications, Inc.
Cell Reprogramming Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 430.0 Billion |
| Market Size by 2035 | USD 950.0 Billion |
| CAGR | CAGR of 8.3% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Technology (mRNA Reprogramming, Viral Vector-Based, Non-Integrating/Episomal, Small Molecule/Chemical, Others) • by Product (Instruments, Reagents & Kits, Services) • by Application (Research, Therapeutic) • by End User (Research & Academic Institutes, Biotechnology & Pharmaceutical Companies, Contract Research Organizations, Others) • by Source of Cells (Human Cells, Animal Cells) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Thermo Fisher Scientific Inc., Lonza Group AG, Merck KGaA, STEMCELL Technologies Inc., REPROCELL Inc., Bio-Techne Corporation, Fujifilm Holdings Corporation, Miltenyi Biotec B.V. & Co. KG, Takara Bio Inc., Sartorius AG, bit.bio Ltd., Fate Therapeutics, Inc., Sumitomo Pharma Co., Ltd., Cynata Therapeutics Limited, Ncardia, Cellectis S.A., OriGene Technologies, Inc., Creative Biolabs, Axol Bioscience Ltd., Cell Applications, Inc. |
Frequently Asked Questions
The Cell Reprogramming Market is expected to grow at a CAGR of 8.3% from 2026 to 2035.
The Cell Reprogramming Market was valued at USD 430.0 Million in 2025.
Expanding iPSC research activity across academic and industry labs, alongside growing momentum in iPSC-derived cell therapy development toward commercial manufacturing scale.
Research dominated with approximately 64.9% share in 2025, while Therapeutic is the fastest growing segment with a CAGR of approximately 11.2%.
North America dominated the Cell Reprogramming Market in 2025, while Asia Pacific is the fastest-growing region.
