
Compounding Pharmacies Market Report Scope and Overview
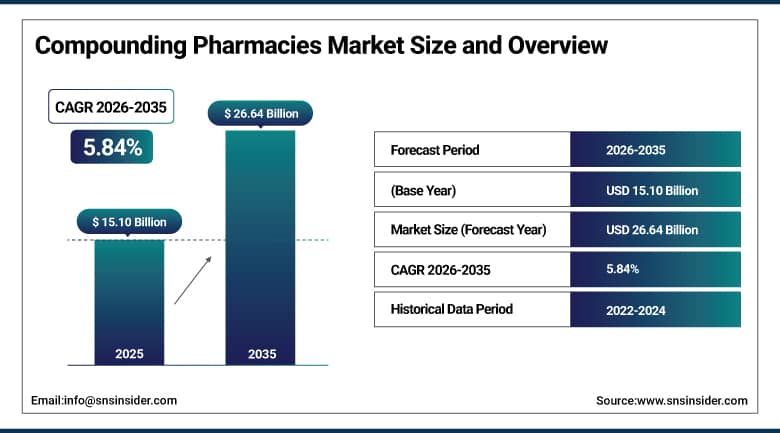
The Compounding Pharmacies Market was valued at USD 15.10 Billion in 2025 and is estimated at USD 15.98 Billion in 2026. The market is forecast to reach USD 26.64 Billion by 2035, registering a CAGR of 5.84% from 2026 to 2035. Growth reflects demand for personalized doses and formulations, shortages of commercial drugs, sterile outsourcing by hospitals, and growing use of hormone, pain, and dermatology preparations. The scope covers revenue of traditional pharmacies and outsourcing facilities that prepare customized medicines. Hospital, clinic, and community channels are all included in the estimate.
To Get More Information On Compounding Pharmacies Market - Request Free Sample Report
Key Market Trends & Insights
-
By therapeutic area: Pain management held the largest market share of 33.60% in 2025.
-
By sterility: Sterile held the largest market share of 58.40% in 2025.
-
By dosage form: Oral held the largest market share of 37.60% in 2025.
-
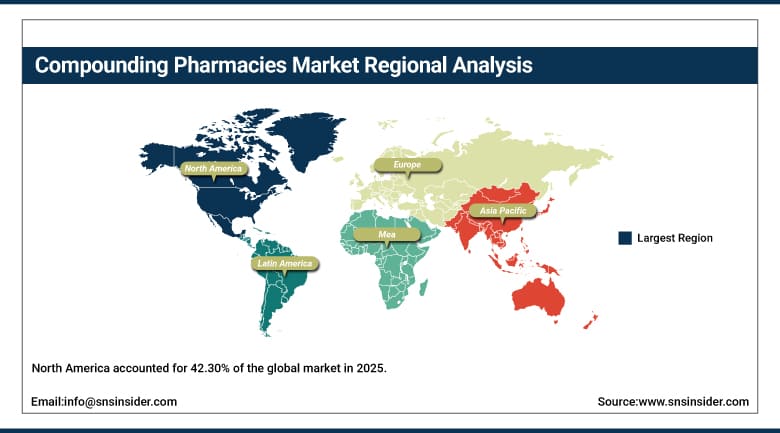
North America accounted for the largest regional share of 42.30% in 2025.
-
Asia Pacific is projected to register the fastest regional CAGR of 7.24% from 2026 to 2035.
-
The U.S. is the leading country market, supported by a large network of licensed compounding pharmacies, registered outsourcing facilities, and sustained demand for hormone, pain, and sterile preparations.
Growth Outlook
Quality standards for compounded preparations are rising and shaping the supplier base. In November 2023, the revised United States Pharmacopeia general chapters on nonsterile and sterile compounding became official, alongside the chapter on handling hazardous drugs, with updated rules for beyond-use dates, facility design, and personnel training. Pharmacies that invest in cleanrooms, testing, and documentation can serve hospitals and clinics that demand compliant products, while smaller operators exit or outsource sterile work to registered facilities. Compliance is now a selling point.
Telehealth is widening the channel for personalized prescriptions. In December 2025, the Drug Enforcement Administration, with the Department of Health and Human Services, extended its telemedicine flexibilities for prescribing controlled substances through the end of 2026. Clinics and online providers continue to route prescriptions for hormones, pain creams, and other customized therapies to partner pharmacies, and this channel adds patients who would otherwise not reach a compounding pharmacy. Several online providers have signed pharmacy partnerships to handle fulfillment and patient counseling.
Market Dynamics:
Driver: Personalized Dosing, Drug Shortages, and Hospital Outsourcing Support Demand
Hospitals and clinics rely on outsourcing facilities for ready-to-use sterile syringes and bags. In November 2026, the U.S. Food and Drug Administration listed 100 registered outsourcing facilities, up from 89 in early 2025, which reflects steady entry by firms that supply hospital pharmacies with prefilled doses. Such products save nursing time, reduce errors, and ease shortages of commercial injectables, and health systems sign multi-year supply contracts that give facilities predictable volumes. New entrants also include sterile specialists that focus on cardiac surgery solutions, parenteral nutrition, and anesthesia syringes, which are among the products most affected by supply interruptions. Contracts of this kind also reduce waste of expiring stock.
Personalization remains the core reason patients use compounding. Prescribers order preparations for patients who need a different strength, dosage form, or an ingredient free of dyes and allergens, such as liquids for children, topical combinations for pain, and bioidentical hormones. Aging populations, rising use of pain and dermatology therapies, and shortages of commercial products create steady demand, and many pharmacies add services such as veterinary compounding and pediatric flavoring. Prescribers also value the ability to adjust a strength for patients with kidney or liver conditions, and pharmacies that provide clinical consultation, labeling, and delivery to the patient's home earn repeat business.
Restraint: Enforcement Against Copies of Approved Drugs and Contamination Risks Limit Growth
Pharmacy compounding will be reduced by regulators. In April 2026, the National Association of Boards of Pharmacy sent out a memo to state boards reminding them of the position of the U.S. government that semaglutide and tirzepatide were not listed in either the shortage list or the bulk drug substances list for outsourcing facilities. There will be fewer revenues coming from the sale of weight loss drugs because sales increased rapidly in 2024 but now the revenue is declining and some pharmacies have stopped manufacturing these products. Pharmacies which have been making money from these products will experience low sales and lawsuits. Pharmacies which have telehealth business will suffer the most.
State rules add further limits. In June 2025, the California Board of Pharmacy adopted rules defining when a compounded drug is essentially a copy of a commercial product, which restrict preparations that duplicate approved drugs without a documented clinical need. Inspection findings on sterile processes, product recalls, and warning letters raise compliance costs for outsourcing facilities, and insurers and hospitals review supplier quality records closely before they renew contracts. Staff training, environmental monitoring, and third-party testing add to operating costs, and facilities that cannot meet them often exit the market or sell contracts to larger rivals. Insurers may also reject claims for products that resemble commercial drugs.
Opportunity: Policy Clarity, Hospital Outsourcing, and Veterinary and Pediatric Segments Create New Revenue
Legislation is being drafted to clarify the boundary between pharmacies and manufacturers. In December 2025, members of the U.S. Congress introduced the SAFE Drugs Act, which would redefine when a compounded drug is essentially a copy and set a definition for large-scale outsourcing facilities. A clear rulebook would let compliant facilities plan capacity and products with confidence, and it would favor operators with strong quality systems over firms that relied on regulatory gray areas. Investment in automation and robotic filling can also lower the cost of compliance and increase output per cleanroom. Clearer definitions would also reduce disputes with inspectors.
Industry bodies are also seeking orderly transitions. In February 2026, the Alliance for Pharmacy Compounding wrote to federal regulators asking for predictable timelines and slower enforcement of recent policy changes. If regulators agree, pharmacies would have time to redirect capacity toward preparations with clear clinical need, such as hormone therapy, pediatric liquids, ophthalmic products, and veterinary medicines, which supports a more diversified and stable revenue base. Hospital systems are also asking for dual-sourcing arrangements, which gives qualified outsourcing facilities a chance to win new accounts even when a larger competitor already serves part of the demand. Specialty clinics are likely to remain steady customers throughout the transition.
Market Characteristics & Concentration
The Compounding Pharmacies Market is Highly Fragmented. Thousands of community pharmacies manufacture custom-made medications for their local patients while a few outsourcing facilities manufacture sterile products in bulk for hospitals and clinics. Competition is defined by pharmacist skill, quality control, regulatory status, and relationship with the prescribers. Most pharmacies are independent and receive patient referrals from local doctors, dentists, and veterinarians in order to keep the market fragmented with many players.
There is an increased level of consolidation in outsourcing pharmacies due to rising compliance expenses and some pharmacies leaving the business. Consolidations happen through larger pharmacies acquiring the product lines and customers of exiting pharmacies, ingredient suppliers offering services, and telemedicine companies partnering with pharmacies. Specialty and veterinary pharmacies are still catering to their local markets. Inspection record and history are the primary criteria hospitals consider when choosing their suppliers. Consistently there are consolidation activities due to retirements of proprietors.
Litigation is also shaping the market. In April 2025, a federal court in Texas denied a request for a preliminary injunction by an outsourcing trade group seeking to block federal action on compounded semaglutide. Such cases influence how aggressively agencies enforce rules, and pharmacies maintain legal and regulatory teams to track decisions. Trade groups also lobby for definitions that protect traditional pharmacies. Counsel track rulings closely. Associations also file comments on proposed agency rules.
Analyst Perspective
Compounding pharmacies serve patients whose needs are not met by commercial products, and hospitals that depend on outsourced sterile preparations. Revenue from copies of newly approved obesity drugs, which boosted growth in earlier years, is receding under tighter enforcement, while hormone, pain, dermatology, pediatric, and sterile hospital preparations provide a stable base. Quality compliance is now the main basis of competition, and consolidation among outsourcing facilities is expected to continue. An SNS Insider Analyst, Santosh Bhul, commented, "Operators that invest in sterile quality systems, diversify across clinical niches, and build hospital supply contracts will outgrow the market, and Asia Pacific will add the fastest demand through 2035."
Therapeutic Area Insights
Pain management had the biggest market share at 33.60% in 2025. Compound creams, gels, and patches have a mixture of anti-inflammatories, local anesthetics, and muscle relaxers at strengths not available in the commercial setting and are prescribed by doctors for those patients who cannot take their oral opioids and systemic drugs. Order flow is continuous from sports clinics, pain clinics, and workers compensation, and bases are custom-made for better absorption with fewer side effects. The concentration is adjusted by pharmacists in consultation with the prescriber, and demand is consistent in neuropathic, arthritic, and post-operative pain patients.
Hormone replacement therapy is projected to grow at the fastest CAGR of 7.52% from 2026 to 2035. Prescribers order bioidentical estrogen, progesterone, and testosterone in custom doses and forms such as creams, troches, and pellets, and demand is rising as more women and men seek treatment for menopause and age-related hormone decline. Dermatology, oncology supportive care, and nutritional supplements add further demand, while pediatric and veterinary preparations are a growing specialty. Pharmacies that provide consultation, testing, and monitoring support earn stronger loyalty, and telehealth clinics refer a growing number of patients for this type of therapy.
Sterility Insights
Sterile products accounted for 58.40% of the highest market share. They consist of injectable drugs, intravenous drips, prefilled syringes, eye drops, and compounded infusion solutions manufactured using the sterile process. The products are purchased by hospitals, surgical centers, and other healthcare centers from outsourced organizations to cut down cost and avoid mistakes, and rely on vendors for the supplies that are in short supply. The high cost per unit and repeat purchase contract form the key income pool for sterile services. Organizations that have current registration and a good record of inspection are favored, and hospitals seek for stability and sterility test results with each order.
Non-sterile formulations will witness the highest CAGR of 6.38% during 2026-2035. Non-sterile formulations like creams, ointments, capsules, suspensions, and flavored liquids are produced by community pharmacists and specialists for adults, children, and pets, and due to the minimal regulatory requirements and capital investment, independent pharmacists also find it easier to enter this market. Teleprescriptions and the increasing popularity of hormone therapy and dermatological treatments have increased demand for these orders. In addition to that, specialists also prepare formulations for veterinarians and pediatrics upon their demand, and these custom-made products are more profitable.
Dosage Form Insights
Oral preparations held the largest share of 37.60% in 2025. Capsules, tablets, troches, suspensions, and flavored liquids allow prescribers to adjust strengths, remove allergens, and prepare medicines for children, older adults, and patients who cannot swallow tablets. Community pharmacies prepare most oral products on request, and demand is steady because many patients rely on them for long-term therapy. Flavoring services for pediatric and veterinary patients further support volumes. Pharmacists also prepare dye-free and sugar-free versions on request, which is valuable for patients with allergies or metabolic conditions and keeps demand stable.
Parenteral preparations are projected to grow at the fastest CAGR of 7.28% from 2026 to 2035. Outsourcing facilities prepare syringes, vials, and bags for hospitals and clinics, and demand is supported by drug shortages, nursing labor constraints, and quality rules on sterile processes. Topical creams, gels, and patches and other forms add further demand, while ophthalmic and inhalation products are growing from a smaller base. Automation of filling and inspection lines is lowering costs, and facilities that invest in isolators and robotic systems can raise output without proportionately higher labor needs.
Regional Insights:
North America accounted for 42.30% of the global market in 2025. The region has a large network of licensed compounding pharmacies, registered outsourcing facilities, and a regulatory structure that separates traditional pharmacies from outsourcing facilities. In June 2025, Health Canada issued a position document that treats most compounded GLP-1 activity as manufacturing, which narrows what Canadian pharmacies can offer. Prescriber demand for custom doses remains strong. Canada adds demand through hospital pharmacies and community providers.
Get Customized Report as Per Your Business Requirement - Enquiry Now
U.S. Compounding Pharmacies Market
The size of the U.S. market was estimated to be USD 5.49 Billion in 2025 and forecasted to exhibit a CAGR of 5.46% between 2026 and 2035. There are tens of thousands of licensed compounding pharmacies and more than 100 outsourcing facilities in the country, driven by the demand for pain, hormones, dermatology, and sterile hospital products. In July 2025, the Ohio Board of Pharmacy released guidelines on GLP-1 compounded products indicating how states follow federal legislation. Each state pharmacy board licenses and regulates operators of pharmacies, resulting in a fragmented set of regulations that large organizations handle via compliance departments.
The operators are changing the portfolio due to enforcement cases against weight loss preparations, and some of them are shifting focus towards hospitals' contracts, hormone treatments, and animal drugs. The telehealth companies are still working with pharmacies, and outsourcing facilities are acquiring the portfolios of companies that have left the industry. The buyers care about inspection history, consistent deliveries, and clinical assistance. Hospitals' group purchasing organizations are reducing their suppliers, and outsourcing facilities with broad portfolio and consistent deliveries during shortages can get better negotiating power, and independent community pharmacies focus on hormones, pain, and pediatric drugs.
Europe Compounding Pharmacies Market
Europe held a share of 26.60% of the world market in 2025, and Germany, the UK, France, Italy, and Spain were among the leading markets at the country level. Preparation of magistral formula occurs as per the national regulation and mostly occurs at the hospital pharmacy. In October 2025, the medicines regulator of the UK closed a facility producing fake weight loss injections, an indication of regulatory efforts in preventing illegal manufacturing. There is investment in central preparation units in Germany, France, and the Netherlands for hospital pharmacies.
Asia Pacific Compounding Pharmacies Market
Asia Pacific accounted for 22.70% of the market in 2025 and is anticipated to register the fastest regional CAGR of 7.24% from 2026 to 2035. In October 2024, Australia's Therapeutic Goods Administration ended compounding and supply of GLP-1 products by pharmacists, which shows how rules are tightening in some markets. Japan, India, China, and Australia lead demand through hospital pharmacies, specialty clinics, and growing private pharmacy networks. Rising incomes and aging populations support further volume.
Latin America Compounding Pharmacies Market
Latin America accounted for 4.60% of the market in 2025, with Brazil as the leading country market followed by Mexico, Argentina, and Colombia. Compounding pharmacies, known locally as manipulation pharmacies, are well established in Brazil and serve dermatology, nutrition, and hormone prescriptions. Regulators set quality and licensing rules, and private demand is supported by prescriber habits and the cost advantage of custom preparations. Dermatology and hormone prescriptions remain the main growth areas, and regulators periodically update good practice rules for manipulation pharmacies.
Middle East & Africa Compounding Pharmacies Market
Middle East & Africa accounted for 3.80% of the market in 2025, with Saudi Arabia, the United Arab Emirates, Turkey, South Africa, and Egypt as the main country markets. Hospital pharmacies in Gulf countries prepare sterile and oncology products, while private clinics offer dermatology and hormone preparations. Regulators are developing licensing frameworks, and most active ingredients and equipment are imported across the region. Investment in oncology centers and private hospitals adds further demand for sterile preparations in the Gulf region.
Key Compounding Pharmacies Market Company Insights:
Companies in the compounding pharmacies market are focusing on sterile quality systems, hospital supply contracts, diversification into hormone, pediatric, and veterinary preparations, and portfolio consolidation through acquisitions. Outsourcing facilities are investing in cleanrooms, testing, and documentation, while ingredient suppliers expand services and partnerships. Telehealth firms continue to work with licensed pharmacies.
Key Compounding Pharmacies Companies:
-
Fagron
-
QuVa Pharma
-
SCA Pharmaceuticals
-
Nephron Pharmaceuticals
-
Leiters Health
-
Empower Pharmacy
-
Wells Pharma of Houston
-
Olympia Pharmaceuticals
-
Hims & Hers
-
Medisca
Recent Developments
-
In October 2026, Medisca announced a strategic partnership with EUROAPI to secure access to active ingredients and peptides.
-
In October 2026, Nephron Pharmaceuticals named Haywood Miller interim chief executive officer as its founder stepped down from the role.
-
In September 2026, QuVa Pharma acquired the outsourcing portfolio of the Central Admixture Pharmacy Services unit of B. Braun, including cardioplegia, parenteral nutrition, and heparin products.
-
In September 2026, Empower Pharmacy received an FDA warning letter citing regular large-volume production of copies of commercial GLP-1 drugs and insanitary conditions.
-
In June 2026, Olympia Pharmaceuticals, through its Wesley brand, launched three multi-dose injectables prepared as outsourcing facility products.
-
In March 2026, Hims & Hers agreed with Novo Nordisk to offer branded Wegovy and Ozempic and to stop advertising compounded semaglutide.
-
In November 2025, Wells Pharma of Houston received an FDA warning letter citing labeling, current good manufacturing practice, and insanitary conditions at its outsourcing facility.
Scope and Research Methodology
This report defines the compounding pharmacies market as the revenue generated by traditional compounding pharmacies and outsourcing facilities that prepare customized medicines by mixing, altering, or combining ingredients to meet individual patient or institutional needs. Coverage includes sterile and non-sterile preparations in oral, topical, parenteral, and other dosage forms, used in pain management, hormone replacement therapy, dermatology, oncology, and other areas. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are stated in USD. Commercial manufacturing of approved drugs and retail sales of finished products are outside the scope. Retail sales of over-the-counter products and manufacturing of generic drugs are excluded from the market definition.
The research program combines secondary and primary work. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, pharmacy directors, procurement managers, and other stakeholders across the value chain. These conversations validate assumptions, adoption rates, and pricing, and they test the direction of demand in each region and application before any figure is finalized for the study. Every interview follows a structured guide so that responses are comparable across respondents and regions, and findings are logged against the assumptions they affect.
Market engineering follows a bottom-up build from prescription volumes, price bands by preparation type, and facility revenue, cross-checked top-down against pharmacy counts, hospital spending, and prescription indicators. Estimates are triangulated across these routes until the results converge within an acceptable range. Forecasts incorporate the drivers that shape demand, including regulation, technology maturity, and macroeconomic conditions. Senior analysts review every estimate, assumption, and narrative section for consistency before release, and figures are checked against the segment and regional totals so that the final model remains internally coherent. Where inputs differ, analysts revisit the underlying assumptions with sector experts and adjust the model only when the evidence supports a change, so that the published figures stay traceable to documented inputs.
Compounding Pharmacies Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 15.10 Billion |
| Market Size by 2035 | USD 26.64 Billion |
| CAGR | CAGR of 5.84% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Therapeutic Area (Pain Management, Hormone Replacement Therapy, Dermatology, Oncology, Nutritional Supplements, and Others) • By Sterility (Sterile and Non-Sterile) • By Dosage Form (Oral, Topical, Parenteral, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Fagron, QuVa Pharma, SCA Pharmaceuticals, Nephron Pharmaceuticals, Leiters Health |

Frequently Asked Questions
The market was valued at USD 15.10 Billion in 2025 and is projected to reach USD 26.64 Billion by 2035.
The market is expected to register a CAGR of 5.84% from 2026 to 2035.
North America led the market with a 42.30% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 7.24% from 2026 to 2035.
Pain management led the therapeutic area segment with a 33.60% share in 2025, and sterile preparations led the sterility segment.
Key players include Fagron, QuVa Pharma, SCA Pharmaceuticals, Nephron Pharmaceuticals, and Leiters Health.
