
Conformal Coatings Market Report Scope & Overview:
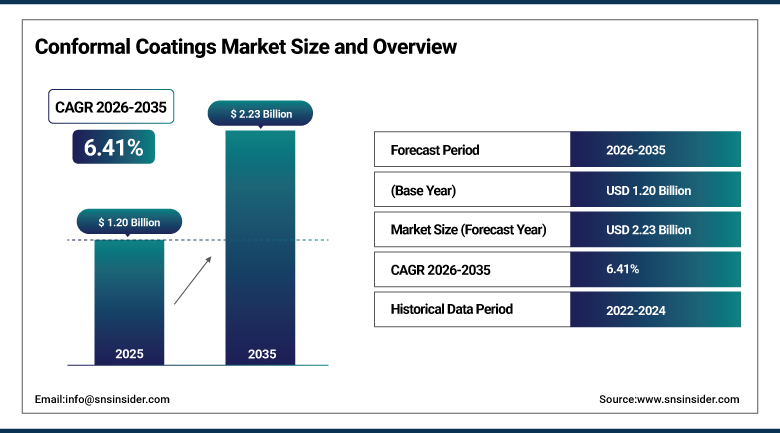
The Conformal Coatings Market was valued at USD 1.20 Billion in 2025 and is expected to reach USD 2.23 Billion by 2035, growing at a CAGR of 6.41% from 2026-2035.
The Conformal Coatings Market is experiencing steady growth due to rising requirement of conformal coatings that will protect the electronics against moisture, dust, chemicals, corrosion, and temperature variations. Growing demands for consumer electronics, automotive electronics, telecommunication, and industrial automation have boosted the need for advanced conformal coatings in order to improve the durability and performance of electronic components. In addition, the rise in the use of electric vehicles, advanced driver assistance system, and electronic devices is driving the Conformal Coatings Market, as there is need of protection of sensitive circuit board and electronic assembly. In addition, there is rising demand for advanced conformal coatings due to adoption of 5G infrastructure.
⮞In February 2026, the Semiconductor Industry Association reported that global semiconductor sales reached a record level in 2025, rising 25.6% year on year. Higher chip output enlarges the population of printed circuit assemblies that need conformal protection, which supports coating demand across the Conformal Coatings Market.
To Get more information Conformal Coatings Market - Request Free Sample Report
Conformal Coatings Market Trends
-
Migration from solvent-based chemistries to UV-cured, solvent-free and dual-cure systems is gathering pace.
-
PFAS-free and bio-based formulations are gaining priority as the European restriction process advances.
-
Selective dispensing and vapor deposition are replacing manual spraying on high-reliability assemblies.
-
Aerospace and defense accreditation is pulling coating services closer to regional production hubs.
-
Rising electronics content in vehicles and devices is lifting coated board volumes worldwide.
U.S. Conformal Coatings Market Outlook
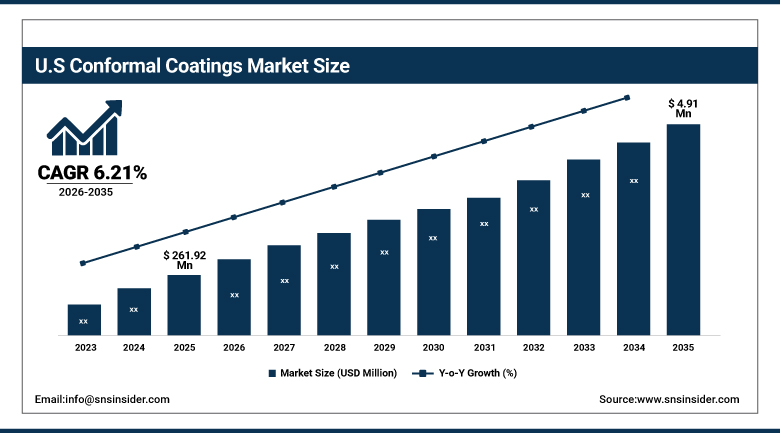
The U.S. Conformal Coatings Market was valued at USD 261.92 Million in 2025 and is expected to reach USD 478.43 Million by 2035, growing at a CAGR of 6.21% from 2026-2035.
The U.S. Conformal Coatings Market is witnessing steady growth due to increasing demands of protection of advanced electronic materials used in various industries like automotive, aerospace, defense, telecommunications, and industries. Adoption of electric vehicles, ADAS and connected automotive systems is enhancing the demand for such materials that protect the sensitive electronic parts from moisture, chemicals, corrosion, and heat. There is a significant presence of semiconductor manufacturers, electronics manufacturers, and aerospace and defense companies in the country, which is fueling market growth. Investment in domestic electronics manufacturing, 5G technology, and industrial automation has increased the demands. Moreover, the focus on the reliability and life expectancy of electronic parts is enhancing the growth of the market.
⮞Boeing reported in January 2026 that it delivered 600 aircraft during 2025, its strongest year since 2018. Each aircraft carries extensive avionics and cabin electronics that require conformal protection, so rising delivery rates sustain U.S. coating demand.
Conformal Coatings Market Segment Analysis
-
By Type, the Acrylic segment dominated the Conformal Coatings Market with approximately 40.75% share in 2025, while the Silicone segment is the fastest growing with a CAGR of approximately 7.21%.
-
By Technology, the Solvent-Based segment dominated the Conformal Coatings Market with approximately 55.78% share in 2025, while the UV-Cured segment is the fastest growing with a CAGR of approximately 7.44%.
-
By Application Method, the Spray segment dominated the Conformal Coatings Market in 2025, while the Chemical Vapor Deposition segment is the fastest growing with a CAGR of approximately 7.31%.
-
By End Use, the Consumer Electronics segment dominated the Conformal Coatings Market with approximately 45.00% share in 2025, while the Aerospace and Defense segment is the fastest growing with a CAGR of approximately 7.31%.
By Type, Acrylic Dominates the Conformal Coatings Market and Silicone Grows Fastest
The Acrylic segment dominates the Conformal Coatings Market because of the extensive use of acrylic coatings in electronic assemblies, printed circuit boards, and consumer electronic products. Acrylic coatings exhibit good moisture resistance property, good dielectric property, ease of application, and low cost of processing. High drying speed and easy removability for repair and rework purposes make acrylic coatings ideal for high volume manufacturing of electronics. In addition, the compatibility with a wide range of substrates and ease of manufacture process further support the usage of acrylic coatings in automotive, industrial, and telecommunication electronics applications.
The Silicone segment is witnessing the fastest growth owing to its superior resistance to high temperatures, moisture, chemicals, and environmental conditions. These properties make silicone coatings ideal for harsh applications in the electric vehicles, aerospace, defense, and industrial electronics segments. Increasing usage of electronic components in high temperature conditions is driving the growth in the segment. Increasing preference for flexible coatings, which can withstand thermal expansion and mechanical stress, is also driving the use of silicone based coatings.
⮞In April 2025, the Taiwan Printed Circuit Association projected that global printed circuit board output would grow 5.5% for the year. Every board in that output is a candidate for protective coating, which anchors volume for the Conformal Coatings Market.
By Technology, Solvent-Based Dominates the Conformal Coatings Market and UV-Cured Grows Fastest
The Solvent-Based segment dominates the Conformal Coatings Market owing to its existing manufacturing process, its protective nature, and its acceptance by industries. The coatings offer uniformity in coating, efficient protection against moisture, and insulation in complex electronic assemblies. The compatibility of the coatings with existing spray and dip-coating manufacturing processes makes it possible to manufacture the coatings on an industrial scale in consumer electronics, automotive, and industrial applications. Moreover, the wide variety of formulations available, easy application process, and extensive industry experience make it easier for electronics manufacturers to adopt the coatings.
The UV-Cured segment is experiencing the fastest growth owing to the rising need for faster production cycles, increased efficiency in manufacturing, and shorter processing times. The rapid curing offered by the UV-curable coatings with ultraviolet radiation helps manufacturers enhance their throughput while reducing production constraints. Furthermore, the lower solvent content helps in lowering emissions of volatile organic compounds. In addition to that, the rise in use of automated coating lines and precision electronics manufacturing is boosting the demand for UV-cured coatings.
⮞In December 2025, the Japan Electronics and Information Technology Industries Association forecast that global electronics and IT production would climb 11% in 2025. Larger production runs reward cure technologies that raise line speed, which favors UV-cured systems.
By Application Method, Spray Dominates the Conformal Coatings Market and Chemical Vapor Deposition Grows Fastest
The Spray segment dominates the Conformal Coatings Market owing to its capability to provide even coverage of complex electronic assemblies such as circuit boards with densely packed components. This method allows flexibility in terms of coating thickness, applicability time, and coverage, which makes it applicable in the manufacture of high volume electronics. Besides, it can be used in automated dispensing and selective coating processes. Also, its wide adoption in consumer electronics, automotive electronics, and industrial products accounts for its dominance in the market.
The Chemical Vapor Deposition segment is witnessing rapid growth due to the increasing preference for protective coatings that offer highly uniform, thin, and pinhole free layers for miniaturized electronics. This technique provides efficient coverage of complicated geometries and areas difficult to reach, making it ideal for modern assemblies. Increasing adoption of high reliability electronics in sectors such as aerospace, defense, medical devices, and automobiles is driving demand for this coating process. Besides, superior protection against moisture and chemicals in tough operating conditions is motivating manufacturers to use vapor deposition techniques.
⮞In September 2025, the International Federation of Robotics reported that 542,000 industrial robots were installed worldwide during 2024. Wider robot deployment supports automated selective coating cells, which strengthens demand for programmable spray and dispensing methods.
By End Use, Consumer Electronics Dominates the Conformal Coatings Market and Aerospace and Defense Grows Fastest
The Consumer Electronics segment dominates the Conformal Coatings Market owing to the wide usage of printed circuit boards and electronic components in smartphones, laptops, televisions, wearable devices, and household appliances. The growing trend of miniaturization and increased density of components is creating the need for better protection from moisture, dust, and contamination. Moreover, increasing global production of internet-enabled devices, smart electronics, and advanced consumer goods is boosting the demand for conformal coatings. Manufacturers are using conformal coatings to enhance their product durability and reliability.
The Aerospace and Defense segment is experiencing the fastest growth Due to the increasing demand for highly reliable electronic systems that can function in harsh environmental conditions. Systems such as avionics, navigation equipment, communication systems, radar systems, and defense electronics need protection against humidity, temperature changes, vibrations, and corrosive environments. Increasing investments in military modernization, aircraft production, and advanced defense electronics are also driving the adoption of conformal coatings. Furthermore, high reliability and performance demands are pushing manufacturers to use conformal coating solutions for their mission-critical electronic assemblies.
⮞Airbus reported in January 2026 that it delivered 793 commercial aircraft in 2025. Each delivery carries large avionics and cabin electronics counts, which sustains qualified coating demand within aerospace and defense.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
58.00 |
|
North America |
United States |
86.00 |
|
Europe |
Germany |
26.00 |
|
Middle East & Africa |
Saudi Arabia |
33.84 |
|
Latin America |
Brazil |
46.37 |
North America Conformal Coatings Market Insights
North America hosts a dense customer base of aerospace primes, defense contractors, medical device manufacturers, and data center hardware builders that specify high-reliability coatings. Buyers in the United States and Canada weigh qualification records and traceability above unit price, which supports premium acrylic, urethane and parylene grades. Local chemical producers and application service providers maintain deep technical support that shortens approval timelines for new programs. Growing installations of artificial intelligence servers and networking equipment widen the coated assembly base further. Qualification-heavy buying keeps switching costs high for incumbent suppliers.
Policy is reshaping demand patterns. Incentives for onshore chip fabrication and tariffs on imported components encourage board assembly capacity near end customers, which adds coating line installations. Electric vehicle and energy storage programs also lift orders for silicone grades able to withstand repeated thermal cycling. Distributors and toll applicators are broadening service capacity in the Midwest and Southwest to serve these sites. Medical device clusters in Minnesota and Massachusetts add specialty parylene volumes, and defense procurement programs reward suppliers able to demonstrate secure and audited supply chains.
⮞In January 2026, a White House proclamation imposed a 25% ad valorem tariff on certain advanced computing chips under Section 232. Trade measures of this kind encourage onshore electronics assembly, which creates new coating requirements at North American production sites.
Europe Conformal Coatings Market Insights
Automotive, industrial automation and aerospace supply chains create steady demand for high-performance coatings in Europe. Plants in Germany, Italy and Central Europe coat engine controllers, sensor modules and drive electronics that must withstand salt, vibration and temperature extremes. Chemical compliance rules lead buyers to document the restricted-substance status of every formulation. Eastern European assembly hubs in Poland, Hungary and Czechia are adding coating lines as automotive suppliers localize production. Premium German and Swiss drive makers specify silicone and urethane films for long-life equipment.
Regulatory change defines the competitive agenda. Producers are reformulating around fluorinated polymers and solvent content, and several are introducing bio-based or PFAS-free grades well ahead of final rules. Electrified vehicles raise coated electronics content per car, while aerospace programs in France, the United Kingdom and Spain sustain specification-heavy orders. Equipment makers are responding with closed-loop dispensing systems that reduce material waste and solvent exposure for operators. Research programs on bio-derived resins are moving into pilot production at several chemical groups. These shifts are reshaping supplier shortlists at major original equipment manufacturers.
⮞In January 2026, the European Automobile Manufacturers' Association reported that 1,880,370 electric cars were newly registered in the European Union during 2025. Electrified vehicles carry power electronics and battery management boards that need dependable protective coatings.
Asia Pacific Conformal Coatings Market Insights
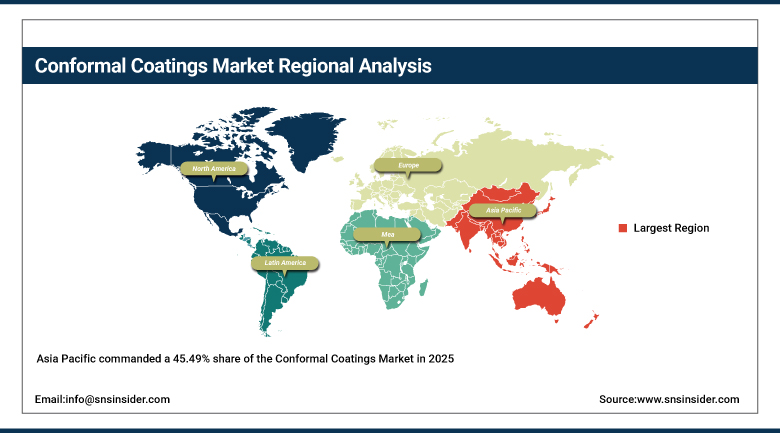
Asia Pacific commanded a 45.49% share of the Conformal Coatings Market in 2025, reflecting the concentration of printed circuit board fabrication, smartphone assembly and electric vehicle component production across China, Taiwan, South Korea, Japan and Southeast Asia. Contract manufacturers in the region run coatings at very high line speeds and favor UV-cured and selective spray systems that shorten cycle times. Local resin suppliers keep material costs competitive and nearby technical service teams speed up qualification of new formulations. Established clusters around Shenzhen and Suzhou continue to add inspection and dispensing capacity.
The region projected to expand at a CAGR of 7.98% through 2035. India is building component and assembly capacity under production-linked incentives while Vietnam and Malaysia attract relocated supply chains. China continues to scale automotive electronics and energy storage controls that call for robust board protection. Japan and South Korea contribute high-value automotive and semiconductor packaging applications that favor premium silicone and parylene grades. Rising adoption of automated lines across the region is shifting purchases toward faster-curing products.
⮞China's Ministry of Industry and Information Technology reported in December 2025 that value-added output of major electronic information manufacturers rose 10.9 percent in the first nine months of 2025. Sustained factory expansion of this kind enlarges the base of boards requiring protective coatings in the region.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa and Latin America Conformal Coatings Market Insights
Middle East and Africa is building an electronics assembly base through industrial diversification programs, notably in Saudi Arabia and the United Arab Emirates. Local assembly of computers, telecom equipment and consumer devices creates first-time demand for protective coatings, while oil and gas, utility and defense electronics require formulations resistant to heat, dust and salt-laden air. Global suppliers are expanding technical service capabilities to support new factories. Defense modernization programs in the Gulf raise requirements for locally supported electronics maintenance and repair, and mobile network expansion across Africa adds outdoor telecom hardware that needs humidity protection.
⮞In October 2025, Saudi Arabia's ALAT was reported to have a planned USD 100 Billion program that is driving electronics manufacturing in the Kingdom. New assembly lines of this scale create first-time demand for conformal coatings across the region.
Latin America ties its coating demand to electronics assembly and automotive production in Mexico and Brazil. Mexico's position as a major exporter of computers and automotive modules supports steady consumption on contract manufacturing lines serving North American customers, while Brazil's assembly of consumer devices and appliances sustains regional volumes. Import dependence for specialty resins keeps buyers price sensitive and favors acrylic and urethane grades. Auto parts plants in Mexico are adopting coatings for electric vehicle control modules as global manufacturers shift sourcing closer to the North American market.
⮞In April 2026, Banco Base reported that Mexico's computer exports grew nearly 145% in 2025 and overtook new automobiles as the leading export category. Assembly growth of this scale makes Latin America a rising source of new coated board volumes.
Market Dynamics
Growth Drivers: Rising Electronics Content in Vehicles and Devices Is Increasing Demand for Board-Level Protection
Miniaturization packs more functionality onto smaller boards, which narrows conductor spacing and heightens exposure to moisture-induced failure. Manufacturers therefore coat products once treated as low-risk, including appliances, e-bikes and smart home sensors. Higher component density also raises the cost of field failures, making coating an inexpensive insurance step within bill-of-materials planning. Consumer expectations for water resistance and durability, once confined to premium devices, are spreading to mid-range products. Procurement teams view the added step as inexpensive relative to warranty returns and recall exposure.
Vehicle electrification multiplies the number of coated modules per car. Driver assistance cameras, radar units, battery management systems and onboard chargers all operate under heat, vibration and condensation. Fifth generation telecom infrastructure and renewable energy inverters add outdoor electronics that must meet long service lives. Industrial automation and robotics push controller boards into washdown and dust-heavy factory floors where uncoated circuits fail early. Medical wearables and diagnostic equipment contribute a further layer of regulated demand. Together these programs widen the range of assemblies that carry a coating specification.
⮞The International Energy Agency noted in its Global EV Outlook 2026 that electric car sales exceeded 20 million units globally in 2025. Each electric vehicle carries more power and control boards than a combustion model, which lifts coating consumption.
Restraints: Tightening Fluoropolymer and Solvent Regulations Are Raising Reformulation and Compliance Costs
Environmental rules weigh on formulators and applicators alike. Limits on volatile organic compounds and restricted substances oblige solvent-based users to invest in abatement equipment or switch chemistries. Reformulation requires fresh testing and customer requalification that can run for many months. Smaller applicators struggle to fund new curing equipment, which slows conversion and keeps legacy products in service. Raw material price swings in acrylic monomers and silicone intermediates squeeze margins for formulators that sell under fixed annual contracts. Supply interruptions in specialty resins also lengthen lead times for customers.
Application complexity inflates processing cost. Achieving uniform thickness around tall components, masking connectors and inspecting under ultraviolet light demand trained staff and tightly controlled lines. Automated equipment and vapor deposition chambers require capital outlays that discourage smaller electronics makers. Uncertainty over fluorinated chemistries also complicates multi-year material choices for parylene users. Many assemblers lack in-house expertise to qualify coatings, so they depend on supplier training that adds cost and time. Inspection and rework of failed boards consume labor that thin-margin contract manufacturers prefer to avoid.
⮞In March 2026, the Committee for Risk Assessment of the European Chemicals Agency adopted its final opinion on the universal PFAS restriction with no grouped derogation for fluoropolymers. The outcome creates compliance uncertainty for parylene and fluorinated coating chemistries sold in Europe.
Opportunities: Solvent-Free and PFAS-Free Chemistries Are Opening New Sales Pools in Aerospace and Medical Electronics
Suppliers that offer faster cure and lower emissions in a single product are finding new growth in UV-cured and solvent-free coatings. Electronics makers pursuing carbon reduction targets increasingly request materials with documented emission savings. Bio-based content and PFAS-free chemistry create a premium tier where formulators can differentiate beyond price. Water-based platforms are attracting trials among appliance and lighting makers seeking low-odor alternatives. Suppliers with strong regulatory documentation can convert these trials into approved material listings faster than rivals at global brand owners.
Medical and aerospace electronics offer high-value openings for vapor deposited and selectively dispensed films. Implantable monitors, hearing devices, drones and satellite constellations require lightweight coatings that cover complex geometries without adding bulk. Suppliers pairing materials with application equipment, accredited service centers and engineering support can win multi-year program awards. Automotive radar and lidar sensors on advanced driver assistance platforms provide a further outlet for thin-film protection. Service providers operating accredited vapor deposition capacity can charge premium rates and build recurring contracts.
⮞The U.S. Food and Drug Administration's Center for Devices and Radiological Health released its 2025 annual report in May 2026 showing 124 novel devices authorized during the year. A pipeline of new electronic medical devices expands demand for biocompatible coatings and vapor deposited films.
Recent Developments:
-
June 2026, Henkel made Loctite Stycast UV 7998 available as a solvent-free UV and moisture dual-cure conformal coating with a UL 94 V-0 flame rating. The company claims up to 40% lower carbon dioxide emissions than solvent-based coatings. It offers assemblers a lower-emission route to faster curing.
-
March 2025, Specialty Coating Systems announced that its Singapore facility achieved Nadcap accreditation for conformal coating of printed board assemblies. The accreditation extends the company's qualified service footprint in Asia and supports aerospace customers that require audited processes.
-
October 2025, Dymax announced that it would exhibit its 9483 and 9451 UV-curable conformal coatings at SMTA International 2025 in Rosemont, Illinois. The showing places light-cure protective materials in front of electronics assemblers who are seeking higher line throughput.
-
September 2026, MacDermid Alpha Electronics Solutions introduced Electrolube UVFlex, a PFAS-free UV-curable coating with 25-30% bio-based content, ahead of Productronica India. The product responds to rising demand for fluorine-free protection with renewable content.
Conformal Coatings Market Key Players
-
Henkel
-
Dow
-
Chase Corporation (HumiSeal)
-
MacDermid Alpha Electronics Solutions (Electrolube)
-
Specialty Coating Systems
-
Dymax
-
Shin-Etsu Chemical
-
H.B. Fuller
-
ITW Chemtronics
-
MG Chemicals
-
KISCO
-
Panacol-Elosol
-
ELANTAS (ALTANA)
-
CHT Group
Conformal Coatings Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.20 Billion |
| Market Size by 2035 | USD 2.23 Billion |
| CAGR | CAGR of 6.41% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Acrylic, Silicone, Epoxy, and Others) • By Technology (Solvent-Based, Water-Based, UV-Cured, and Others) • By Application Method (Spray, Dipping, Brushing, Selective Dispensing, and Chemical Vapor Deposition) • By End Use (Consumer Electronics, Automotive, Aerospace and Defense, Medical, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Henkel, Dow, Chase Corporation (HumiSeal), MacDermid Alpha Electronics Solutions (Electrolube), Specialty Coating Systems, Dymax, Shin-Etsu Chemical, H.B. Fuller, ITW Chemtronics, MG Chemicals, KISCO, Panacol-Elosol, ELANTAS (ALTANA), CHT Group |

Frequently Asked Questions
Prominent participants in the Conformal Coatings Market include Henkel, Dow, Chase Corporation, Shin-Etsu Chemical and H.B. Fuller among others.
Key opportunities lie in UV-cured and PFAS-free chemistries, vapor deposition for medical and space electronics, and selective dispensing integrated with automated lines.
Rising electronics content in vehicles, aircraft and compact consumer devices is the major growth factor, because every additional circuit board requires protection against moisture, dust, chemicals and thermal stress.
The Acrylic segment dominated the Conformal Coatings Market in 2025 with approximately 40.75% share, owing to fast drying, easy rework and dependable moisture protection on general purpose boards.
Asia Pacific dominated the Conformal Coatings Market in 2025 with approximately 45.49% share, owing to the concentration of printed circuit board fabrication, smartphone assembly and vehicle electronics production in the region.
