
CSP MOSFET Market Report Scope & Overview:
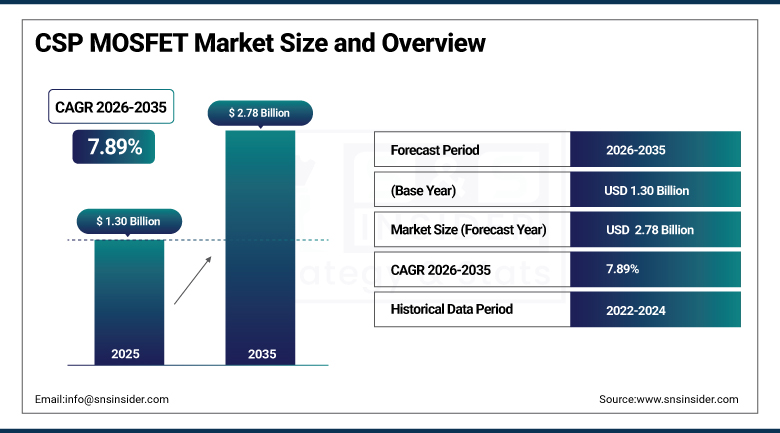
The CSP MOSFET Market was valued at USD 1.30 Billion in 2025 and is expected to reach USD 2.78 Billion by 2035, growing at a CAGR of 7.89% from 2026-2035.
Chip scale package metal-oxide-semiconductor field-effect transistors deliver ultra-low thermal impedance, reduced on-resistance, and superior thermal performance within a footprint barely larger than the semiconductor die itself, making them essential components across compact, energy-efficient power electronics. The market continues to be driven by increasing adoption of compact, energy-efficient power solutions across consumer electronics, electric automotive, and industrial automation applications, with the ongoing trend of miniaturisation in smartphones, IoT devices, and wearables continuing to demand power components that are simultaneously smaller and more efficient. Development of CSP MOSFET manufacturing methods leads to production of ultra-small, highly efficient devices necessary for use in modern electronics. Simultaneously, the fast growth of the automobile industry requires highly energy-efficient power components necessary for battery management systems and motor control circuits.
In October 2025, Infineon Technologies unveiled the CoolSiC MOSFET 750 V G2 series, boasting ultra-low on resistance designed exclusively for the automotive and industrial power electronics sectors. This development marks the ongoing efforts by the manufacturer towards developing power semiconductors that can keep up with the increasing thermal and efficiency demands of the latest generation of electric vehicles and industrial power electronics.
To Get more information On CSP MOSFET Market - Request Free Sample Report
CSP MOSFET Market Trends
- Rising adoption of chip scale packaging enabling ultra-thin, compact designs for mobile and wearable devices.
- Growing demand for high-voltage CSP MOSFETs supporting electric vehicle battery management and traction systems.
- Expanding integration of advanced thermal management architectures improving power density in compact packages.
- Increasing OEM specification of CSP MOSFETs across smart home devices and IoT-enabled electronics.
- Rising investment in wide-bandgap alternatives complementing traditional silicon-based CSP MOSFET portfolios.
U.S. CSP MOSFET Market Overview
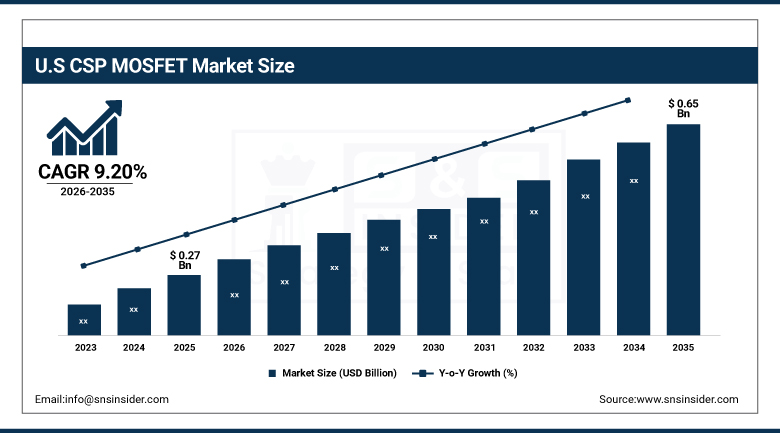
The U.S. CSP MOSFET Market was valued at USD 0.27 Billion in 2025 and is expected to reach USD 0.65 Billion by 2035, growing at a CAGR of 9.20% from 2026-2035.
The domestic market continues to benefit from strong electric vehicle development, renewable energy project investment, and accelerating data centre expansion, requiring increasingly compact, energy-efficient power switching components. Domestic power semiconductor manufacturers continue investing heavily in expanding wafer-level chip scale packaging capacity to meet surging demand from automotive customers pursuing battery electric and hybrid vehicle programs, alongside data centre operators seeking to reduce power conversion losses across increasingly dense AI computing infrastructure. Electronic component allocation constraints have periodically affected supply for automotive-grade power devices tied to EV electrification and advanced driver assistance systems, with capacity often prioritised toward long-term automotive supply agreements over spot-market availability. Continued domestic semiconductor incentive programs continue reinforcing the country's position as manufacturing base for advanced CSP MOSFET technology.
In 2026, Alpha and Omega Semiconductor expanded production and technology development at its 8-inch wafer fabrication facility in Hillsboro, Oregon. The U.S. facility supports the company’s proprietary power-semiconductor technologies, including MOSFET development and manufacturing. During the fiscal year, AOS introduced more than 70 new products, including 28 MOSFET products, targeting power supplies, industrial systems, communications equipment, and other high-efficiency applications. The Hillsboro operation strengthens AOS’s domestic semiconductor manufacturing capabilities while supporting new product development and supply for customers requiring advanced power-management devices in the U.S. market.
CSP MOSFET Market Segment Analysis
- By Product Type, the N-Channel segment dominated the market with a 52.60% share in 2025, while the Dual N-Channel segment is the fastest growing with a CAGR of 9.20% during 2026-2035.
- By Package Type, the WLCSP segment dominated the market with an estimated 42.30% share in 2025, while the Flip-Chip CSP segment is the fastest growing with a CAGR of approximately 9.80% during 2026-2035.
- By Application, the Consumer Electronics segment dominated the market with a 37.60% share in 2025, while the Automotive segment is the fastest growing with a CAGR of 9.60% during 2026-2035.
- By End-User, the OEMs segment dominated the market with a 79.60% share in 2025, and is also the fastest growing with a CAGR of 8.60% during 2026-2035.
- By Voltage Class, the Low-Voltage segment dominated the market with a 44.60% share in 2025, while the High-Voltage segment is the fastest growing with a CAGR of 9.40% during 2026-2035.
By Product Type, N-Channel Dominates the Market and Dual N-Channel Grows Fastest
N-Channel CSP MOSFETs dominated the market in 2025. This configuration continues to represent the established default choice across the majority of power switching applications, benefiting from superior electron mobility relative to P-Channel alternatives and a deeply established manufacturing and design ecosystem that continues to support reliable, cost-effective production at scale across virtually every major end-use application.
Dual N-Channel configurations are projected to be the fastest-growing product type over the forecast period. With an increasing demand for small footprint power management packages with multifunctional switching, dual die devices are gaining prominence owing to their ability to integrate all kinds of switching functions into one device. Dual N-Channel power management packages are therefore set for continued growth above market average compared to the rest of the mostly single channel packages.
By Package Type, WLCSP Dominates the Market and Flip-Chip CSP Grows Fastest
The WLCSP category held the major market share of the CSP MOSFET Market in 2025 owing to its extremely small footprint, minimal parasitics, and applicability in high density surface mount applications. The use of WLCSP will help in providing effective power management devices for smartphones, wearables, portable devices, etc. Shrinking size of electronic devices and increased need for higher power densities will drive its growth. Its ability to manufacture using wafer-level process helps in cost-effective and scalable production, thereby making it a strong contender in both consumer and automotive electronics segments.
The Flip-Chip CSP segment is expected to register the fastest growth in the CSP MOSFET Market during 2026-2035, driven by increasing demand for compact packages with improved electrical and thermal performance. The flip-chip interconnection approach allows for shortened interconnect distances and inductance, as well as enabling higher current densities and thermal dissipation. These attributes make the flip-chip technology useful for automotive electronics, computing, telecommunications, and power management. The continued semiconductor shrinkage, increased frequencies of switching action, and use of high density architectures are prompting the development of flip-chip CSPs into new application areas.
By Application, Consumer Electronics Dominates the Market and Automotive Grows Fastest
Consumer electronics dominated the market in 2025, including smartphones, wearables, and IoT devices. As these devices continue becoming smaller, their power components correspondingly need to be smaller yet more efficient, with ultra-low on-resistance requirements that CSP MOSFETs are specifically engineered to satisfy, sustaining this application's position as the largest category within the broader market.
Automotive is projected to be the fastest-growing application over the forecast period, supported by accelerated electric vehicle penetration and booming demand for improved power electronics in vehicles. CSP MOSFETs continue providing best-in-class performance, reduced power losses, and better thermal management within vital automotive systems including battery management, motor control, and onboard charging, positioning automotive for sustained above-market growth relative to the broader consumer-electronics-dominated application mix.
By End-User, OEMs Dominates the Market and Also Grows Fastest
OEMs dominated the CSP MOSFET market in 2025. Original equipment manufacturers still make up the vast majority of CSP MOSFET consumption due to the fact that they have to be involved with component specification and integration from the time of the original product development stage.
OEMs are also expected to grow fastest over the forecast period, fuelled by growing demand for high-performance, energy-efficient devices in applications spanning automotive, consumer electronics, and industrial automation. As product design cycles continue prioritising power density and efficiency from the outset, OEM specification activity continues to reinforce this end-user category's already dominant position even further relative to the aftermarket segment.
By Voltage Class, Low-Voltage Dominates the Market and High-Voltage Grows Fastest
Low-voltage CSP MOSFETs dominated the market in 2025. These devices continue to serve the substantial majority of consumer electronics and mobile device power management applications, where operating voltages typically remain well below 30 volts, sustaining low-voltage devices' position as the largest voltage class category across the broader CSP MOSFET market.
High-voltage CSP MOSFETs are projected to be the fastest-growing voltage class over the forecast period. Rising automotive and electric vehicle power electronics requirements continue to demand devices capable of reliably handling substantially higher voltages across battery management, traction inverter, and onboard charging applications, positioning high-voltage devices for sustained above-market growth relative to the broader low-voltage-dominated voltage class mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
Asia Pacific |
China |
39.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific CSP MOSFET Market Insights
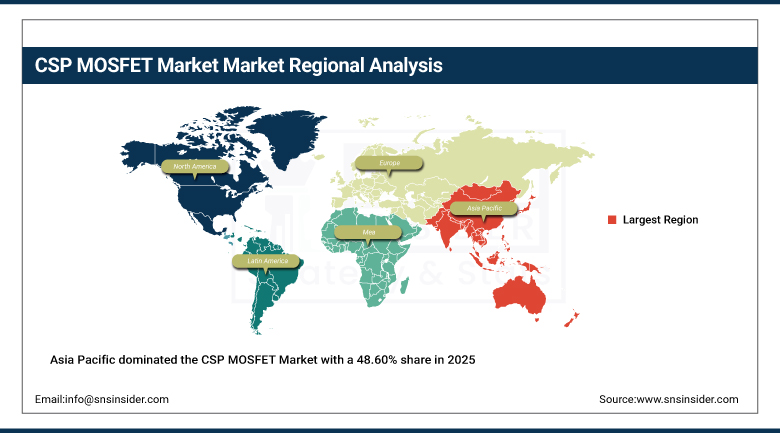
Asia Pacific dominated the CSP MOSFET Market with a 48.60% share in 2025, supported by its established semiconductor manufacturing ecosystem, high-volume electronics production, and expanding automotive electronics industry. China continues to be an important source of regional demand due to its large consumer electronics, industrial equipment, and electric vehicles manufacturing industry. Japan is a source of advanced semiconductor technologies, automotive electronics know-how, and manufacturing capability for power semiconductors.
South Korea’s electronics and semiconductor industry adds value to the region, while Taiwan’s semiconductor fabrication and package technologies add significant value as well. The region also has extensive supply chains, engineering capabilities, and investment in semiconductor manufacturing facilities. Rising adoption of compact power management solutions, increasing electronics miniaturization, and expanding electric mobility applications are expected to support sustained demand for CSP MOSFETs across Asia Pacific through the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America CSP MOSFET Market Insights
North America is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 9.20% during the forecast period. Rising demand continues to be driven by electric vehicle development, renewable energy projects, and accelerating data centre expansion, all of which require increasingly compact, energy-efficient power switching solutions.
The United States continues to anchor regional demand, supported by sustained domestic semiconductor manufacturing investment and expanding electric vehicle production. Canada contribute additional incremental regional demand as their own automotive and electronics manufacturing sectors continue to develop, positioning North America as the fastest-growing regional market through the forecast period.
Europe CSP MOSFET Market Insights
The region of Europe remains committed to the use of energy efficiency and automotive electrification which is helping in the continuous adoption of CSP MOSFET technologies. Germany remains a significant producer of automobiles in the region and is the primary driver of demand within the region owing to its technological advancements.
France, Italy, and other key automobile producers in Europe also remain key drivers of demand for the technology. Continued regional investment in semiconductor fabrication capability is expected to sustain steady growth across the broader European market through the forecast period.
MEA & Latin America CSP MOSFET Market Insights
The Middle East & Africa market remains comparatively modest, with growing industrial and renewable energy investment across the United Arab Emirates and Saudi Arabia gradually supporting regional demand for compact power semiconductor solutions.
Latin America's market is anchored by Brazil, where a growing domestic electronics and automotive manufacturing sector sustains steady demand. Mexico contributes further incremental growth as regional electronics assembly continues to expand alongside broader nearshoring-driven manufacturing investment.
Market Dynamics
Growth Drivers: Miniaturisation Demand and Electric Vehicle Adoption
The trend of miniaturisation in smartphones, IoT, and wearable devices stands as the primary growth driver, as power components need to be smaller, yet more efficient with ultra-low on-resistance to keep pace with continued device shrinkage across consumer electronics. Advancements in semiconductor fabrication techniques continue enabling production of increasingly ultra-compact, high-performance CSP MOSFETs essential for the latest electronic applications.
Rapid electrification of transportation represents a second major driver, as the global electric vehicle market continues expanding toward tens of millions of unit sales, with MOSFETs playing a crucial role in battery management systems, motor controllers, and onboard chargers. The increasing integration of smart home devices and IoT-enabled electronics continues to further reinforce sustained market demand across an expanding range of connected device categories.
Restraints: High Manufacturing Costs and Supply Chain Disruptions
High manufacturing costs remain a genuine restraint, as the semiconductor industry continues experiencing fluctuating raw material prices, particularly for silicon wafers, that continue to add cost pressure to CSP MOSFET production relative to less thermally demanding, larger-package alternatives.
Supply chain disruptions present a further restraint, as electronic component allocation constraints continue periodically affecting availability for automotive-grade power devices tied to EV electrification, with capacity often prioritised toward long-term supply agreements over spot-market buyers facing longer lead times.
Opportunities: Wide-Bandgap Integration and Data Centre Power System Expansion
Continued integration of wide-bandgap alternatives alongside traditional silicon-based CSP MOSFET portfolios represents a substantial opportunity, as manufacturers that can deliver genuinely complementary silicon carbide and gallium nitride offerings stand to capture demand from customers seeking the full spectrum of power semiconductor performance options.
Continued expansion into data centre power system applications offers a further avenue for growth, as manufacturers that can deliver compact, highly efficient power switching components suited to increasingly dense AI computing infrastructure are positioned to capture demand from an end-use category experiencing genuinely explosive growth in power conversion requirements.
Recent Developments:
- 2026: Infineon expanded its power-semiconductor portfolio for compact, high-efficiency applications, strengthening its position in miniaturized MOSFET solutions for automotive, industrial, computing, and consumer electronics.
- 2026: onsemi advanced its PowerTrench MOSFET portfolio, including wafer-level CSP devices designed to reduce footprint and conduction losses in space-constrained power-management applications.
- 2026: Vishay expanded its power semiconductor portfolio with compact MOSFET technologies targeting higher efficiency and miniaturization across automotive, industrial, computing, and consumer electronics applications.
CSP MOSFET Market Key Players are:
- Infineon Technologies AG
- onsemi (ON Semiconductor Corporation)
- Vishay Intertechnology, Inc.
- Texas Instruments Incorporated
- Toshiba Corporation
- Renesas Electronics Corporation
- Nexperia B.V.
- Diodes Incorporated
- Alpha and Omega Semiconductor Limited
- STMicroelectronics N.V.
- Rohm Co., Ltd.
- Semtech Corporation
- Microchip Technology Incorporated
- MagnaChip Semiconductor Corporation
- Nisshinbo Micro Devices Inc.
- Sanken Electric Co., Ltd.
- Nichicon Corporation
- Littelfuse, Inc.
- Power Integrations, Inc.
- China Wafer Level CSP Co., Ltd.
CSP MOSFET Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.30 Billion |
| Market Size by 2035 | USD 2.78 Billion |
| CAGR | CAGR of 7.89% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (N-Channel, P-Channel, Dual N-Channel, Dual P-Channel) • By Package Type (WLCSP, Flip-Chip CSP, Quad Flat No-Lead (QFN)-Based CSP, Ball Grid Array (BGA)-Based CSP, Other CSP Configurations) • By Application (Consumer Electronics, Automotive, Industrial, Telecommunications) • By End-User (OEMs, Aftermarket) • By Voltage Class (Low-Voltage (Below 30 V), Mid-Voltage (30-100 V), High-Voltage (Above 100 V)) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Infineon Technologies AG, onsemi (ON Semiconductor Corporation), Vishay Intertechnology, Inc., Texas Instruments Incorporated, Toshiba Corporation, Renesas Electronics Corporation, Nexperia B.V., Diodes Incorporated, Alpha and Omega Semiconductor Limited, STMicroelectronics N.V., Rohm Co., Ltd., Semtech Corporation, Microchip Technology Incorporated, MagnaChip Semiconductor Corporation, Nisshinbo Micro Devices Inc., Sanken Electric Co., Ltd., Nichicon Corporation, Littelfuse, Inc., Power Integrations, Inc., China Wafer Level CSP Co., Ltd. |
Frequently Asked Questions
Key players include Infineon Technologies AG, onsemi, Vishay Intertechnology, Inc., Texas Instruments Incorporated, and Toshiba Corporation, among other power semiconductor manufacturers.
Continued integration of wide-bandgap alternatives alongside traditional silicon-based portfolios and continued expansion into data centre power system applications represent the primary opportunities.
Growth is primarily driven by the trend of miniaturisation in smartphones, IoT, and wearable devices, combined with rapid electrification of transportation.
By Product Type, N-Channel dominated the market with a 52.60% share in 2025, reflecting its superior electron mobility and established manufacturing ecosystem.
Asia Pacific dominated the market with a 48.60% share in 2025, supported by the region's dominant power semiconductor manufacturing hub status.
