
Electronic Materials and Chemicals Market Report Scope & Overview:
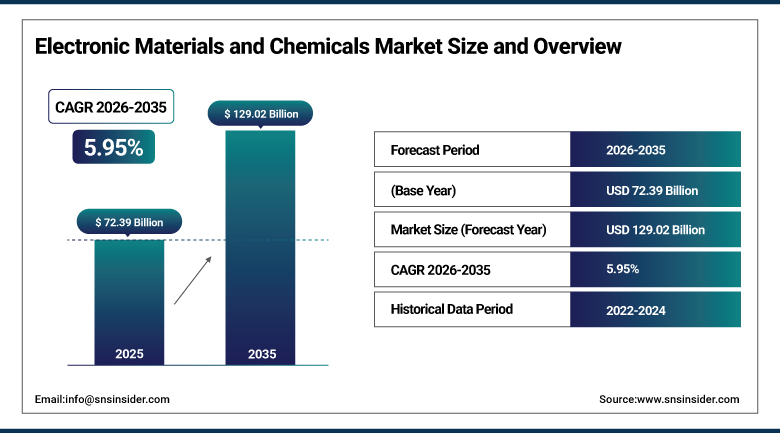
The Electronic Materials and Chemicals Market was valued at USD 72.39 Billion in 2025 and is expected to reach USD 129.02 Billion by 2035, growing at a CAGR of 5.95% from 2026-2035.
Growth in the Electronic Materials and Chemicals Market is mainly due to the growth in the production and usage of semiconductors in the world. Growing demand for electronics, advanced devices, and smaller components that require special materials for their manufacture, coating, and packaging drives the growth in the usage of electronic materials and chemicals. Electronic materials and chemicals include specialty gases, CMP slurries, photoresist chemicals, low-k dielectrics, wet chemicals, silicon wafers, and PCB laminates and play a key role in the production of semiconductors, printed circuit boards, and flat panel displays. Growth in technology related to the manufacture of semiconductors, miniaturization of electronic components, and growth in the production of semiconductors within countries drive demand for these products. Growth in applications such as artificial intelligence, high performance computing, electric vehicles, and 5G networks creates applications for electronic materials that ensure growth in the years ahead.
In April 2025, Linde announced an expansion of its industrial gas supply agreement with Samsung in South Korea, strengthening its long-term partnership with the semiconductor major. The contract covers delivery of high-purity gases essential for chip manufacturing processes, reflecting continued industrial gas supplier investment in long-term supply relationships with leading semiconductor manufacturers amid growing demand for electronic and specialty gases driven by advanced semiconductor production.
To Get more information Electronic Materials and Chemicals Market - Request Free Sample Report
Electronic Materials and Chemicals Market Trends
-
Growing demand for gaseous electronic materials driven by rising penetration in semiconductor and PCB manufacturing.
-
Rising investment in domestic semiconductor manufacturing capacity supporting regional supply chain resilience.
-
Continued development of PCB designs utilizing base material replacements such as BT-epoxy and polyamides.
-
Increasing adoption of high-purity chemical supply chains supporting increasingly complex chip architectures.
-
Expanding on-site bulk gas plant deployment reducing logistics costs and supply-disruption risk for fabs.
U.S. Electronic Materials and Chemicals Market Outlook
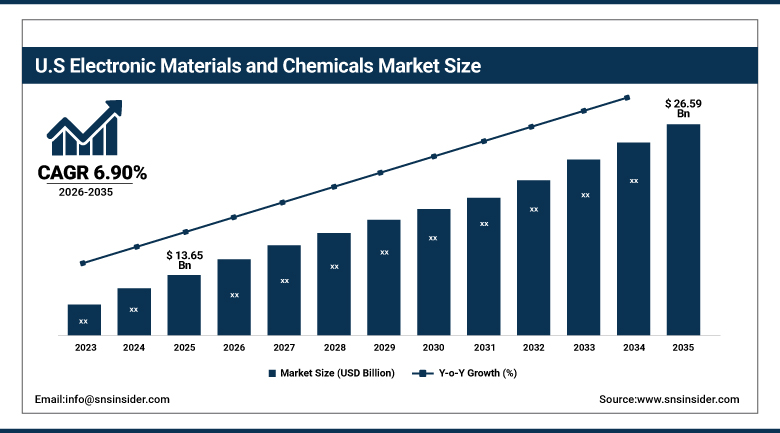
The U.S. Electronic Materials and Chemicals Market was valued at USD 13.65 Billion in 2025 and is expected to reach USD 26.59 Billion by 2035, growing at a CAGR of 6.90% from 2026-2035.
The U.S. Electronic Materials and Chemicals Market growth continues to be reinforced by rising investments in domestic semiconductor manufacturing, growing wafer fabrication capacity, and the country's concentration of leading electronic materials suppliers. Domestic demand also benefits from continued government incentives supporting semiconductor supply-chain resilience, which continue to attract new fabrication and materials production investment to the United States. Continued growth in artificial intelligence and high-performance computing chip production further supports demand for high-purity electronic materials capable of meeting the increasingly stringent specifications of advanced logic and memory manufacturing.
Entegris, a leading U.S.-based supplier of advanced materials and process solutions for the semiconductor industry, continues to expand its comprehensive electronic materials portfolio to serve customers pursuing smaller device geometries and new architectures requiring innovative materials and increasingly stringent purity standards. The company's continued investment in materials science and purity capabilities reflects sustained domestic supplier focus on accelerating time to yield for semiconductor manufacturers navigating industry forecasts projecting global semiconductor sales approaching USD 1.6 trillion by 2030.
Electronic Materials and Chemicals Market Segment Analysis
-
By Product Type, the Solid segment dominated the Electronic Materials and Chemicals Market with approximately 54.00% share in 2025, while the Gaseous segment is the fastest growing with a CAGR of approximately 6.90%.
-
By Application, the Silicon Wafers segment dominated the Electronic Materials and Chemicals Market with approximately 28.50% share in 2025, while the Photoresists segment is the fastest growing with a CAGR of approximately 7.20%.
-
By End-Use, the Semiconductors & Integrated Circuits segment dominated the Electronic Materials and Chemicals Market with approximately 68.50% share in 2025, while the Printed Circuit Boards segment is the fastest growing with a CAGR of approximately 6.80%.
By Product Type, Solid dominates and Gaseous grows fastest
The Solid segment continues to lead the Electronic Materials and Chemicals Market by product type, a position rooted in the sheer volume of silicon wafers, substrates, and other solid inputs consumed in manufacturing computers, laptops, and smartphones. Renewable energy technologies are adding further momentum: solar panels and electric vehicles depend on electronic components built from specialized solid materials, and this expanding end-use base is pushing manufacturers to invest heavily in research and development aimed at more effective, more sustainable formulations. The segment's breadth also works in its favor, since solid materials span everything from substrates and laminates to bonding wires and encapsulants, giving suppliers multiple entry points into a single customer's fabrication process rather than a single narrow product line.
Gaseous materials, by contrast, are the segment to watch for growth, propelled by their rising penetration across semiconductor and printed circuit board manufacturing processes that demand increasingly pure specialty gases. Suppliers in this category are concentrating on high-purity gas delivery systems built for advanced fabrication, a focus that should serve them well as chipmakers keep pushing toward smaller process geometries and correspondingly tighter gas purity specifications. On-site bulk gas plants, built directly adjacent to fabrication facilities, are becoming an increasingly common way for suppliers to guarantee reliable, contamination-free delivery while cutting the logistics risk that comes with transporting specialty gases over long distances, a shift that continues to strengthen supplier relationships with major foundries.
By Application, Silicon Wafers dominates and Photoresists grows fastest
Silicon Wafers hold the largest application share in the Electronic Materials and Chemicals Market, owing to their role as the foundational substrate beneath nearly every semiconductor device manufactured today. Sustained growth across global semiconductor production keeps this segment well supported, since expanding chip output at both leading-edge and mature process nodes translates directly into rising demand for high-purity wafer material. Wafer suppliers also benefit from long qualification cycles that, once a customer relationship is established, tend to produce years of repeat business, since switching wafer suppliers mid-production run carries real technical and cost risk for chipmakers.
Photoresists are on track to outpace every other application segment, a trajectory tied to increasingly complex chip architectures that call for advanced photolithography materials capable of resolving ever-finer circuit patterns. Suppliers are directing development toward next-generation photoresist chemistries suited to extreme ultraviolet and other cutting-edge lithography processes, positioning themselves to benefit as chipmakers advance toward smaller process nodes. Because each new process node effectively demands a new generation of photoresist chemistry, suppliers who can move fastest from lab-validated formulations to qualified, production-ready material tend to capture outsized share of this fast-moving application category relative to slower-moving competitors.
By End-Use, Semiconductors & Integrated Circuits dominates and Printed Circuit Boards grows fastest
Semiconductors & Integrated Circuits remain the anchor end-use segment for the Electronic Materials and Chemicals Market, a reflection of the sector's standing as the primary consumer of specialty electronic materials across wafer fabrication, packaging, and testing. Sustained expansion of global semiconductor manufacturing capacity, across both established and emerging production regions, continues to underpin this segment's dominant position. New fabrication facilities coming online across multiple countries each represent years of forward material demand once construction wraps and production ramps toward full capacity, giving suppliers serving this end-use category unusually strong visibility into future order volumes.
Printed Circuit Boards are the fastest-growing end-use category, fueled by rising consumption of electronic chemicals and materials as digitalization accelerates across both developing and developed economies. PCB manufacturers are pursuing designs that maximize material utilization and minimize cost, including replacing conventional base materials with BT-epoxy and polyamides, a shift that should support continued momentum as connected-device proliferation keeps expanding. Growing demand for multilayer and high-density interconnect boards, driven by smartphones, servers, and automotive electronics alike, is adding further pressure on PCB manufacturers to source increasingly specialized laminates and etching chemicals capable of supporting finer circuit traces.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
Taiwan |
48.60% |
|
North America |
United States |
88.50% |
|
Europe |
Germany |
34.60% |
|
Latin America |
Brazil |
38.60% |
|
Middle East & Africa |
Israel |
41.80% |
Asia Pacific Electronic Materials and Chemicals Market Insights
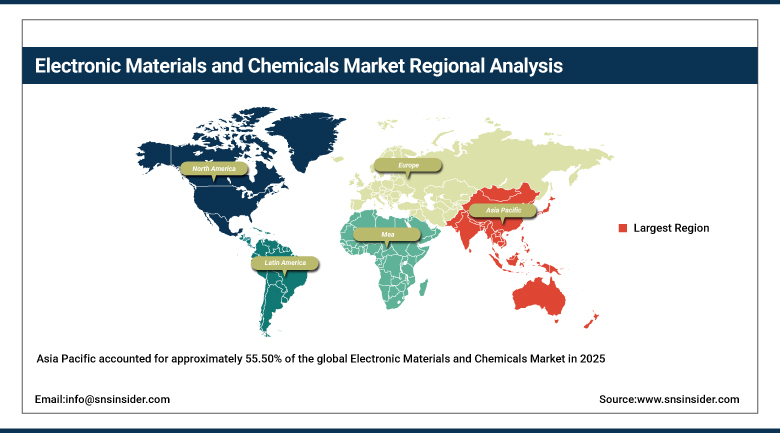
Asia Pacific accounted for approximately 55.50% of the global Electronic Materials and Chemicals Market in 2025, supported by the region's concentration of leading semiconductor foundries, wafer fabrication facilities, and electronic materials suppliers. Taiwan represents a particularly significant contributor within the region, anchored by its leading advanced logic foundry base and dense network of materials suppliers serving the semiconductor manufacturing ecosystem. The island's foundries alone consume a substantial share of the world's high-purity photoresist, specialty gas, and CMP slurry output, making Taiwan's own capacity expansion plans a real bellwether for global electronic materials demand.
China and South Korea contribute substantial additional regional demand, supported by expanding domestic semiconductor manufacturing capacity and memory production. Japan's established electronic materials manufacturing expertise further reinforces the region's overall supply chain depth, supporting Asia Pacific's position as the largest global market for electronic materials and chemicals. South Korea's dominance in memory chip production in particular keeps demand for etching chemicals and specialty gases running at a scale few other single-country markets can match, while China's own push toward domestic materials self-sufficiency continues to reshape sourcing patterns across the broader regional supply chain.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Electronic Materials and Chemicals Market Insights
North America is projected to expand at the fastest CAGR across the Electronic Materials and Chemicals Market during the 2026-2035 forecast period, driven by expansion of semiconductor fabrication capacity, growth in consumer electronics production, and rising investments in domestic wafer manufacturing. The United States shapes regional demand dynamics through its concentration of leading electronic materials suppliers and sustained government incentives supporting semiconductor supply-chain resilience. Federal funding tied to domestic chip manufacturing legislation has accelerated construction of new fabrication facilities across several states, each of which represents a fresh, long-term customer for electronic materials suppliers once production begins.
Canada contributes additional regional demand through its participation in North American semiconductor and electronics supply chains. Continued domestic investment in advanced logic and memory chip production further reinforces North America's position as the fastest-growing regional market for electronic materials and chemicals. As more fabrication capacity comes online across the region over the coming years, suppliers with existing U.S. manufacturing footprints are generally better positioned than import-dependent competitors to win the accompanying materials contracts, given the premium customers increasingly place on shorter, more resilient supply chains.
Europe Electronic Materials and Chemicals Market Insights
Europe represents a significant regional market for electronic materials and chemicals, anchored by Germany's substantial semiconductor and automotive electronics manufacturing base and its concentration of major specialty chemical suppliers. Germany's share within the European market reflects both its advanced logic semiconductor investment activity and its home-market presence of major electronic materials developers. The country's deep automotive electronics sector adds a layer of demand less exposed to consumer electronics cycles, since automotive-grade semiconductor components typically require longer qualification periods and more conservative material specifications than consumer devices.
France and the Netherlands contribute additional regional demand, supported by established semiconductor manufacturing and equipment supply chains. Continued European Chips Act investment aimed at expanding the region's semiconductor manufacturing footprint supports steady regional demand for electronic materials and chemicals. The Netherlands' position as home to leading lithography equipment manufacturers also gives the region an unusual advantage: equipment and materials suppliers often collaborate closely on process development, which can accelerate qualification of new electronic materials for use alongside next-generation lithography tools. Both countries also host a meaningful base of specialty equipment manufacturers whose local presence continues to support close collaboration with materials suppliers on next-generation formulation development.
MEA & Latin America Electronic Materials and Chemicals Market Insights
Latin America's Electronic Materials and Chemicals Market is led by Brazil, which accounts for the majority of regional demand on the strength of its growing electronics assembly and manufacturing sector. Gradual growth in domestic electronics production continues to support steady regional market development. Mexico is also contributing incremental demand as nearshoring-driven investment continues to draw electronics assembly operations closer to North American supply chains, a trend that should gradually expand the region's overall materials consumption over the coming years even from a currently modest base.
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in markets such as Israel, which maintains an established semiconductor research and development ecosystem supporting advanced logic and specialty device production. Gulf Cooperation Council markets contribute additional regional demand through growing investment in electronics manufacturing and technology infrastructure. Israel's deep bench of semiconductor design talent, paired with a growing number of specialty fabrication facilities, continues to draw materials suppliers eager to establish an early presence in one of the region's most technically sophisticated markets. Growing government interest across several Gulf states in diversifying beyond oil-driven economies is also gradually opening the door to early-stage electronics manufacturing investment, a trend that could meaningfully expand the region's materials demand over the coming decade.
Market Dynamics
Growth Drivers: Semiconductor Production Growth and Manufacturing Capacity Expansion
Rising demand for advanced electronics, high-performance devices, and miniaturized components is the main force pushing the Electronic Materials and Chemicals Market forward, since the global production and consumption of semiconductors continues to climb and each new generation of chips requires specialized materials for fabrication, coating, and packaging. Rapid technological advancement in semiconductor manufacturing, combined with growing adoption of miniaturized, high-density electronic components across consumer and industrial applications, keeps reinforcing this underlying demand. Every new smartphone generation, data center buildout, or electric vehicle platform effectively locks in years of forward material demand, since each requires chips built to specifications that didn't exist in the prior generation.
A second major driver comes from growing investments in domestic semiconductor manufacturing capacity, as governments and private investors keep funding new fabrication facilities to strengthen regional supply-chain resilience. Rising consumption of electronic chemicals and materials in printed circuit boards, tied to increasing demand for digitalization across both developing and developed countries, adds further support to this growth trajectory. Governments in multiple regions now treat domestic chip manufacturing as a matter of national economic security rather than a purely commercial decision, and that policy shift has translated into subsidy programs that are directly accelerating new fab construction and, with it, materials demand.
Restraints: Semiconductor Industry Cyclicality and High-Purity Manufacturing Complexity
The semiconductor industry's inherent cyclicality poses a real challenge for suppliers in this market, since industry downturns can quickly translate into decreased demand for electronic chemicals and materials, forcing strategic adaptations that not every supplier is equipped to make quickly. Weathering these swings tends to require sustained investment in research and development aimed at innovative, high-performance, cost-effective solutions that help suppliers hold onto their competitive edge through the industry's down cycles. Smaller suppliers without diversified end-use exposure are especially vulnerable during downturns, since they often lack the balance sheet to sustain R&D spending through a prolonged slump in chip demand.
Manufacturing increasingly high-purity electronic materials for advanced semiconductor process nodes is technically demanding work, and that complexity adds real development cost relative to conventional chemical manufacturing. Ongoing volatility in raw material and specialty gas supply chains compounds the problem, making long-term manufacturing cost and pricing planning harder to pin down across the industry. Achieving the parts-per-billion purity levels leading-edge fabrication now requires often means rebuilding entire production processes from scratch rather than simply refining an existing one, a capital commitment that keeps raising the bar for new entrants hoping to compete at the industry's technical frontier.
Opportunities: Emerging Technology Applications and Sustainable Formulation Development
Emerging technology applications such as flexible electronics and energy storage offer suppliers a meaningful path to diversify beyond the semiconductor industry's cyclical demand swings, and continued exploration of these categories represents a substantial growth opportunity for the Electronic Materials and Chemicals Market. Suppliers able to demonstrate validated, high-performance materials suited to these newer applications stand to capture real share as these technology categories mature. Flexible display and wearable electronics manufacturers in particular are actively searching for material partners willing to co-develop novel formulations, an opening that rewards suppliers with real materials science depth over those competing purely on production scale.
Sustainable chemical formulation development offers a longer-term opportunity for suppliers looking to differentiate their portfolios through reduced environmental impact alongside the performance requirements customers already expect. Semiconductor manufacturers are increasingly weighing supply chain sustainability alongside technical performance when choosing suppliers, and those with established sustainable materials development capabilities are well placed to capture a disproportionate share of this emerging demand. Several major chipmakers have already begun formally scoring supplier sustainability credentials as part of procurement decisions, turning what was once a marketing consideration into a real factor in which materials suppliers win new fabrication contracts.
Recent Developments:
-
In April 2025, Linde announced an expansion of its industrial gas supply agreement with Samsung in South Korea, covering delivery of high-purity gases essential for chip manufacturing processes to support growing semiconductor production demand.
-
FUJIFILM Corporation completed a USD 700 million acquisition strengthening its semiconductor-materials business and expanding its global footprint in electronic chemicals manufacturing to better serve growing demand from semiconductor fabricators.
Electronic Materials and Chemicals Market Key Players
-
Air Products and Chemicals, Inc.
-
Air Liquide S.A.
-
Linde plc
-
Honeywell International Inc.
-
BASF SE
-
Entegris, Inc.
-
Ashland Inc.
-
Fujifilm Electronic Materials
-
Kanto Chemical Co., Inc.
-
Tokyo Ohka Kogyo Co., Ltd.
-
JSR Corporation
-
DuPont de Nemours, Inc.
-
Dow Inc.
-
Shin-Etsu Chemical Co., Ltd.
-
Sumitomo Chemical Co., Ltd.
-
Mitsubishi Chemical Group Corporation
-
Eastman Chemical Company
-
Transene Company, Inc.
-
Merck KGaA
-
Solvay S.A.
Electronic Materials and Chemicals Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 72.39 Billion |
| Market Size by 2035 | USD 129.02 Billion |
| CAGR | CAGR of 5.95% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Solid, Liquid, and Gaseous) • by Application (Silicon Wafers, PCB Laminates, Specialty Gases, Wet Chemicals & Solvents, Photoresists, Low-k Dielectrics, and CMP Slurries) • by End-Use (Semiconductors & Integrated Circuits, Printed Circuit Boards, Flat Panel Displays, and Photovoltaics) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Air Products and Chemicals, Inc., Air Liquide S.A., Linde plc, Honeywell International Inc., BASF SE, Entegris, Inc., Ashland Inc., Fujifilm Electronic Materials, Kanto Chemical Co., Inc., Tokyo Ohka Kogyo Co., Ltd., JSR Corporation, DuPont de Nemours, Inc., Dow Inc., Shin-Etsu Chemical Co., Ltd., Sumitomo Chemical Co., Ltd., Mitsubishi Chemical Group Corporation, Eastman Chemical Company, Transene Company, Inc., Merck KGaA, Solvay S.A. |
Frequently Asked Questions
Leading companies in the Electronic Materials and Chemicals Market include Air Products and Chemicals, Air Liquide, Linde, Honeywell International, and BASF, among others.
Key opportunities include continued exploration of flexible electronics and energy storage applications, and rising focus on sustainable chemical formulation development.
Rising production and consumption of semiconductors globally, combined with growing investments in domestic semiconductor manufacturing capacity, is the major factor driving market growth.
The Solid segment dominated the Electronic Materials and Chemicals Market with approximately 54.00% share in 2025.
Asia Pacific dominated the Electronic Materials and Chemicals Market in 2025 with approximately 55.50% share, supported by the region's concentration of leading semiconductor foundries, led by Taiwan.
