
Flexible Electronics Market Report Scope & Overview:
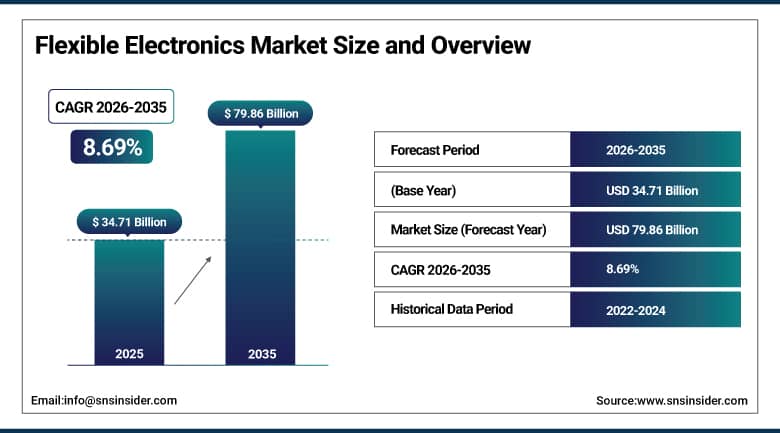
The Flexible Electronics Market was valued at USD 34.71 Billion in 2025 and is expected to reach USD 79.86 Billion by 2035, growing at a CAGR of 8.69% from 2026-2035.
The Flexible Electronics Market covers electronic components and systems built on bendable, foldable, stretchable or rollable substrates such as plastic films, metal foils, thin glass and textiles. Products include flexible displays, thin batteries, printed and stretchable sensors, memory, antennas and circuits that conform to curved surfaces or move with the human body. Foldable phones, smartwatches, medical patches, vehicle interiors and industrial monitoring all draw on these technologies. Roll-to-roll printing, advances in organic and thin-film materials and falling production costs are widening the range of devices that can be built flexibly, supporting growth through 2035. Suppliers with proven reliability data and scalable printing lines are best placed to benefit.
⮞The Global Electronics Association reported on 25 August 2026 that North American printed circuit board shipments rose 14.5% year on year in July 2026, while bookings increased 62.0%.
To Get More Information On Flexible Electronics Market - Request Free Sample Report
Flexible Electronics Market Trends
-
Foldable, slidable and rollable displays are moving from premium phones into tablets, laptops and vehicle dashboards as crease visibility and brightness at the hinge improve.
-
Printed, lithium-free thin-film batteries are being embedded in smart cards, labels and sensor patches that must stay below one millimeter in thickness.
-
Stretchable silicone and textile sensors are entering wearables, automotive interiors and robotic skins that need to track pressure or strain across large surfaces.
-
Roll-to-roll and additive manufacturing are shifting production from batch lithography to continuous printing, which lowers the cost per square meter.
-
Hybrid designs that combine printed circuits with thin silicon chips are appearing in medical patches, smart packaging and defense electronics.
U.S. Flexible Electronics Market Outlook
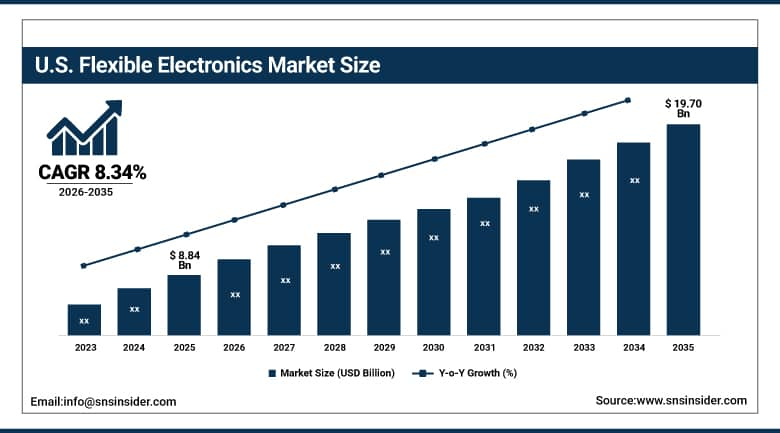
The U.S. Flexible Electronics Market was valued at USD 8.84 Billion in 2025 and is expected to reach USD 19.70 Billion by 2035, growing at a CAGR of 8.34% from 2026-2035.
The U.S. Flexible Electronics Market is the largest national market in North America, supported by consumer technology brands, medical device developers, defense laboratories and a growing base of printed electronics start-ups. Government-funded programs in flexible hybrid electronics bring universities, manufacturers and the military together to build bendable sensors and circuits for soldiers, aircraft and health monitoring. Smartwatch ownership is already high, and regulators have loosened rules for wellness wearables. These conditions sustain steady demand for thin batteries, stretchable sensors and flexible interconnects through 2035. Venture funding for wearable health start-ups adds further momentum. Federal research laboratories also contribute prototypes.
⮞The Pew Research Center reported on 17 June 2026 that 37% of U.S. adults own a smartwatch, including 44% of those aged 18 to 29 and 44% of those aged 30 to 49.
Flexible Electronics Market Segment Analysis
-
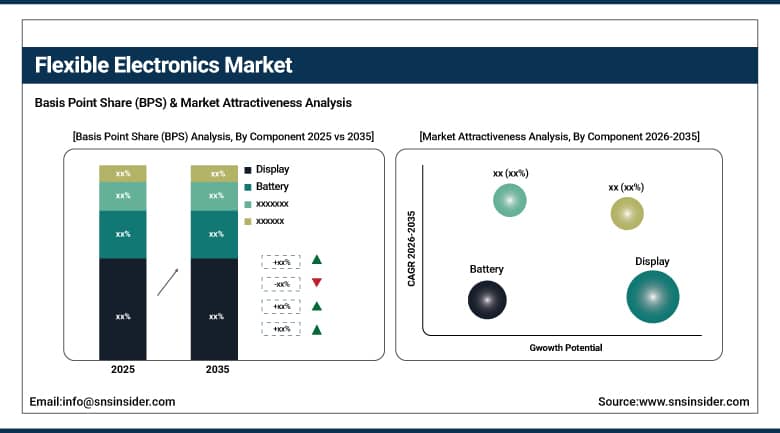
By Component, the Display segment dominated the Flexible Electronics Market with approximately 50.67% share in 2025, while the Battery segment is the fastest growing with a CAGR of approximately 11.47%.
-
By Application, the Consumer Electronics segment dominated the Flexible Electronics Market with approximately 58.42% share in 2025, while the Healthcare segment is the fastest growing with a CAGR of approximately 12.64%.
-
By Material, the Plastic Substrates segment dominated the Flexible Electronics Market with approximately 60.38% share in 2025, while the Metal Foils segment is the fastest growing with a CAGR of approximately 9.12%.
-
By Technology, the Printed Electronics segment dominated the Flexible Electronics Market with approximately 57.86% share in 2025, while the Organic Electronics segment is the fastest growing with a CAGR of approximately 11.37%.
By Component, Display Dominates the Flexible Electronics Market and Battery Grows Fastest
Displays hold approximately 50.67% of the Flexible Electronics Market in 2025 because flexible OLED panels already ship in very large numbers inside foldable phones, curved smartphones, smartwatches, televisions and automotive clusters. Panel makers have invested heavily in plastic-substrate production lines, and each new generation improves brightness at the fold, durability and thickness. Foldable and slidable formats are extending into tablets, notebooks and vehicle screens, which keeps the display segment far ahead of other components in revenue. Suppliers also benefit from long-term supply agreements with phone makers, which support continued investment in capacity. Continuing improvements in materials and processes support this position.
Batteries are the fastest growing component, with a CAGR of approximately 11.47% during 2026-2035. Thin printed and lithium-free cells below one millimeter thick power smart labels, medical patches, wearables and wireless sensors that cannot accommodate coin cells. Roll-to-roll production lowers unit prices, and bendable form factors let designers integrate energy storage directly into clothing, packaging and curved device housings. Rising use of internet-connected sensors in logistics and healthcare adds many new low-power devices that need slim power sources. Smart cards and logistics tags are further high-volume users of such cells. Wireless earbuds and hearing devices add further volume.
⮞The GSMA reported in February 2026 that the world had 5.8 billion unique mobile subscribers in 2025, about 70% of the global population, and 8.8 billion wireless connections.
By Application, Consumer Electronics Dominates the Flexible Electronics Market and Healthcare Grows Fastest
Consumer electronics account for approximately 58.42% of the market in 2025, led by foldable smartphones, smartwatches, fitness bands, earbuds, curved televisions and augmented reality eyewear. These products reward thin, light and bendable parts that fit awkward shapes, and large brands are willing to pay for the differentiation. Annual product cycles ensure steady demand for new flexible displays, batteries and interconnects, while the scale of production helps bring costs down for other users of the same technologies. Retail availability and quick replacement cycles reinforce this lead. Continuing improvements in materials and processes support this position.
Healthcare is the fastest growing application, with a CAGR of approximately 12.64% through 2035. Skin-conforming patches monitor heart rhythm, muscle activity, glucose indicators and sweat chemistry, and printed sensors are built into bandages, smart implants and diagnostic strips. Hospitals and consumers want continuous, comfortable monitoring, and flexible devices make that possible. Looser regulatory treatment of wellness wearables is also speeding product launches. Dermatology and rehabilitation clinics are testing adhesive sensor arrays, while insurers explore remote monitoring programs that reduce hospital visits, which together create a durable pipeline of clinical pilots.
⮞The U.S. Food and Drug Administration updated its General Wellness and Clinical Decision Support guidances on 6 January 2026, allowing non-invasive wearables that estimate measures such as blood pressure to be sold as wellness products if no disease claims are made.
By Material, Plastic Substrates Dominate the Flexible Electronics Market and Metal Foils Grow Fastest
Plastic substrates account for approximately 60.38% of the market in 2025 because polyimide, polyethylene terephthalate and polyethylene naphthalate films combine low weight, mechanical flexibility, chemical stability and compatibility with roll-to-roll processing. Polyimide tolerates the temperatures of display and circuit fabrication, while cheaper films serve printed antennas, labels and sensors. A broad supply chain of film producers, coaters and equipment makers supports consistent quality and attractive pricing for high-volume products. Suppliers are also developing thinner, colorless variants to support transparent and under-panel uses, which broadens the reach of plastic films into new product categories. Continuing improvements in materials and processes support this position.
Metal foils are the fastest growing material, at a CAGR of approximately 9.12% during 2026-2035. Stainless steel, aluminum and copper foils withstand high processing temperatures, offer excellent barrier properties against moisture and oxygen, and dissipate heat well. They are used in flexible solar modules, battery current collectors, lighting and rugged displays. Growing interest in durable, bendable products for automotive, energy and industrial settings is raising their share. Roll-to-roll metal foil processing lowers costs and supports large-area production, helping the segment gain ground over time.
⮞The Taiwan Printed Circuit Association reported in June 2026 that flexible boards made up 20.0% of the product mix of Taiwan-based printed circuit board makers in the first quarter of 2026.
By Technology, Printed Electronics Dominates the Flexible Electronics Market and Organic Electronics Grows Fastest
Printed electronics hold approximately 57.86% of the market in 2025 because screen, inkjet, gravure and flexographic printing deposit conductive, semiconducting and dielectric inks on flexible films at low cost and high speed. The method suits sensors, antennas, heaters, batteries, touch layers and simple circuits, and it avoids many of the chemicals and energy demands of lithography. Manufacturers can switch designs quickly, which suits short product runs and customized devices. Established ink suppliers and equipment makers provide a mature support base for new entrants, which shortens development time. Continuing improvements in materials and processes support this position. Lower tooling costs encourage frequent redesigns.
Organic electronics are the fastest growing technology, with a CAGR of approximately 11.37% during 2026-2035. Organic light-emitting diodes, organic photovoltaics and organic transistors can be processed at low temperatures on plastic and offer tunable color, light weight and large-area coverage. Display makers continue to improve lifetimes and efficiency, while developers of sensors and lighting explore new molecules. Advances in encapsulation and materials purity are widening commercial use. Research collaborations between universities and display makers continue to produce new emitter materials, supporting long-term growth for this technology.
⮞SEMI’s FlexTech organization issued a call for flexible hybrid electronics proposals on 19 May 2026, with full proposals due on 6 July 2026.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
79.26% |
|
Asia Pacific |
China |
36.42% |
|
Europe |
Germany |
26.91% |
|
Latin America |
Brazil |
44.35% |
|
Middle East & Africa |
United Arab Emirates |
22.46% |
North America Flexible Electronics Market Insights
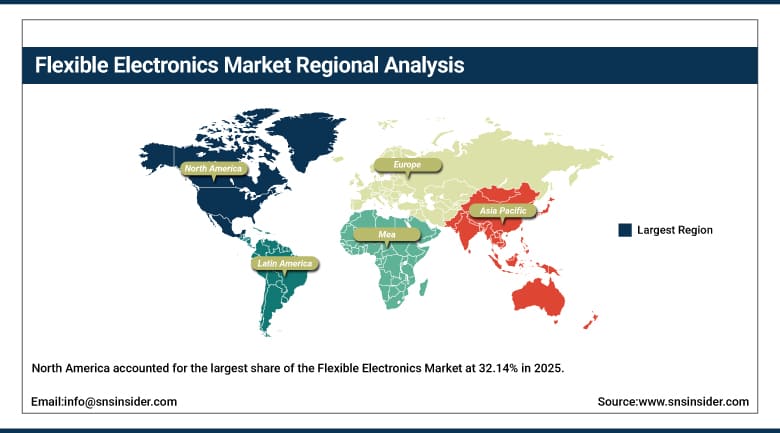
North America accounted for the largest share of the Flexible Electronics Market at 32.14% in 2025, with the United States contributing about 79.26% of regional demand and Canada the balance. The region combines leading consumer technology brands, strong medical device and defense research, and a community of start-ups that develop printed sensors, thin batteries and stretchable circuits. Public funding for flexible hybrid electronics and university pilot lines supports commercialization. High consumer adoption of wearables creates a ready market for new form factors. Local suppliers and distributors strengthen regional access to components.
Canada adds demand through medical technology and university spinoffs, while Mexico, which is part of Latin America, supplies contract assembly for devices sold in the United States. Healthcare providers and insurers are testing remote monitoring patches, and automotive suppliers in the Midwest are adding flexible sensors and lighting to vehicles. Most manufacturing of displays occurs in Asia, so regional strength is concentrated on design, materials, sensors, packaging and system integration. Venture-backed firms in California, Massachusetts and Texas continue to raise capital for printed sensors, which reinforces the region's innovation lead.
⮞The Semiconductor Industry Association reported on 6 August 2026 that global semiconductor sales in June 2026 were up 123.6% year on year.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Flexible Electronics Market Insights
Asia Pacific held approximately 29.63% of the Flexible Electronics Market in 2025 and is the fastest growing region, with a CAGR of 10.21% during 2026-2035. South Korea, China, Japan and Taiwan host the world’s leading flexible display, printed circuit and materials producers, and they supply nearly every global electronics brand. Large capital investment in new panel lines, a deep supplier network and strong consumer demand for foldable phones and wearables keep the region at the center of production. Government support in several countries for local electronics supply chains is adding further momentum. Local suppliers and distributors strengthen regional access to components.
South Korea leads in flexible OLED and foldable panels, while China has expanded capacity quickly through local panel makers and a vast base of printed circuit board and sensor suppliers. Japan contributes materials, equipment and specialty films, and Taiwan adds flexible circuits and assembly. India is building electronics manufacturing through incentive schemes, and Southeast Asia hosts final assembly. Together these countries ensure cost leadership and rapid product iteration. Regional brands also release new foldable phones annually, which keeps panel makers investing in thinner and more durable designs and sustains component demand.
⮞China’s Ministry of Industry and Information Technology reported in August 2026 that revenue of the electronic information manufacturing sector rose 18.5% in the first half of 2026.
Europe Flexible Electronics Market Insights
Europe accounted for approximately 27.86% of the Flexible Electronics Market in 2025, led by Germany, the United Kingdom, France, the Netherlands and the Nordic countries. The region has strong research institutes and companies in organic electronics, printed sensors, specialty silicones and flexible circuits. Automotive manufacturers use flexible lighting and sensors in vehicle interiors, and industrial and medical equipment makers integrate thin sensors and heaters. Public funding for advanced materials and sustainability supports pilot lines. Sustainability rules also push suppliers toward recyclable and safer materials. Local suppliers and distributors strengthen regional access to components.
Germany is the largest market, supported by automotive and industrial demand, while the United Kingdom is notable for organic electronics and flexible display research. The Netherlands and Belgium host nanoelectronics institutes that collaborate with industry on hybrid integration. Nordic countries lead in printed paper electronics and smart packaging. European buyers emphasize recyclability, safe materials and long-term reliability, which shapes product requirements. Research consortia link universities, material suppliers and manufacturers, helping smaller companies reach commercial scale. Funding programs from the European Union support this collaboration.
⮞Eurostat reported in August 2025 that nearly 30% of people aged 16 to 74 in the European Union used wearable devices in 2024, and 7.9% used health-related connected devices.
MEA & Latin America Flexible Electronics Market Insights
The Middle East and Africa and Latin America together account for approximately 10.37% of the Flexible Electronics Market in 2025, with the Middle East and Africa at 5.40% and Latin America at 4.97%. Both regions import most devices and components. In the Gulf, the United Arab Emirates and Saudi Arabia invest in smart city and healthcare projects that use flexible sensors, while Israel contributes research and start-ups. South Africa and Egypt show early adoption of wearables and smart packaging. Government health programs in Gulf countries also encourage pilots of remote monitoring.
Latin America is led by Brazil and Mexico. Brazil has an electronics manufacturing base serving local phone and appliance demand, and Mexico is a major assembly hub for consumer devices and medical products. Argentina, Colombia and Chile add demand through retail and healthcare uptake. Growing mobile subscriptions and rising smartphone ownership lift sales of wearables and foldable devices, although price sensitivity favors lower-cost flexible products. Distributors and telecom operators bundle wearables with service plans, widening access. Regional retailers expand online sales channels.
⮞The International Telecommunication Union reported on 17 November 2025 that about 6 billion people used the internet while 2.2 billion remained offline.
Market Dynamics
Growth Drivers: Foldable Devices and Wearable Health Monitoring Drive Growth in the Flexible Electronics Market
Consumer demand for foldable and wearable devices is the strongest force behind the Flexible Electronics Market. Major phone makers now release foldable handsets every year, and tablets, laptops and automotive screens are following. Each device uses flexible displays, thin batteries, bendable circuits and sensors, creating a broad base of component demand. Strong semiconductor investment and rising electronics output also ensure healthy supply conditions for the devices that carry these parts. Carmakers also contribute through curved interior displays. Retail promotions and trade-in schemes help broaden the buyer base.
Wearable health monitoring is the second driver. Aging populations, rising chronic disease and a desire for continuous data encourage adoption of patches, smart rings, watches and textile sensors. Flexible electronics allow comfortable, skin-conforming designs that gather reliable signals over days. Regulatory flexibility for wellness devices, partnerships between sensor makers and health systems, and falling component costs encourage new entrants and expand the volume of devices produced each year. Sports and fitness brands use stretchable sensors that track motion with greater precision.
⮞The World Semiconductor Trade Statistics organization reported on 6 August 2026 that global chip sales in the first half of 2026 rose 102% year on year.
Restraints: Manufacturing Yield and Weak Handset Demand Restrain Growth in the Flexible Electronics Market
Manufacturing complexity restrains the Flexible Electronics Market. Flexible displays and circuits require tight control of thin films, encapsulation and bending reliability, and yields for new formats can be low. Capital costs for panel lines are high, which limits the number of producers, and printed devices must still meet strict reliability standards for moisture, flexing fatigue and temperature. Standards for testing bendable products are less mature than for rigid electronics. Testing and qualification therefore take longer, and these delays raise costs for start-ups seeking to commercialize new designs.
Weak demand in mature handset markets adds pressure. When phone and personal computer shipments fall, suppliers of flexible boards and panels see lower volumes, and price competition intensifies. Foldable phones remain more expensive than traditional models, which restricts their reach among cost-conscious buyers. Shortages of specialty materials, and the difficulty of recycling multilayer flexible devices, further complicate scaling in some product categories. Trade tensions and export controls on certain materials and equipment also add uncertainty to long-term supply planning for panel and circuit makers.
⮞The China Academy of Information and Communications Technology reported on 11 August 2026 that mobile phone shipments in China fell 5.5% in the first half of 2026.
Opportunities: Smart Packaging and Emerging Electronics Hubs Create Opportunities in the Flexible Electronics Market
Smart packaging and logistics offer a major opportunity. Printed sensors, thin batteries and antennas can be embedded in labels and cartons to track temperature, shock, location and authenticity at very low cost. Food, pharmaceutical and retail companies want better visibility across supply chains, and regulators are encouraging traceability. Disposable, recyclable electronics made with printing methods could create volumes far larger than those of wearable devices. Battery-free tags powered by harvested energy could extend these gains even further. Brand owners also gain anti-counterfeiting benefits.
Emerging electronics hubs provide further growth. India is scaling mobile phone production and building component ecosystems, and Southeast Asia, Mexico and the Gulf are adding assembly and design capacity. Local production lowers costs for flexible sensors and displays intended for regional markets. Applications in smart agriculture, energy harvesting, defense and robotics skins also offer new paths for suppliers that can deliver durable, customizable products. Public programs that fund pilot production lines help smaller firms bridge the gap between prototype and volume manufacturing, which is where many promising technologies stall.
⮞The Indian Cellular and Electronics Association reported on 13 January 2026 that India was expected to produce about 300 million mobile phones by the end of fiscal year 2026.
Recent Developments:
-
2025: WACKER announced serial production of NEXIPAL Sense, a stretchable silicone sensor laminate with layers of 20 to 200 µm, 100 µm pixels and ±5 µm accuracy, made by roll-to-roll laser printing and shown at K 2025.
-
2026: LG Display presented a 32-inch Slidable OLED for vehicles at SID Display Week, showing a panel that extends and retracts to change the usable screen area inside the cabin.
-
2026: Samsung Display showed a 7.6-inch Wide View flexible OLED at IMID 2026 in Busan, using new emissive-layer materials and structure to address the brightness loss in curved areas of foldable panels.
-
2026: All Flex Solutions acquired Flex Interconnect Technologies, creating an end-to-end flex and rigid-flex offering for military, aerospace and medical customers.
Flexible Electronics Market Key Players are:
-
Samsung Display Co., Ltd.
-
Samsung Electronics Co., Ltd.
-
LG Display Co., Ltd.
-
WACKER Chemie AG
-
Murata Manufacturing Co., Ltd.
-
Tekscan, Inc.
-
Interlink Electronics, Inc.
-
Zinergy, Inc.
-
All Flex Solutions, Inc.
Flexible Electronics Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 34.71 Billion |
| Market Size by 2035 | USD 79.86 Billion |
| CAGR | CAGR of 8.69% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Display, Battery, Sensors, Memory, and Others) • By Application (Consumer Electronics, Automotive, Healthcare, Industrial, and Others) • By Material (Plastic Substrates, Metal Foils, Glass, and Others) • By Technology (Printed Electronics, Organic Electronics, and Thin-Film Electronics) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Samsung Display Co., Ltd., Samsung Electronics Co., Ltd., LG Display Co., Ltd., WACKER Chemie AG, Murata Manufacturing Co., Ltd., Tekscan, Inc., Interlink Electronics, Inc., Zinergy, Inc., All Flex Solutions, Inc. |

Frequently Asked Questions
The key players in the Flexible Electronics Market include Samsung Display Co., Ltd., Samsung Electronics Co., Ltd., LG Display Co., Ltd., WACKER Chemie AG, Murata Manufacturing Co., Ltd., among others.
Key opportunities include smart packaging and logistics sensors, wearable health patches, and growing electronics manufacturing hubs in India, Southeast Asia, Mexico and the Gulf.
The major growth factor is consumer demand for foldable devices and wearable health monitors, which use flexible displays, thin batteries, circuits and sensors.
The Display segment dominated the Flexible Electronics Market with approximately 50.67% share in 2025, because flexible OLED panels ship in large volumes inside foldable phones, smartwatches and vehicles.
North America dominated the Flexible Electronics Market with a 32.14% share in 2025, supported by leading consumer technology brands, medical and defense research, and government-backed flexible hybrid electronics programs.
