
Fuel Cell Powertrain Market Report Scope & Overview:
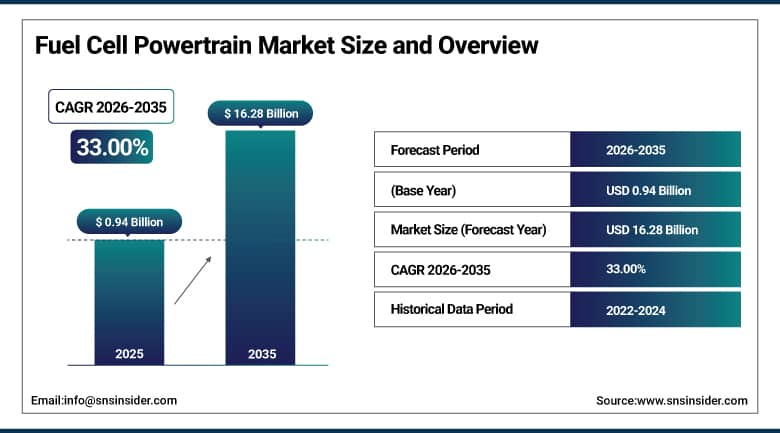
The Fuel Cell Powertrain Market was valued at USD 0.94 Billion in 2025 and is expected to reach USD 16.28 Billion by 2035, growing at a CAGR of 33.00% from 2026-2035.
The Fuel Cell Powertrain Market growth is being driven primarily by growing regulatory pressure for zero-emission vehicles, which continues to accelerate automaker and government investment in hydrogen-based propulsion systems capable of converting stored hydrogen into electricity to drive traction motors without producing harmful tailpipe emissions. Fuel cell powertrains offer refueling times under five minutes and driving ranges exceeding 450 miles for heavy-duty platforms, delivering a structurally differentiated value proposition relative to battery-electric alternatives for commercial and heavy-duty transport segments where payload capacity and rapid refueling are critical operational requirements. Demand is further reinforced by rapid cost declines in fuel cell stack technology and expanding hydrogen refueling infrastructure across key economies in Asia-Pacific, North America, and Europe, which continue to provide the distribution backbone underpinning fleet-scale adoption. Growing capital inflows into green hydrogen projects and strategic alliances between automakers and fuel cell specialists are lowering technology risk and broadening commercial applications, positioning the market for sustained, rapid growth through the coming decade.
Toyota Motor Corporation signed an agreement with Daimler Truck AG and the Volvo Group to join cellcentric, the companies' existing fuel cell system joint venture, as an equal shareholder alongside the two founding partners.
To Get More Information On Fuel Cell Powertrain Market - Request Free Sample Report
Fuel Cell Powertrain Market Trends
- Rapid cost declines in fuel cell stack technology improving total cost of ownership for hydrogen vehicles.
- Expanding hydrogen refueling infrastructure development across Asia-Pacific, North America, and Europe.
- Growing strategic alliances and joint ventures between automakers and fuel cell technology specialists.
- Increasing focus on heavy-duty commercial trucks and buses as the primary near-term commercial application.
- Continued breakthrough durability gains extending fuel cell system lifetimes and compressing payback periods.
U.S. Fuel Cell Powertrain Market Outlook
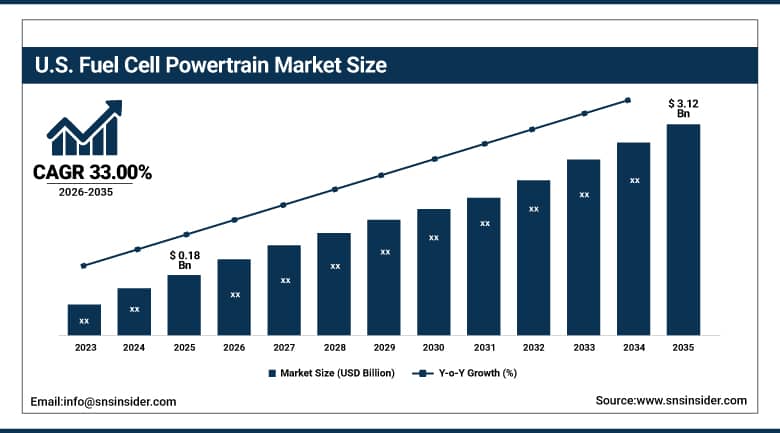
The U.S. Fuel Cell Powertrain Market was valued at USD 0.18 Billion in 2025 and is expected to reach USD 3.12 Billion by 2035, growing at a CAGR of 33.00% from 2026-2035.
The U.S. Fuel Cell Powertrain Market will find additional strength in investments in hydrogen fueling infrastructure on freight corridors, consistent collaboration between car manufacturers and engine makers regarding hydrogen powertrain technology, and continuous government support in promoting zero emissions heavy duty vehicles. In addition, domestic demand will be boosted through testing initiatives by commercial fleets that will keep validating the suitability of hydrogen fuel cells for use in long-haul and high utilization freight transport. Expansion in hydrogen fueling infrastructure will further boost demand as fleets start considering hydrogen as an alternative zero-emissions technology to batteries.
In June 2025, Hyundai Motor Company debuted its vision for a Class 8 hydrogen refueling hub featuring 76 fueling stalls for commercial vehicles, with initial customers including J.B. Hunt Transport Services and fully electric carrier Nevoya. The hub concept reflects continued domestic investment in hydrogen refueling infrastructure necessary to support fleet-scale adoption of fuel cell-powered heavy-duty trucks across major U.S. freight corridors.
Fuel Cell Powertrain Market Segment Analysis
- By Component, the Fuel Cell System segment dominated the Fuel Cell Powertrain Market with approximately 47.83% share in 2025, while the Hydrogen Storage System segment is the fastest growing with a CAGR of approximately 35.56%.
- By Vehicle Type, the Commercial Vehicles segment dominated the Fuel Cell Powertrain Market with approximately 87.00% share in 2025, while the Passenger Cars segment is the fastest growing with a CAGR of approximately 34.80%.
- By Power Output, the Less than 150 kW segment dominated the Fuel Cell Powertrain Market with approximately 60.00% share in 2025, while the More than 250 kW segment is the fastest growing with a CAGR of approximately 34.90%.
- By Drive Type, the Rear-Wheel Drive segment dominated the Fuel Cell Powertrain Market with approximately 53.41% share in 2025, while the All-Wheel Drive segment is the fastest growing with a CAGR of approximately 35.58%.
By Component, Fuel Cell System dominates and Hydrogen Storage System grows fastest
Fuel Cell Systems continue to be the leading component category in the Fuel Cell Powertrain Market due to the nature of the systems as the fundamental element which utilizes the stored hydrogen and turns it into electricity to propel the traction motor of the vehicle. The Fuel Cell Systems have the advantage of the constant investment made by manufacturers in order to increase the durability and reduce the costs associated with these systems, which are the key factor influencing the commercial viability of fuel cell powertrains.
Hydrogen Storage Systems continue to be the fastest-growing component category as a result of the progress made in high pressure storage tanks which are able to increase the driving range of the vehicles and take care of the weight and space issues on board.
By Vehicle Type, Commercial Vehicles dominates and Passenger Cars grows fastest
Commercial Vehicles overwhelmingly dominate the vehicle type segment within the Fuel Cell Powertrain Market, reflecting the technology's structurally differentiated value proposition for long-haul trucking and heavy-duty fleet applications where rapid refueling and superior payload capacity outweigh battery-electric alternatives. This segment benefits from concentrated hydrogen refueling infrastructure development along major freight corridors, which continues to make commercial fleet applications the most economically viable near-term use case for fuel cell technology.
Passenger Cars are emerging as the fastest-growing vehicle type segment off a comparatively small base, driven by continued automaker investment in next-generation fuel cell stack technology designed for both heavy-duty commercial and passenger vehicle applications. This segment focuses on improving cost competitiveness and expanding hydrogen refueling accessibility for individual consumers, positioning passenger vehicle applications to capture growing demand as fuel cell technology continues to mature beyond its commercial vehicle core.
By Power Output, Less than 150 kW dominates and More than 250 kW grows fastest
The Less than 150 kW power output segment continues to dominate the Fuel Cell Powertrain Market, owing to the power demands of most existing passenger vehicles and light commercial fuel cell vehicles. The segment enjoys efficient fuel cell stack design tailored to the respective power output needs, thus providing economies of scale in the manufacturing of the fuel cells used in mainstream fuel cell vehicles.
The More than 250 kW power output segment will soon become the fastest-growing market segment. The demand for high-power fuel cell technology is on the rise due to the need for such fuel cells for long-distance transportation trucks and buses. The high-power segment targets the design scalability of fuel cell stacks to meet the high power and durability demands of the heavy-duty commercial vehicles.
By Drive Type, Rear-Wheel Drive dominates and All-Wheel Drive grows fastest
The Rear-Wheel Drive drive type segment continues to account for a majority share of the Fuel Cell Powertrain Market owing to the extensive application of this drive system in heavy-duty commercial trucks owing to their compatibility with conventional commercial vehicle chassis and load distribution systems. The Rear-Wheel Drive drive type segment is aided by the existing practice of using rear-wheel drive configurations in the engineering of commercial vehicles.
The All-Wheel Drive drive type segment is expected to be the fastest-growing drive type segment, spurred by the rising preference for the adoption of fuel cell powertrain systems in off-highway, construction, and specialized vehicles in which traction and stability become crucial. The All-Wheel Drive drive type segment aims at modifying the fuel cell powertrain system to work in tougher environments, making all-wheel drive fuel cell systems an attractive option in non-conventional commercial vehicles.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
48.60% |
|
North America |
United States |
85.50% |
|
Europe |
Germany |
34.60% |
|
Latin America |
Brazil |
41.80% |
|
Middle East & Africa |
United Arab Emirates |
36.60% |
Asia Pacific Fuel Cell Powertrain Market Insights
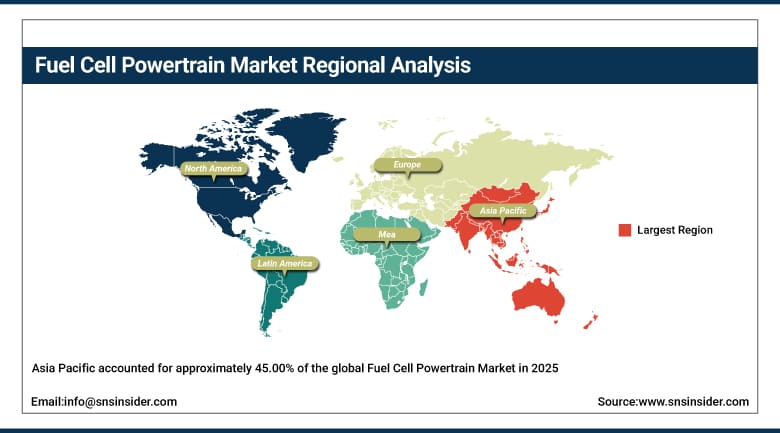
Asia Pacific accounted for approximately 45.00% of the global Fuel Cell Powertrain Market in 2025 and is also projected to expand at the fastest of around 41.20% during the 2026-2035 forecast period, supported by government policies promoting clean energy and large-scale fuel cell vehicle production. China represents the largest single contributor within the region, supported by government policy backing clean energy adoption, large-scale fuel cell vehicle production, and continued development of green hydrogen infrastructure.
Japan and South Korea contribute additional regional demand, home to established fuel cell technology developers with decades of accumulated hydrogen propulsion engineering expertise. India's growing government support for clean and renewable energy sources further reinforces the region's overall market development, supporting Asia Pacific's position as both the largest and fastest-growing global market for fuel cell powertrain technology.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Fuel Cell Powertrain Market Insights
North America represents a significant regional market for fuel cell powertrains, anchored by the United States' growing hydrogen refueling infrastructure investment and its concentration of leading heavy-duty engine and fuel cell technology developers. The United States accounts for the substantial majority of regional demand, reflecting both its commercial freight corridor infrastructure and its role as home to major fuel cell technology partnerships and joint ventures.
Canada contribute additional regional volume through cross-border commercial vehicle fleet operations. Continued government support for zero-emission heavy-duty vehicle adoption and expanding hydrogen refueling hub infrastructure further reinforce North America's position as a significant regional market for fuel cell powertrain technology.
Europe Fuel Cell Powertrain Market Insights
Europe is an important region for fuel cell powertrains, owing to the strong German commercial vehicle manufacturing base and the presence of important truck manufacturers who are looking to develop fuel cell technology, including series production of fuel cell trucks. The importance of Germany within Europe stems from not only its strong position within commercial vehicle manufacturing but also its own domestic presence of important joint ventures producing fuel cell systems.
Other important demand within the region comes from France and the Netherlands, with the aid of important hydrogen infrastructure initiatives. The continued attention being paid to zero emission heavy duty vehicles by the European Union helps ensure demand for fuel cell technology in Europe.
MEA & Latin America Fuel Cell Powertrain Market Insights
The Middle East & Africa region remains a smaller contributor to global demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where growing investment in hydrogen production and clean energy infrastructure is gradually increasing interest in fuel cell vehicle technology. Broader regional demand remains limited relative to Asia Pacific, North America, and Europe, reflecting the technology's early stage of commercial development in the region.
Latin America's Fuel Cell Powertrain Market is led by Brazil, which accounts for the majority of regional demand on the strength of its growing interest in alternative fuel commercial vehicle technology. Gradual development of regional hydrogen infrastructure continues to support steady, if comparatively modest, regional market development.
Market Dynamics
Growth Drivers: Zero-Emission Regulation and Heavy-Duty Application Advantages
The growing regulatory push for zero-emission vehicles constitutes the major growth driver for the Fuel Cell Powertrain Market, as regulations get increasingly strict regarding the emissions from automobiles in favor of using hydrogen as well as batteries for the propulsion of commercial and heavy-duty vehicle applications. Such market dynamics are additionally supported by the inherent structural benefits of fuel cell powertrains for heavy-duty use cases such as fast refueling time and higher payload compared to battery-powered vehicles.
Decreasing costs of fuel cell stacks and the development of hydrogen infrastructure represent an additional substantial source of demand, as the decreasing cost of fuel cells makes the economics of owning fuel cell vehicles more favorable against conventional diesel and battery electric vehicles. Increased capital flows to green hydrogen production plants make it more economically viable to use hydrogen as a fuel.
Restraints: Limited Refueling Infrastructure and High System Costs
Lack of hydrogen refueling infrastructure apart from freight corridors is one of the major restraints for the Fuel Cell Powertrain Market due to the requirement of a much larger network than currently exists in order to foster commercialization. The aspect is more relevant when it comes to passenger vehicles because there is a need for fueling infrastructure, which poses an impediment compared to electric charging infrastructure.
Higher costs for fuel cell stacks and hydrogen storage compared to diesel engines and battery electric powertrains act as a hindrance for the immediate feasibility of fuel cells in the market except for some specialized uses where the technology's value outweighs the higher cost. Higher green hydrogen costs and its availability pose another issue regarding the fuel's competitiveness.
Opportunities: Heavy-Duty Fleet Adoption and Joint Venture Consolidation
Continued expansion of heavy-duty commercial truck and bus fleet adoption presents a substantial growth opportunity for the Fuel Cell Powertrain Market, as these applications represent the most economically viable near-term commercial use case given hydrogen's rapid refueling and superior payload capacity advantages. Manufacturers that can demonstrate validated, cost-competitive heavy-duty fuel cell powertrain solutions are well positioned to capture share as fleet operators increasingly explore hydrogen as a complement to battery-electric alternatives.
Rising joint venture and strategic alliance activity between automakers and fuel cell technology specialists presents a longer-term opportunity for companies to share technology development costs and accelerate commercialization timelines. As leading automakers continue consolidating fuel cell development resources through shared ventures, companies with established hydrogen propulsion engineering capabilities are positioned to capture a disproportionate share of this emerging demand.
Recent Developments:
- 2026: Trimac began a hydrogen truck pilot program with Hyundai, testing fuel cell-powered heavy-duty trucks in real-world freight operations as part of continued fleet-scale validation of hydrogen commercial vehicle technology.
- 2026: Daimler Truck unveiled the Mercedes-Benz NextGenH2 Truck, with a small-series production run of 100 units manufactured at the Mercedes-Benz plant in Wörth, Germany, for deployment with various customers beginning near the end of 2026.
Fuel Cell Powertrain Market Key Players are:
- Toyota Motor Corporation
- Hyundai Motor Company
- Honda Motor Co., Ltd.
- Ballard Power Systems Inc.
- Cummins Inc.
- Robert Bosch GmbH
- Plug Power Inc.
- Ceres Power Holdings plc
- Nikola Corporation
- Hyzon Motors Inc.
- Nel ASA
- ITM Power plc
- AVL List GmbH
- cellcentric GmbH & Co. KG
- Weichai Power Co., Ltd.
- Sinopec (China Petroleum & Chemical Corporation)
- FAW Group Corporation
- Doosan Fuel Cell Co., Ltd.
- PowerCell Sweden AB
- Symbio SAS
Fuel Cell Powertrain Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.94 Billion |
| Market Size by 2035 | USD 16.28 Billion |
| CAGR | CAGR of 33.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Fuel Cell System, Hydrogen Storage System, Motor/Generator, and Battery & BMS) • By Vehicle Type (Commercial Vehicles and Passenger Cars) • By Power Output (Less than 150 kW, 150-250 kW, and More than 250 kW) • By Drive Type (Rear-Wheel Drive, Front-Wheel Drive, and All-Wheel Drive) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Toyota Motor Corporation; Hyundai Motor Company; Honda Motor Co., Ltd.; Ballard Power Systems Inc.; Cummins Inc.; Robert Bosch GmbH; Plug Power Inc.; Ceres Power Holdings plc; Nikola Corporation; Hyzon Motors Inc.; Nel ASA; ITM Power plc; AVL List GmbH; cellcentric GmbH & Co. KG; Weichai Power Co., Ltd.; Sinopec (China Petroleum & Chemical Corporation); FAW Group Corporation; Doosan Fuel Cell Co., Ltd.; PowerCell Sweden AB; Symbio SAS. |
Frequently Asked Questions
Leading companies in the Fuel Cell Powertrain Market include Toyota Motor Corporation, Hyundai Motor Company, Cummins, cellcentric, and Ballard Power Systems, among others.
Key opportunities include continued expansion of heavy-duty commercial truck and bus fleet adoption, and rising joint venture activity between automakers and fuel cell technology specialists.
Growing regulatory pressure for zero-emission vehicles, combined with fuel cell powertrains' structurally differentiated advantages for heavy-duty commercial applications, is the major factor driving market growth.
The Commercial Vehicles segment dominated the Fuel Cell Powertrain Market with approximately 87.00% share in 2025.
Asia Pacific dominated the Fuel Cell Powertrain Market in 2025 with approximately 45.00% share, supported by government policies promoting clean energy, led by China.
