
Hybrid Printing Market Report Scope & Overview:
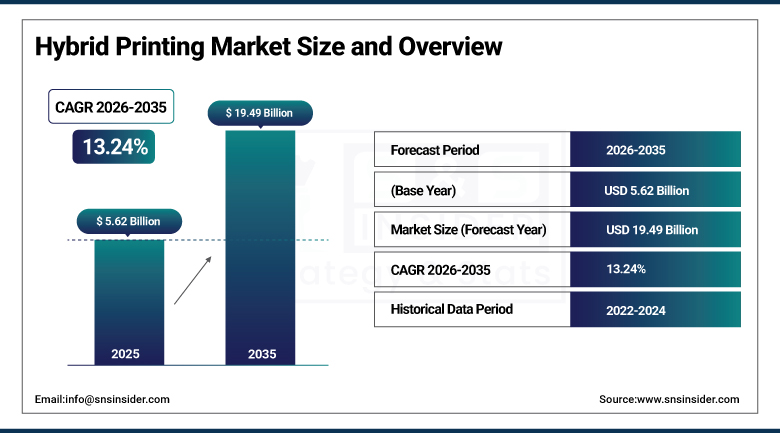
The Hybrid Printing Market was valued at USD 5.62 Billion in 2025 and is projected to reach USD 6.36 Billion in 2026. It is anticipated to grow at a CAGR of 13.24% during the forecast period (2026-2035) and will hit a valuation of USD 19.49 Billion by 2035. Hybrid printing is used to digitally print using inkjet or toner technology while incorporating traditional printing techniques such as flexo, offset, gravure, and screen printing in one integrated printing system or process. Most commonly used in label and packaging applications, hybrid printing is growing due to short print runs, greater variety and converters wanting to benefit from digital printing with traditional printing speeds and finishing.
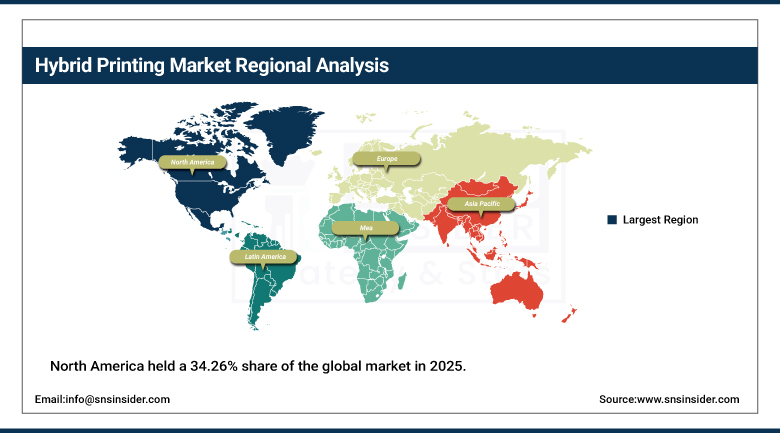
North America was the largest regional market in 2025, with a 34.26% share. The region has a mature label and flexible packaging industry, a large base of narrow-web presses, and brand owners that release many product variants each year. Converters in the United States and Canada are adding digital stations to existing flexo lines, and extended producer responsibility laws are pushing demand for lighter and more recyclable packaging. Asia Pacific and Europe follow closely, with strong installation activity in China, India, and Germany. Investment in digital finishing is also rising steadily.
To Get more information On Hybrid Printing Market - Request Free Sample Report
Key Report Takeaways
-
By printing technology, flexo and inkjet hybrids held a 44.30% share in 2025, while screen and inkjet hybrids are the fastest growing.
-
By ink type, UV-curable inks held a 38.60% share in 2025, while water-based inks are the fastest growing.
-
By substrate, paper and paperboard held a 38.10% share in 2025, while films and plastics are the fastest growing.
-
By application, labels held a 41.70% share in 2025, while textile and apparel is the fastest growing.
-
By region, North America held a 34.26% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Inline, single-pass hybrid lines are replacing separate printing and finishing steps. Converters want digital color, flexo varnish, foil, lamination, and die cutting in one pass, which cuts handling, reduces waste, and shortens the time between order and delivery for short-run work.
Retrofit modules are opening the market to existing press owners. Digital print bars can be added to installed flexo and offset machines, which lets converters protect earlier capital investments while adding variable data, personalization, and short-run capability at a much lower cost than a new press.
Inks are changing. UV-LED curing, low-migration formulations, and water-based inkjet fluids are being developed for food, pharmaceutical, and flexible packaging use, and suppliers are working on adhesion and durability so that digital output matches the performance of conventional flexo inks.
Automation and software are becoming part of the machine. Closed-loop color control, predictive maintenance, and workflow tools that link hybrid presses to ordering systems reduce makeready time and allow smaller crews to operate more complex equipment, while leasing models lower the entry barrier.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Short Runs, SKU Proliferation, and E-commerce Packaging |
+2.34% |
Global |
Short term (2 years or less) |
|
UV Inkjet Quality Parity with Flexo |
+2.08% |
Global |
Medium term (2 to 4 years) |
|
Single-Pass Inline Finishing and Converter Productivity |
+1.79% |
Europe, North America, Asia Pacific |
Medium term (2 to 4 years) |
|
Smart Packaging, QR Codes, and Product Passports |
+1.47% |
Europe, North America |
Medium term (2 to 4 years) |
|
Pharmaceutical Serialization and Traceability |
+1.19% |
North America, Europe |
Short term (2 years or less) |
|
Automation, Predictive Maintenance, and Leasing Models |
+1.02% |
Global |
Long term (4 years or more) |
Short Runs, SKU Proliferation, and E-commerce Packaging
Brand owners now launch more products, seasonal editions, and regional variants, and each one needs its own label or carton design. Conventional flexo plates and offset setups are costly for runs of a few hundred meters, while digital printing handles them easily. Hybrid presses allow converters to run short jobs and long jobs on one machine, with spot colors, varnish, and embellishments applied by analog units. E-commerce shipments also call for personalized and promotional packaging, which adds demand for flexible production setups that switch jobs quickly.
UV Inkjet Quality Parity with Flexo
Print heads and UV inks have improved to the point where digital output approaches the sharpness, opacity, and color gamut of flexo, even on films and uncoated papers. Resolution of 1,200 dpi is now common on label presses, and white ink and extended color sets widen the range of designs. As quality gaps close, brand owners accept digital elements on premium packaging, which allows hybrid presses to take on complex jobs that earlier required several separate machines and longer production schedules.
Single-Pass Inline Finishing and Converter Productivity
Converters are under pressure to reduce lead times and labor costs, and inline finishing removes handling between printing, varnishing, laminating, and die cutting. The LOUPE Europe exhibition in Barcelona in September 2025 drew 37,122 visitors, 670 exhibitors, and participants from 140 countries, with hybrid and digital finishing lines among the main attractions. Such interest reflects a clear shift toward machines that complete a job in one pass and cut waste during makeready. Converters with tight delivery schedules gain a clear advantage from this approach.
Smart Packaging, QR Codes, and Product Passports
Packages now carry QR codes, digital links, and serialized data that connect shoppers, recyclers, and regulators to product information. GS1 published version 1.5.0 of its Digital Link URI syntax in June 2024, giving brand owners a common way to encode this data in a single code. Hybrid presses are well suited to this trend because analog units print the base design at speed while digital heads add unique variable codes to each label or carton. Regulators in several regions are expected to follow with similar requirements.
Pharmaceutical Serialization and Traceability
Drug packaging must carry unique identifiers that support tracing from factory to pharmacy. The United States Food and Drug Administration issued small-dispenser exemptions under the Drug Supply Chain Security Act in 2024 that expire on 27 November 2026, which moves smaller pharmacies toward full compliance. Hybrid presses print variable codes digitally on labels and cartons while keeping analog quality for the fixed artwork, making them a practical choice for healthcare packaging. Contract packagers and brand owners are therefore ordering equipment capable of printing serialized data reliably.
Automation, Predictive Maintenance, and Leasing Models
Machine suppliers are adding sensors, remote diagnostics, and automatic registration so that hybrid presses run with fewer interventions. Predictive maintenance warns operators of head wear or ink supply issues before they cause waste, and software links the press to order management. Leasing and pay-per-use arrangements also reduce the capital cost of a new line, which opens the technology to mid-sized converters. Together these developments raise utilization and improve the return on each machine. Suppliers also offer subscription software that tracks press performance across several sites.
Restraints Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Capital Cost and Integration Complexity |
-1.72% |
Global |
Medium term (2 to 4 years) |
|
Shortage of Dual-Skilled Operators |
-1.41% |
Global |
Long term (4 years or more) |
|
Tariff and Component Supply Volatility |
-1.03% |
North America, Europe |
Short term (2 years or less) |
|
Competition from All-Digital Presses and Demand Swings |
-0.79% |
Global |
Medium term (2 to 4 years) |
High Capital Cost and Integration Complexity
A hybrid line costs far more than a conventional flexo press, and the combination of analog and digital units adds integration work for registration, color management, and workflow software. Vendors often build proprietary architectures, which limits flexibility for buyers who want to mix equipment from different makers. Small converters therefore hesitate, particularly when consumables, maintenance, and software licenses add recurring expense. Long payback periods in slower markets also delay orders for new lines. Financing costs in several regions add pressure to buying decisions.
Shortage of Dual-Skilled Operators
Operators need skills in both analog printing such as anilox rolls/plates/varnish and digital printing such as head maintenance/color profiling/data files to run hybrid presses. Few operators will have both these skills and training takes a while. This means that it can be difficult for converters to fill second/third shift roles with skilled individuals. This leads to less utilization and people being reluctant to buy. Although suppliers provide training and remote support it remains an issue due to high turnover and experienced operators getting older. The younger staff are less familiar with analog press set up.
Tariff and Component Supply Volatility
Inkjet heads and drive electronics are imported from a small number of suppliers, and tariffs change the landed cost of machines and spare parts. Silicone liner supply, which relies on platinum-based chemistry, adds a further risk for label producers. Unpredictable import duties complicate quotations for machines that take months to deliver, and some buyers postpone orders until trade conditions become clearer. Suppliers respond with regional stocks and dual sourcing, though these measures raise costs. Currency swings add to the cost pressure for buyers outside the United States.
Competition from All-Digital Presses and Demand Swings
Pure digital label presses continue to improve in speed and quality, and many converters choose them for simplicity when their work consists mostly of short runs. Label demand also moves with retail and consumer goods cycles, which makes buyers cautious about large investments. Where volumes are uncertain, converters may prefer to subcontract digital work or to retrofit a single module rather than buy a full hybrid line, which slows the pace of new press sales. Price competition among suppliers of digital presses adds to the pressure.
Hybrid Printing Market Segment Analysis
By Printing Technology, Flexo and Inkjet Hybrids Dominate Hybrid Printing Market; Screen and Inkjet Hybrids to Register Fastest Growth.
Flexo and inkjet hybrids lead because flexo is the most common process in label and flexible packaging plants, and adding a digital engine to it is the natural step. These lines accounted for 44.30% of the market in 2025. They allow converters to print the base artwork digitally while using flexo stations for varnish, white, and metallic effects. Converters can also keep using familiar plates, anilox rolls, and converting units, so adoption faces little operator resistance. Operators adapt quickly.
Screen and inkjet hybrids are projected to expand at a CAGR of 16.07% from 2026 to 2035. Screen units lay down thick deposits for tactile coatings, raised effects, and high-opacity inks that inkjet cannot match, and combining them with digital variable printing creates premium labels, textile designs, and decorative products. Brand owners looking for distinctive shelf appeal are encouraging converters to invest in such lines. Several builders now offer modular screen units that can be added to existing digital platforms.
By Ink Type, UV-Curable Inks Dominate Hybrid Printing Market; Water-Based Inks to Register Fastest Growth.
UV curable inks are the largest segment in the market accounting for 38.60% of the market in 2025. They cure instantly when exposed to UV lamps. This means they have excellent adhesion to film, paper and metallised substrates whilst being resistant to scratching. This makes them a good option for labelling and packaging applications. Low energy usage and reduced heating of delicate substrates has been achieved by using LED curing. The fact that both analog and digital print units can share curing stations makes them a great fit for hybrid lines. Due to this reason UV is also the go-to ink choice for converters. Shared curing stations also make life easy for converters.
Water-based inks are forecast to grow at a CAGR of 15.42% over 2026 to 2035. Food and beverage brands, regulators, and recyclers favor inks with low migration and low odor, and water-based chemistries meet many of those expectations. Improved print heads and primers now allow acceptable adhesion on paper and coated films, and suppliers are developing formulations for flexible packaging. Environmental targets are accelerating adoption among converters. Early adopters report steady gains in food contact and pharmaceutical applications.
By Substrate, Paper and Paperboard Dominate Hybrid Printing Market; Films and Plastics to Register Fastest Growth.
Paper and paperboards made up 38.10% of the market in 2025. Paper based substrates are used in pressure sensitive labelling, folding cartons and corrugated liners. They can be easily printed using analog and digital inks with little pre-treatment. Driven by sustainability goals and a move away from plastic usage in some food and consumer applications, paper based materials are seeing demand grow. With lots of coated and uncoated options available, this makes them cost effective to convert at any size. They also have strong sustainability credentials for packaging.
The film and plastics industry is anticipated to grow at a CAGR of 15.19% from 2026-2035. Flexible pouches, shrink sleeves and high-end labelling applications rely on polypropylene, polyethylene and polyester film substrates for their moisture and chemical resistance properties. With digital primer technologies, white inks and low migration chemistries allowing for better print quality, brand owners are looking to this substrate to improve their shelf appeal and product protection. This is driving increased demand for hybrid lines from flexible packaging converters globally. Lightweight pouching is also driving demand.
By Application, Labels Dominate Hybrid Printing Market; Textile and Apparel to Register Fastest Growth.
Labels are the leading application, holding 41.70% of the market in 2025. The label industry pioneered the mix of flexo and digital printing, and narrow-web presses with inline varnish, foil, and die-cutting units suit its demand for many variants and short runs. Food, beverage, personal care, and household products all rely on labels, and brand owners keep adding versions, which sustains orders for hybrid label presses worldwide. Short run label work also reduces warehouse stock for brand owners.
Textile and apparel is projected to expand at a CAGR of 16.12% from 2026 to 2035. Fashion and sportswear brands want faster design cycles, smaller batches, and personalized products, and hybrid lines combining screen or rotary units with digital inkjet deliver both volume and variety. Reduced water use compared with traditional dyeing and printing is also attractive. Producers in Asia and Europe are expanding capacity as demand for on-demand garments grows. Demand for on-demand garments keeps rising steadily.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.80% |
|
Europe |
Germany |
36.40% |
|
Asia Pacific |
China |
34.60% |
|
Middle East & Africa |
United Arab Emirates |
24.50% |
|
Latin America |
Brazil |
45.70% |
North America Hybrid Printing Market
North America held a 34.26% share of the global market in 2025. The United States market was valued at USD 1.59 Billion in 2025 and is projected to grow at a CAGR of 12.86% from 2026 to 2035. In May 2026, California approved permanent regulations under its SB 54 packaging law, which tightens rules for recyclable and reusable packaging and gives converters reason to redesign labels and cartons. Label converters and flexible packaging plants are the main buyers. Sales cycles remain long.
Oregon launched the first packaging extended producer responsibility program in the nation in July 2025 under the Circular Action Alliance, and similar programs are being prepared in other states. Brand owners need to modify packaging in response, which creates short, repeated design changes well suited to hybrid production. Canada contributes through food and beverage packaging, while Mexico is covered under Latin America in this study, and service networks matter greatly to buyers. Distributors and press makers offer financing to support equipment purchases.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Hybrid Printing Market
Asia Pacific accounted for 31.84% of the global market in 2025 and is the fastest-growing region, with a projected CAGR of 14.70% from 2026 to 2035. China is the leading country, supported by a very large packaged goods industry, e-commerce volumes, and a growing base of domestic press makers. Brand owners there release products quickly and demand short-run labels, which suits hybrid presses. Government support for upgraded manufacturing adds further momentum. Local converters are investing in wider presses to serve large regional brands.
India is expanding rapidly, with converters adding digital stations to flexo presses to serve food, pharmaceutical, and consumer goods brands, and amended plastic packaging rules are raising targets for recycled content. Japan and South Korea contribute high-quality label and textile production, while Southeast Asian countries attract packaging plants serving export markets. Regional suppliers are also introducing lower-cost hybrid configurations for local converters. Training centers run by machine suppliers help local operators learn both analog and digital skills, which supports faster adoption.
Europe Hybrid Printing Market
Europe held a 25.97% share of the global market in 2025, with Germany as the leading country, followed by Italy, the United Kingdom, and France. The European Commission reported that the Packaging and Packaging Waste Regulation began to apply in August 2026, at a time when each resident generated 181 kilograms of packaging waste. The rule drives interest in recyclable materials, reduced packaging, and digital product information. Converters in Germany and Italy have installed many early hybrid lines and continue to upgrade them.
The region is home to several leading press builders, including Gallus, Durst, and Omet, and to many converters that adopted hybrid lines early. Statistics from Eurostat show that paper and cardboard make up 40.80% of the 81.50 million tonnes of packaging waste generated in the region in 2024, which explains the strong focus on fiber-based and recyclable label and carton solutions among converters. Brand owners in the region also request digital codes that link packaging to recycling instructions and product data.
Latin America Hybrid Printing Market
Latin America is a smaller regional market, led by Brazil, followed by Mexico, Argentina, and Colombia. Brazil has a large food, beverage, and personal care industry that sustains demand for labels and flexible packaging, and local converters are installing digital and hybrid equipment to serve brand owners that want shorter lead times. Mexico benefits from packaging supply chains tied to North American consumer goods production. Large beverage and personal care companies run regional label programs that favor flexible production across several plants.
Most hybrid machines are imported, so financing, currency conditions, and local technical support shape purchases. Distributors and press makers offer leasing, retrofit modules, and training to reach mid-sized converters. Trade shows in Mexico and Brazil introduce digital and hybrid equipment to regional buyers, and gradual adoption of variable data printing for promotions and traceability is expected to widen demand over the forecast period for suppliers. Local assemblers of presses are scarce, so imported equipment dominates new installations in the region overall.
Middle East & Africa Hybrid Printing Market
The Middle East & Africa region holds the smallest share of the market. The United Arab Emirates and Saudi Arabia are the main buyers, followed by Turkey and South Africa. Gulf Print & Pack held its first Saudi edition in Riyadh in January 2025 and attracted more than 150 exhibitors, a sign of rising investment in local packaging and printing capacity as the Kingdom diversifies its industry. Packaging plants in the Gulf are also adding digital label capability to serve local brands.
Food processing, pharmaceutical, and consumer goods plants in the Gulf are installing label and packaging lines, and free zones attract converters serving regional exports. Africa remains an early market, where limited financing and a small converter base keep volumes low, though South Africa and Egypt show steady demand. Distributors provide installation and service, and international suppliers are opening regional offices to support project business. Training and spare parts availability are important factors that influence purchasing decisions for buyers across the region.
Competitive Landscape
The Hybrid Printing Market is moderately concentrated. A group of global press builders and digital technology suppliers, including Mark Andy, Gallus, Durst Group, Omet, Domino Printing Sciences, SCREEN, Lombardi, Bobst, Arrow Systems, and MPS Systems, compete alongside regional builders. Competition rests on print quality, speed, finishing options, retrofit flexibility, and service.
Vendors pursue new product launches, partnerships between analog press builders and inkjet suppliers, and acquisitions that widen their label and packaging portfolios. Trade shows are the main stage for introducing new hybrid configurations, and suppliers invest in retrofit modules, software, and consumables to build recurring revenue from the installed base while meeting converter demands for faster delivery.
Hybrid Printing Market Industry Leaders
1. Mark Andy: Digital Series HD HighSpeed 1200 hybrid press with digital and flexo stations running up to 146 meters per minute.
2. Gallus: Gallus Five hybrid press on the Labelmaster platform at 1,200 dpi, part of the Heidelberg group.
3. Durst Group: KJet hybrid press built with Omet servo flexo units and Durst digital engines.
4. Omet: KFlex K6 multi-technology line combining flexo, offset, gravure, screen, and digital units.
5. Domino Printing Sciences: N610i and N730i inkjet modules for hybrid integration on partner flexo presses.
Companies Covered in this Report
-
Mark Andy
-
Gallus (Heidelberg)
-
Durst Group
-
Omet
-
Domino Printing Sciences
-
SCREEN
-
Lombardi
-
Bobst
-
Arrow Systems
-
MPS Systems
-
Dantex
Recent Industry Developments
-
July 2025: Mark Andy announced the Digital Series HD HighSpeed 1200, a hybrid press running at 146 meters per minute.
-
July 2025: Domino Printing Sciences unveiled the N730i Integration Module and a Grafotronic DCL2 hybrid configuration.
-
August 2025: SCREEN and Lombardi announced the Truepress LABEL 350UV SAI S integrated into the Lombardi Digistar Hybrid line.
-
September 2025: Gallus, part of the Heidelberg group, launched the Gallus Five hybrid press.
-
September 2025: Arrow Systems revealed the ArrowJet Bolt with inline flexo priming and varnishing at 150 meters per minute.
-
September 2026: Durst Group agreed to acquire MPS Printing, with the transaction due to take effect on 1 January 2027.
-
September 2026: Omet showed its KFlex K6 multi-technology line at LOUPE Americas.
-
September 2026: Bobst demonstrated the Digital Master 340, which combines digital printing with flexo and converting modules.
Scope and Research Methodology
This study covers the Hybrid Printing Market, which includes presses and workflows that combine analog printing processes such as flexo, offset, gravure, and screen with digital inkjet or toner engines, delivered as new hybrid presses, inline systems, and retrofit modules. The base year is 2025, the forecast period is 2026 to 2035, and all values are expressed in USD. The market is segmented by printing technology, ink type, substrate, application, and region. Presses used mainly for labels, packaging, textiles, and commercial work are included. All-digital and all-analog presses and flexible hybrid electronics are excluded. Retrofit digital modules that convert an existing analog press into a hybrid line are counted, along with software and installation services.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, procurement leaders, and end-user stakeholders across the value chain, including press builders, inkjet suppliers, ink makers, and label and packaging converters. These conversations validate assumptions, adoption rates, and pricing. Machine installation figures and trade show announcements are reviewed to confirm demand trends and portfolio changes.
Market engineering follows a bottom-up build from press shipments, retrofit module sales, and consumables revenue, which is cross-checked top-down against label and packaging industry output. Triangulation across these views confirms segment and regional estimates. Regional figures are built from installation data and distribution channel information, then adjusted for pricing and regulation. Forecasts consider adoption of inline finishing, ink technology, packaging regulation, and macroeconomic conditions, and every dataset passes an analyst quality review before it is published. Demand is modeled by application and region, and price trends are tracked by technology. Price trends are tracked by technology and application.
Hybrid Printing Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.62 Billion |
| Market Size by 2035 | USD 19.49 Billion |
| CAGR | CAGR of 13.24% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Printing Technology (Flexo and Inkjet, Offset and Inkjet, Gravure and Inkjet, Screen and Inkjet, and Others) • By Ink Type (UV-Curable, Water-Based, Solvent-Based, and Others) • By Substrate (Paper and Paperboard, Films and Plastics, Textiles, and Others) • By Application (Labels, Packaging, Textile and Apparel, Commercial Printing, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Gallus (Heidelberg), Durst Group, Omet, Domino Printing Sciences, SCREEN, Lombardi, Bobst, Arrow Systems, MPS Systems, Dantex |

Frequently Asked Questions
The market was valued at USD 5.62 Billion in 2025 and is estimated at USD 6.36 Billion in 2026. It is projected to reach USD 19.49 Billion by 2035.
The market is projected to grow at a CAGR of 13.24% from 2026 to 2035, supported by short-run demand, inline finishing, and improved UV inkjet quality.
North America leads, with a 34.26% share in 2025, owing to its mature label and flexible packaging industry and regular packaging regulation updates.
Asia Pacific is the fastest-growing region, with a CAGR of 14.70% from 2026 to 2035, driven by packaged goods and e-commerce growth in China and India.
Flexo and inkjet hybrids, UV-curable inks, paper and paperboard, and labels lead their axes. Screen and inkjet hybrids, water-based inks, films and plastics, and textile and apparel grow fastest.
Mark Andy, Gallus, Durst Group, Omet, and Domino Printing Sciences are among the major players, with SCREEN, Lombardi, and Bobst also active.
High capital cost, a shortage of dual-skilled operators, tariff and component supply volatility, and competition from all-digital presses restrain faster growth.
