
Hydrogel Market Report Scope & Overview:
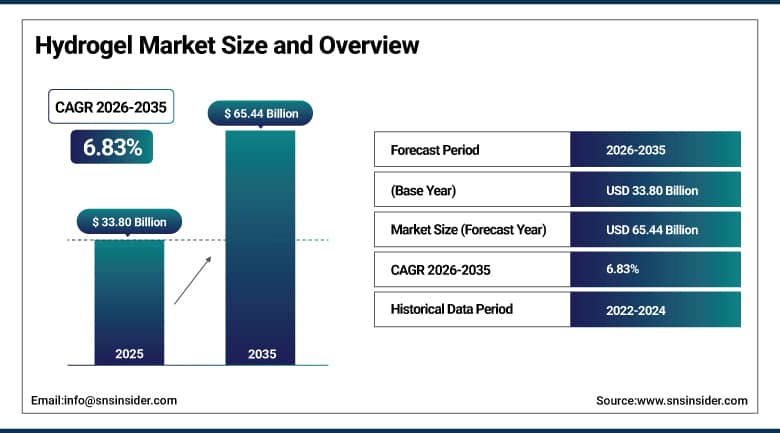
The Hydrogel Market was valued at USD 33.80 Billion in 2025 and is expected to reach USD 65.44 Billion by 2035, growing at a CAGR of 6.83% from 2026-2035.
The Hydrogel Market is expanding as water-rich polymer networks move from commodity hygiene products into medical, ophthalmic and electronic uses. Superabsorbent grades in diapers and feminine care still carry the largest volumes. Wound dressings, contact lenses and drug depots add higher-value demand. Injectable spacers and embolic gels are opening new procedural categories. Ageing populations and diabetes increase the number of chronic wound cases. Silicone-modified and naturally derived formulations widen material choices for manufacturers. Smart hydrogels for sensors and soft robotics extend the market into devices. Asia Pacific leads consumption because of large hygiene volumes. The market is expected to grow as materials, clinical evidence and manufacturing scale improve together.
⮞In April 2025, the International Diabetes Federation reported in the 11th edition of its Diabetes Atlas that 589 million adults aged 20 to 79 were living with diabetes. The size of this patient base supports steady demand for hydrogel dressings used on diabetic foot ulcers and other chronic wounds.
To Get More Information On Hydrogel Market - Request Free Sample Report
Hydrogel Market Trends:
-
Shift from passive moist-wound dressings toward antimicrobial and drug-loaded hydrogels
-
Rapid uptake of hydrogel spacers and embolic systems in oncology procedures
-
Development of injectable, self-healing hydrogels for deep wounds and tissue repair
-
Growth of plant-based and biodegradable hydrogels for agriculture and hygiene products
-
Integration of conductive hydrogels into wearable biosensors and skin-contact electronics
U.S. Hydrogel Market Outlook:
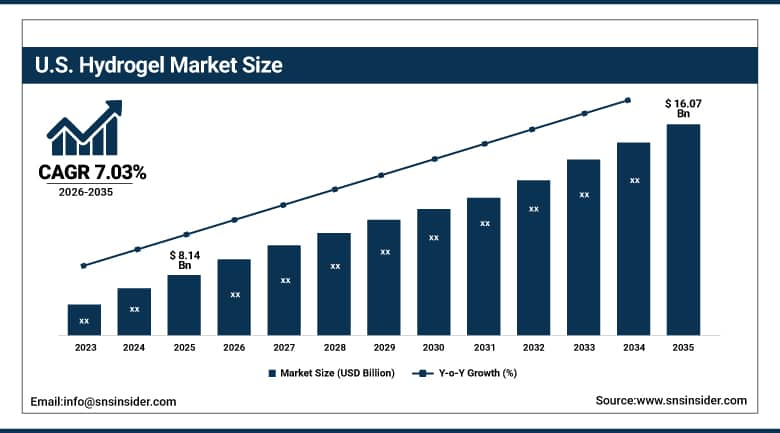
The U.S. Hydrogel Market was valued at USD 8.14 Billion in 2025 and is expected to reach USD 16.07 Billion by 2035, growing at a CAGR of 7.03% from 2026-2035.
The U.S. Hydrogel Market is supported by a large base of chronic wound patients and a deep procedure pipeline. Medicare coverage for advanced dressings keeps wound care demand stable. The Food and Drug Administration has cleared or approved several hydrogel devices, from rectal spacers to embolic systems. Contact lens wearers form a large consumer group that favors silicone hydrogel products. Radiation oncology centers are adopting spacers to protect healthy tissue. Hygiene brands and medical device makers anchor local production and research. Academic centers advance injectable and bioprinted formulations. Higher unit prices for regulated devices lift value growth above the global average. Demand is expected to rise as new approvals reach clinical practice.
⮞The American Cancer Society estimated about 333,830 new prostate cancer cases in the United States for 2026. The number of patients entering radiotherapy underpins demand for hydrogel rectal spacers.
Hydrogel Market Segment Analysis:
-
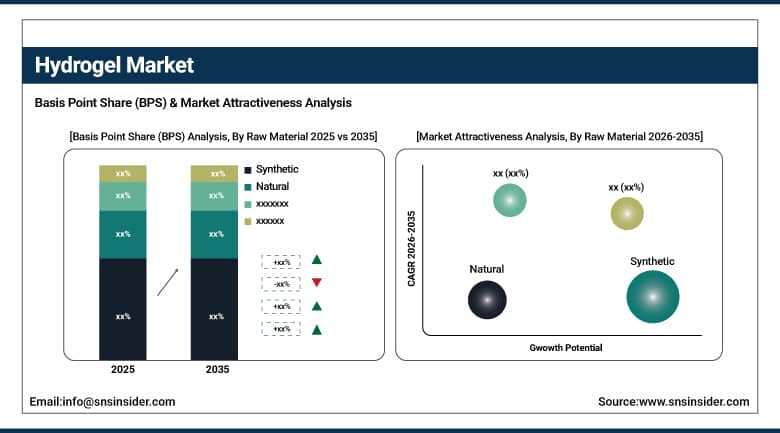
By Raw Material, the Synthetic segment dominated the Hydrogel Market with approximately 66.60% share in 2025, while the Natural segment is the fastest growing with a CAGR of approximately 7.00%.
-
By Form, the Semi-Crystalline segment dominated the Hydrogel Market with approximately 56.78% share in 2025, while the Amorphous segment is the fastest growing with a CAGR of approximately 7.72%.
-
By Composition, the Polyacrylate segment dominated the Hydrogel Market with approximately 25.33% share in 2025, while the Polyacrylamide segment is the fastest growing with a CAGR of approximately 7.29%.
-
By Application, the Personal Care and Hygiene segment dominated the Hydrogel Market with approximately 53.85% share in 2025, and is also the fastest growing with a CAGR of approximately 7.83%.
By Raw Material, Synthetic Dominates the Hydrogel Market and Natural Grows Fastest
The synthetic hydrogels represent the biggest raw material category since polymers like polyacrylate, polyacrylamide, polyvinyl alcohol, and silicone can be designed for uniform capacity to absorb, durability, and cost-effectiveness. Diaper and hygiene manufacturers purchase superabsorbent varieties in huge quantities, while medical device producers favor the synthetic variety because it is sterilizable and has an expiration date. Materials used for contact lenses and electrodes require synthetic polymers with precise specifications. There are established supply chains for these materials in Asia and Europe, making the price competitive, and their regulation files are comprehensive, thus speeding up the process of approvals for new product lines.
Natural hydrogels are developing the most dynamically as consumers seek biocompatible, biodegradable, and plant-based alternatives. Alginate, collagen, gelatin, hyaluronic acid, chitosan, agarose, and silk provide biofriendly structure suitable for tissue engineering, wound healing, and drug delivery. The scientists try to combine seaweed and silk proteins to produce injectable hydrogels which set when injected into the body. Agricultural and personal care manufacturers also want degradable materials because of tightening rules related to microplastics. Batch variability and lack of mechanical durability prevent some applications from being practical, which creates interest in hybrids of natural and synthetic materials.
⮞In May 2026, IIT Madras reported an injectable hydrogel made from silk cocoons and seaweed that gels at body temperature and is biodegradable. The researchers estimate that the approach could cut therapy cost to about USD 300 per course, although the work remains preclinical.
By Form, Semi-Crystalline Dominates the Hydrogel Market and Amorphous Grows Fastest
Semi-crystalline hydrogels lead because they combine a water-rich phase with ordered regions that give mechanical strength. Superabsorbent polymers used in hygiene products are largely semi-crystalline, which explains their large volumes. Dressings, contact lenses and sheet products also need dimensional stability during handling, and ordered domains deliver it without sacrificing fluid uptake. Converters can process these materials on existing coating, extrusion and drying lines, which keeps conversion costs low. Strong demand from diaper and feminine care manufacturers in China, India and Southeast Asia further secures this form as the commercial workhorse of the industry.
Amorphous hydrogels are growing fastest because they are supplied as gels that can be spread, injected or applied into cavities and irregular wounds. Wound care teams use them to rehydrate dry necrotic tissue and support autolytic debridement. Drug depots, embolic systems and spacers rely on injectable gels that flow through fine needles and then stabilize in the body. Self-healing and thermoresponsive grades expand clinical options, and manufacturers can fill tubes, syringes and applicators with standard sterile processes. As procedures shift toward minimally invasive delivery, demand for flowable formats is expected to outpace sheet and button products.
⮞In August 2025, Teleflex launched the Barrigel rectal spacer in Japan after regulatory approval and insurance coverage. The stabilized hyaluronic acid gel is placed between the prostate and rectum to reduce radiation exposure, and the launch shows how injectable gels are entering new national markets.
By Composition, Polyacrylate Dominates the Hydrogel Market and Polyacrylamide Grows Fastest
Polyacrylate leads composition because sodium polyacrylate is the base chemistry of the superabsorbent polymers used in diapers, adult incontinence products and feminine hygiene. Production is mature, acrylic acid is widely available, and the polymer absorbs many times its weight in fluid. Agricultural water retention grades use the same backbone, which adds demand from irrigation and soil conditioning. Large chemical groups operate integrated acrylic acid and polymer plants, so unit cost remains low and supply dependable. Hygiene brand owners qualify these grades through long contracts, which limits switching and supports stable volumes.
Polyacrylamides are experiencing their fastest growth due to their application going beyond water treatments and soil conditioning and into biomedical studies. The cross-linked polymers are flexible, transparent and have less protein affinity, making them suitable for culturing substrates, electrophoresis and diagnostics. The medical industry is investigating polyacrylamide-based injectable filler agents and soft tissues, though the safety data undergoes strict scrutiny by the relevant authorities. Oil fields and mining industries utilize them in their flocculating and conformance applications.
⮞In September 2026, CooperVision opened The Vision Centre innovation hub in Southampton and outlined a lens pipeline that includes a next-generation silicone hydrogel monthly material. The plan shows continued investment in silicone-modified hydrogel formulations for daily and monthly lenses.
By Application, Personal Care and Hygiene Dominates the Hydrogel Market and Is Also the Fastest Growing
Personal care and hygiene leads application demand because diapers, adult incontinence pads and feminine care products consume superabsorbent hydrogels in very large quantities. Rising birth volumes in South Asia and Africa, ageing populations in Japan, China and Europe, and wider use of disposable products drive steady purchases. Brand owners seek thinner cores and lower pulp content, which raises the share of polymer per product. Sustainability programs are testing bio-based and recyclable absorbents, and cosmetic and skin patch makers are adding hydrogel sheet masks and cooling patches, which widens the consumer base beyond baby and adult care.
Personal care and hygiene is also the quickest growing application as penetration rises in emerging markets. Disposable diaper and feminine care use is still low in parts of India, Southeast Asia and Africa, and incomes are rising. Premium products with thinner cores raise polymer content per unit, and adult incontinence demand is climbing with ageing populations. Sheet masks, acne patches and cooling gels add skin care demand, while wound care, contact lenses and drug delivery grow from smaller bases at higher prices. Local production of superabsorbent polymer in Asia keeps supply close to converters and sustains volume growth.
⮞In February 2026, Alcon launched TOTAL30 Multifocal for Astigmatism in the United States, a monthly lens built on its water gradient technology. The launch shows continued demand for advanced contact lens designs among presbyopic and astigmatic wearers.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
80.81 |
|
Europe |
Germany |
20.29 |
|
Asia Pacific |
China |
46.63 |
|
Latin America |
Brazil |
51.87 |
|
Middle East & Africa |
Saudi Arabia |
27.46 |
Asia Pacific Hydrogel Market Insights
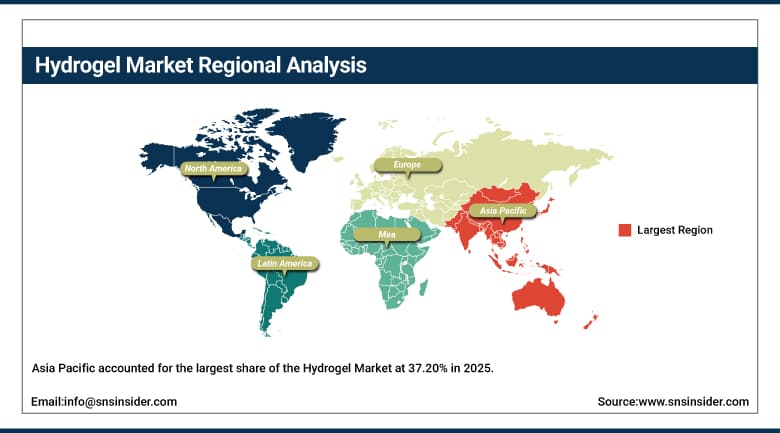
Asia Pacific accounted for the largest share of the Hydrogel Market at 37.20% in 2025, led by China, Japan and India. Large diaper, feminine care and adult incontinence volumes anchor consumption, and regional chemical groups produce superabsorbent polymers at scale. China hosts a deep supply base for acrylic acid and polymer, while Japan contributes advanced contact lens and medical gel technology. Government health programs expand wound care access, and rising incomes lift hygiene product use. Local converters export hygiene and dressing products to other regions, which keeps plant utilization high.
Asia Pacific is also projected to be the fastest growing region, with a CAGR of 7.73% during 2026-2035. India is building medical device capacity under local manufacturing incentives, and South Korea and Singapore are investing in biomaterials research. Hospitals in Southeast Asia are upgrading to advanced wound dressings as diabetes cases rise. Regulatory approvals are becoming faster in Japan and China for spacers and injectable products, although tender pricing pressure persists. Local players are moving into silicone hydrogel lenses and conductive gels for wearables, where regional electronics supply chains give them a cost edge.
⮞In March 2026, the National University of Singapore reported in Nature Sensors that a hydrogel skin interface raised the signal-to-noise ratio of a wearable ECG sensor from 5.19 dB to 37.36 dB. The result shows rising demand for conductive hydrogels in wearable electronics.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Hydrogel Market Insights
North America is the second largest region, led by the United States and supported by Canada. Mature reimbursement for advanced wound dressings, a large population with diabetes and a high rate of cancer radiotherapy keep medical hydrogel demand strong. Leading wound care, contact lens and device companies run research and manufacturing bases in the region, and new products often launch here first. Contact lens wearers prefer silicone hydrogel daily lenses, which supports premium pricing, and hospitals use hydrogel spacers and embolic systems as procedural options expand.
Regulatory and payment decisions shape adoption. The Food and Drug Administration reviews most hydrogel devices through 510(k) or premarket approval pathways, and a recent approval for an embolic system showed that new product classes can reach clinics. Canadian developers are advancing injectable depots for non-opioid pain relief with U.S. partners. Hospital value analysis committees compare dressing costs with healing time, which favors products with clear outcome data. Biotech investors fund ophthalmic and oncology hydrogels, and academic hospitals run many of the trials for new gels.
⮞In February 2026, AmacaThera of Toronto was named Life Sciences Ontario Emerging Company of the Year for its thermoresponsive injectable hydrogel depot. A Phase II trial of its lead non-opioid anesthetic, AMT-143, is planned for 2026.
Europe Hydrogel Market Insights
Europe is a large and technically advanced region, led by Germany, the United Kingdom, France and Italy. National health systems purchase advanced wound dressings through tenders, and the Medical Device Regulation demands strong clinical evidence. Leading European makers supply hydrogel dressings, gels and contact lens materials to global customers. Ageing populations in Germany and Italy increase chronic wound and incontinence cases. Research funding from Horizon Europe supports collaboration among universities, hospitals and small companies. Germany and the United Kingdom lead purchases of hydrogel dressings, while France and Italy support contact lens and hygiene volumes.
Sustainability policy influences product design. Packaging and single-use plastic rules push hygiene brands to test bio-based absorbents, and European universities lead research into degradable gels and bioinks. Tenders emphasize cost per treatment, which favors suppliers with local manufacturing and clear health economics. The Netherlands, Austria and Switzerland host start-ups that move laboratory gels toward clinics. Notified body capacity and certification delays remain a constraint for smaller firms, so partnerships with larger device makers are common routes to market. Separate UK and EU conformity routes add compliance work for exporters.
⮞In June 2025, JOANNEUM RESEARCH in Austria announced the Horizon Europe INJECTHEAL project, a three-year effort with 13 consortium partners to build an injectable self-healing hydrogel for deep chronic wounds. The project shows public funding for next-generation wound hydrogels.
MEA & Latin America Hydrogel Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. Hygiene product consumption grows with urbanization, and public and private hospitals are widening access to advanced wound dressings for diabetic patients. Regional converters import superabsorbent polymer, while local universities develop low-cost biodegradable gels from agricultural waste for irrigation. Currency swings and import duties affect prices, and registration timelines at regulators such as ANVISA influence launches. Contact lens use is rising among younger urban consumers. Brazil's large diabetic population and expanding private hospital networks support dressing demand.
In August 2025, the Universidad Autónoma de Coahuila in Mexico reported that researchers at its CIJE research center had developed an irrigation hydrogel from lechuguilla waste as a biodegradable alternative to commercial agricultural hydrogels. The next step is a trial on model plants.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates and South Africa lead demand. Gulf health budgets and high diabetes prevalence support wound care purchases, and local research centers are building advanced materials programs. Africa depends mainly on imported hygiene and medical products, so affordability and distribution limit penetration. Water scarcity creates opportunities for agricultural hydrogels in dryland farming. Hospital expansion in the Gulf states and growing medical tourism raise demand for premium dressings and surgical gels. South African private hospitals purchase premium wound products, and tender budgets shape public purchasing.
⮞In August 2025, Khalifa University in the UAE reported 4D-printed color-changing hydrogels for battery-free wearables, with an AI model classifying temperature ranges at 98.75% accuracy. The work shows regional research strength in smart hydrogels.
Market Dynamics:
Growth Drivers: Chronic Wound Burden and Expanding Medical Uses Drive Growth in the Hydrogel Market
Chronic disease is expanding the clinical use of hydrogels. Diabetes, pressure injuries and venous ulcers require moist wound care, and hydrogel dressings rehydrate dry tissue and support debridement. Ageing populations increase the number of patients with slow-healing wounds, while health systems favor dressings that reduce nursing visits. Oncology adds procedural demand, since spacers placed before prostate radiotherapy protect the rectum and embolic gels treat hypervascular tumors. Ophthalmology contributes through silicone hydrogel contact lenses and sustained-release eye implants that reduce injection frequency. Home care nursing growth also favors dressings that stay in place for several days.
Hygiene volumes provide the base for growth. Rising incomes in Asia and Africa increase diaper, feminine care and adult incontinence use, and ageing societies in Japan, China and Europe lift adult product demand. Superabsorbent polymer makers add capacity close to converters, which lowers delivered cost. In parallel, conductive hydrogels enter electrodes, patches and wearable sensors, and agriculture buyers adopt water-retaining gels in dry regions. These parallel uses reduce dependence on any single end market and support consistent volume growth across economic cycles. Regional capacity expansions in India and Southeast Asia improve local availability and shorten delivery times.
⮞In August 2026, Gelion Care, a spin-off of Eindhoven University of Technology, introduced a hydrogel for hard-to-heal wounds, mainly diabetic foot ulcers, that releases nitric oxide generated by cold plasma. A pilot with 20 participants reported no side effects, although the study did not measure faster healing.
Restraints: Performance Limits, Regulatory Burden and Sustainability Pressure Restrain Growth in the Hydrogel Market
Technical limits still restrict clinical use. Many hydrogels have low mechanical strength, limited adhesion to wet tissue and unpredictable degradation, which complicates use in load-bearing or long-term implants. Scaling laboratory formulations to sterile and repeatable manufacturing is difficult, and few hydrogel products have won full regulatory approval for implantable or drug-delivery uses. Clinical trials are costly and long, so small developers depend on partners for funding and market access. Reimbursement for advanced dressings varies widely, which slows uptake in price-sensitive markets.
Competition and regulation add further pressure. Foam, alginate and hydrocolloid dressings compete with hydrogel sheets on price and exudate handling, and hospital buyers often choose by cost per dressing. Microplastic and landfill rules scrutinize non-degradable superabsorbent polymers in hygiene products, while energy-intensive polymer production faces environmental, social and governance review. Acrylic acid prices fluctuate with propylene markets, and notified body capacity in Europe can lengthen approval timelines for new device variants. Single-use hygiene waste is also drawing municipal scrutiny in several countries, which pushes brands toward costly redesigns.
⮞In March 2026, researchers at He University and Xi'an Jiaotong University in China published a review noting that understanding of how rheology links to biocompatibility, degradation and scalable manufacturing is insufficient for clinical translation of hydrogels. The review cited only three approved hydrogel products as examples.
Opportunities: Smart Hydrogels, Injectable Therapies and Biodegradable Grades Create Opportunities in the Hydrogel Market
Smart and responsive hydrogels open high-value markets. Conductive and stimuli-responsive gels can sense glucose, pH, temperature and strain, which suits wearable monitors, soft robotics and closed-loop drug delivery. Injectable systems that gel at body temperature enable minimally invasive treatment, from submucosal cushions for endoscopic surgery to depots that release non-opioid anesthetics over days. Companies that secure regulatory clearance for a first-in-class hydrogel can build protected positions with premium pricing. Licensing and partnership deals with large device companies provide funding and distribution that early-stage developers lack.
Biodegradable gels made from plant, seaweed and agricultural waste meet demand from farms, cosmetic brands and hygiene makers facing waste rules. Three-dimensional bioprinting and tissue engineering use hydrogel bioinks for cell-laden constructs, and research hospitals are moving some products toward clinical studies. Contract manufacturers that offer electron-beam cross-linking, sterile filling and regulatory support can serve start-ups and large device firms alike, which widens the supplier base. Lower-cost production routes would let these products reach hospitals in lower-income countries as well.
⮞In March 2026, IIT Gandhinagar developed a plant-based injectable hydrogel based on diglycerol monostearate as a longer-lasting submucosal cushion for colorectal polyp removal. The work remains before human trials but shows how natural gels may support minimally invasive surgery.
Recent Developments:
-
In September 2026, Boston Scientific received U.S. FDA 510(k) clearance for its SpaceOAR Flex hydrogel spacer, placed between the prostate and rectum during prostate radiotherapy. The clearance extends the company's spacer portfolio and gives radiation oncologists another option for protecting rectal tissue.
-
In February 2026, Ocular Therapeutix reported positive topline results from the Phase 3 SOL-1 trial of AXPAXLI, a bioresorbable intravitreal hydrogel implant that releases axitinib, in neovascular age-related macular degeneration. The result supports the case for sustained-release hydrogels that reduce the number of eye injections.
-
In August 2025, Instylla received U.S. FDA premarket approval for the Embrace Hydrogel Embolic System, a liquid embolic used to treat hypervascular tumors in peripheral arteries. The approval opens a new interventional radiology category for hydrogel products.
-
In July 2026, Vivos Inc reported that the U.S. FDA approved a feasibility investigational device exemption for RadioGel, a yttrium-90 hydrogel brachytherapy device, enabling a first-in-human study of five patients at Mayo Clinic. The program tests a hydrogel as a carrier for localized radiation in solid tumors.
Hydrogel Market Key Players:
-
Smith & Nephew plc
-
Alcon Inc.
-
Boston Scientific Corporation
-
Ocular Therapeutix, Inc.
-
NEXGEL, Inc.
-
Coloplast A/S
-
Johnson & Johnson Vision Care, Inc.
-
CooperVision, Inc.
-
Bausch + Lomb Corporation
-
Paul Hartmann AG
-
Axelgaard Manufacturing Co., Ltd.
-
Katecho, LLC
-
Sekisui Kasei Co., Ltd.
-
Sonoma Pharmaceuticals, Inc.
-
Polymer Science, Inc.
-
Convatec Group plc
-
Solventum Corporation
-
B. Braun SE
-
Menicon Co., Ltd.
-
Teikoku Pharma USA, Inc.
Hydrogel Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 33.80 Billion |
| Market Size by 2035 | USD 65.44 Billion |
| CAGR | CAGR of 6.83% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Raw Material (Synthetic, Natural, and Hybrid) • By Form (Amorphous, Semi-Crystalline, and Crystalline) • By Composition (Polyacrylate, Polyacrylamide, Silicone-Modified, Agar-Based, and Others) • By Application (Personal Care and Hygiene, Wound Care, Drug Delivery, Contact Lenses, Agriculture, Tissue Engineering, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Smith & Nephew plc, Alcon Inc., Boston Scientific Corporation, Ocular Therapeutix, Inc., NEXGEL, Inc., Coloplast A/S, Johnson & Johnson Vision Care, Inc., CooperVision, Inc., Bausch + Lomb Corporation, Paul Hartmann AG, Axelgaard Manufacturing Co., Ltd., Katecho, LLC, Sekisui Kasei Co., Ltd., Sonoma Pharmaceuticals, Inc., Polymer Science, Inc., Convatec Group plc, Solventum Corporation, B. Braun SE, Menicon Co., Ltd., Teikoku Pharma USA, Inc. |

Frequently Asked Questions
Key players include Smith & Nephew, Alcon, Boston Scientific, Ocular Therapeutix, NEXGEL, Coloplast, Johnson & Johnson Vision Care, CooperVision, Bausch + Lomb, Paul Hartmann, Axelgaard, Katecho, Sekisui Kasei, Sonoma Pharmaceuticals, Polymer Science, Convatec, Solventum, B. Braun, Menicon and Teikoku Pharma.
Key opportunities include smart and conductive hydrogels for wearables, injectable depots and spacers for minimally invasive therapy, biodegradable grades for agriculture and hygiene, and hydrogel bioinks for tissue engineering.
Rising chronic wound burden, expanding oncology and ophthalmic uses and steady hygiene product demand are the main growth factors, supported by new regulatory approvals for hydrogel devices.
By Application, the Personal Care and Hygiene segment dominated the market in 2025 with an estimated 53.85% share, supported by large superabsorbent polymer use in diapers, incontinence products and feminine care.
Asia Pacific dominated the market with a share of 37.20% in 2025, driven by large hygiene product volumes, local superabsorbent polymer production and expanding healthcare access.
