
Hydrogen Gas Sensor Market Report Scope & Overview:
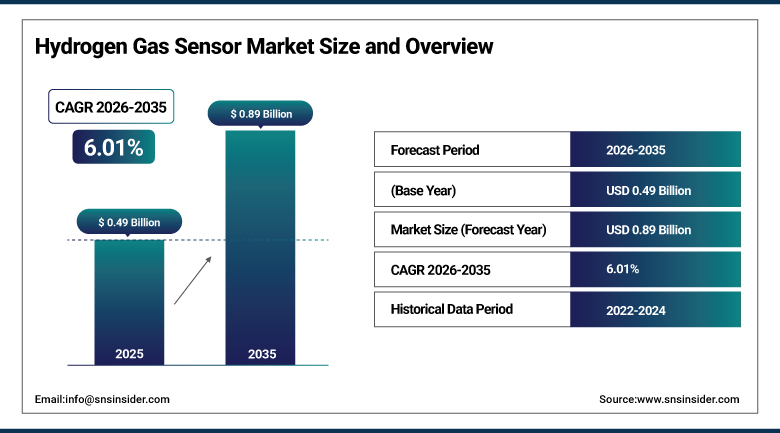
The Hydrogen Gas Sensor Market size was valued at USD 0.49 Billion in 2025 and is expected to reach USD 0.89 Billion by 2035, growing at a CAGR of 6.01% from 2026-2035.
Hydrogen gas detectors help to detect, monitor, and measure hydrogen gas concentration in different environments such as industrial, commercial, transportations, and research applications, to ensure its safe storage, usage, and transport as hydrogen gains increased use around the globe. As hydrogen gas increases in demand as a source of energy in place of fuel, there is increased need for hydrogen detectors in order to reduce any risk of leakage. There are strict rules about the safety of hydrogen and industries using hydrogen are required to have approved detection systems installed in their premises, which creates consistent baseline demand from industries in chemical processing, oil and gas, and semiconductor industries. The adoption of silicon carbide and gallium nitride sensors coupled with increasing awareness about pollution in industries makes it an essential enabler for energy transition.
⮞In May 2025, Honeywell International Inc. introduced a new Hydrogen Leak Detector capable of detecting leaks as low as 50 parts per million using advanced thermal conductivity sensing. The company said the solution is designed to identify microscopic hydrogen leaks in real time, helping ensure the safety of hydrogen-powered systems across industrial and transportation applications.
To Get more information Hydrogen Gas Sensor Market - Request Free Sample Report
Hydrogen Gas Sensor Market Trends
-
Rising integration of silicon carbide and gallium nitride materials improving sensor sensitivity and durability.
-
Growing deployment of MEMS-based sensors supporting miniaturisation and IoT connectivity.
-
Expanding hydrogen refueling station infrastructure driving demand for certified leak detection systems.
-
Increasing adoption of portable hydrogen sensors supporting field inspection and mobile leak detection.
-
Rising government hydrogen strategy investment across Europe reinforcing regional demand growth.
-
Growing integration of AI-based analytics improving detection accuracy and response time across installed systems.
U.S. Hydrogen Gas Sensor Market Size Outlook
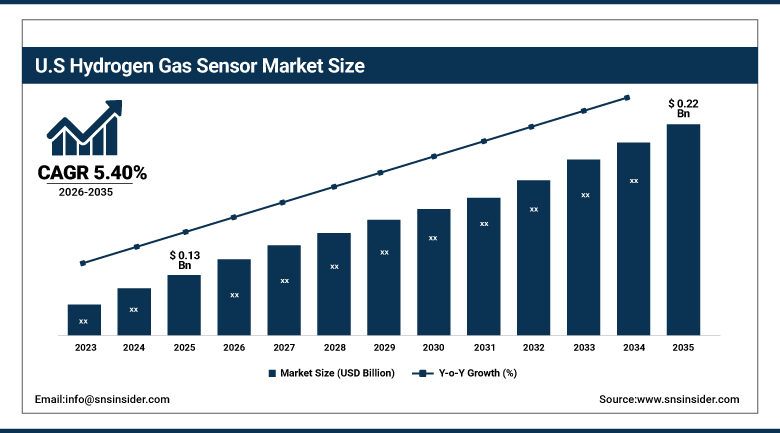
The U.S. Hydrogen Gas Sensor Market was valued at USD 0.13 Billion in 2025 and is expected to reach USD 0.22 Billion by 2035, growing at a CAGR of 5.40% from 2026-2035.
The rising demand for hydrogen fuel is driven by both the increasing hydrogen production and the growing use of fuel cell vehicles, as well as strict work place safety requirements for the installation of certified gas detection systems in chemical, oil and gas, and industrial plants. The leading domestic producers are developing new-generation sensors that provide faster and more accurate detection.
⮞In January 2025, MSA Safety Incorporated introduced the SENTRY io Controller, a gas and flame monitoring system designed to support MSA gas and flame detectors while lowering costs and offering data analytics that help protect workers and facilities. The launch reflects continued domestic manufacturer investment in integrated monitoring platforms combining sensor hardware with analytics capability.
Hydrogen Gas Sensor Market Segment Analysis
-
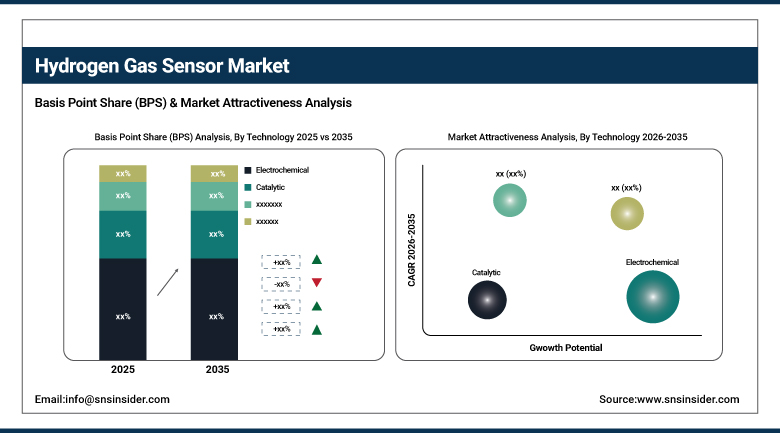
By Technology, the Electrochemical segment dominated the market with a 42.60% share in 2025, while the MEMS segment is the fastest growing with a CAGR of 8.60% during 2026-2035.
-
By Application, the Industrial Safety segment dominated the market with a 34.60% share in 2025, while the Hydrogen Refueling Stations segment is the fastest growing with a CAGR of 9.80% during 2026-2035.
-
By End User, the Industrial Manufacturing segment dominated the market with a 36.60% share in 2025, while the Automotive segment is the fastest growing with a CAGR of 9.20% during 2026-2035.
-
By Sensor Type, the Fixed segment dominated the market with a 58.60% share in 2025, while the Portable segment is the fastest growing with a CAGR of 8.40% during 2026-2035.
By Technology, Electrochemical Dominates the Market and MEMS Grows Fastest
Electrochemical sensing dominated the market in 2025. This technology continues to deliver a favourable balance of sensitivity, selectivity, and cost efficiency that makes it the practical default choice across the majority of industrial hydrogen detection applications, where facilities require reliable, continuous monitoring without the premium cost that more specialised sensing technologies typically command. This established manufacturing base and broad application compatibility continues to sustain electrochemical sensing's position as the largest technology category within the broader hydrogen gas sensor market.
MEMS-based sensing is projected to be the fastest-growing technology over the forecast period. Continued miniaturisation and IoT integration capability continues to make this technology increasingly attractive for space-constrained and connected monitoring applications, as facilities increasingly seek sensors that can integrate seamlessly with broader industrial IoT platforms while occupying minimal physical footprint. This capability continues to position MEMS-based sensing for sustained above-market growth relative to the broader electrochemical-dominated technology mix.
⮞On September 29, 2026, India’s Technology Development Board announced ₹37.51 crore in support for Multi Nano Sense Technologies to advance a MEMS-based multi-gas sensing platform with an application-specific front-end system-on-chip.
By Application, Industrial Safety Dominates the Market and Hydrogen Refueling Stations Grows Fastest
Industrial safety applications dominated the market in 2025. Chemical processing plants, oil and gas facilities, and semiconductor manufacturing sites worldwide continue relying on certified hydrogen detection systems to comply with strict occupational safety regulation, a compliance requirement that continues to generate sustained, recurring demand for both new installations and periodic equipment replacement across established industrial facilities.
Hydrogen refueling stations are projected to be the fastest-growing application over the forecast period. Rapidly expanding fuel cell vehicle infrastructure continues to require certified leak detection systems at every new refueling station, and as governments worldwide continue funding hydrogen infrastructure buildout to support clean transportation goals, this application category continues to capture an increasing share of overall sensor demand relative to the broader, industrial-safety-dominated application mix.
⮞On July 29, 2026, India’s Ministry of New and Renewable Energy announced 12 pilot projects involving 70 hydrogen-powered vehicles and 16 hydrogen refueling stations across 21 routes. The planned infrastructure expansion creates potential demand for hydrogen leak detection and station-safety monitoring systems.
By End User, Industrial Manufacturing Dominates the Market and Automotive Grows Fastest
Industrial manufacturing dominated the market in 2025. The sheer breadth of manufacturing facilities that use or generate hydrogen as part of their production processes, spanning chemical synthesis, metal treatment, and electronics fabrication, continues to anchor industrial manufacturing as the largest end-user category across the broader hydrogen gas sensor market.
Automotive is projected to be the fastest-growing end-user category over the forecast period. Expanding fuel cell vehicle adoption continues to require hydrogen sensors integrated directly into vehicle safety systems, alongside sensors deployed across the broader refueling and maintenance infrastructure supporting these vehicles, positioning automotive for sustained above-market growth relative to the broader manufacturing-dominated end-user mix.
⮞On June 16, 2026, Sensirion announced global availability of its STC42A automotive hydrogen sensor for detecting hydrogen leaks and supporting early thermal-runaway detection in electric-vehicle battery systems. The sensor uses thermal-conductivity measurement and an automotive-qualified digital interface.
By Sensor Type, Fixed Dominates the Market and Portable Grows Fastest
Fixed sensors dominated the market in 2025. Facility-wide continuous monitoring installations continue to represent the primary deployment model across industrial and transportation infrastructure, as fixed sensors provide the uninterrupted, always-on detection capability that safety-critical applications require without depending on manual deployment or battery management.
Portable sensors are projected to be the fastest-growing sensor type over the forecast period. Rising demand for mobile leak detection and field inspection capability continues to drive adoption of handheld and wearable hydrogen detection devices, particularly among maintenance technicians and safety inspectors requiring flexible, on-demand monitoring capability across facilities not covered by fixed installations.
⮞On August 14, 2025, India’s Department of Science and Technology highlighted research into a miniaturized, low-power sensor capable of detecting trace hydrogen at room temperature. The research addresses key requirements for compact, portable and on-chip gas detection, although it represents technology development rather than a confirmed commercial product launch.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Germany |
28.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Hydrogen Gas Sensor Market Insights
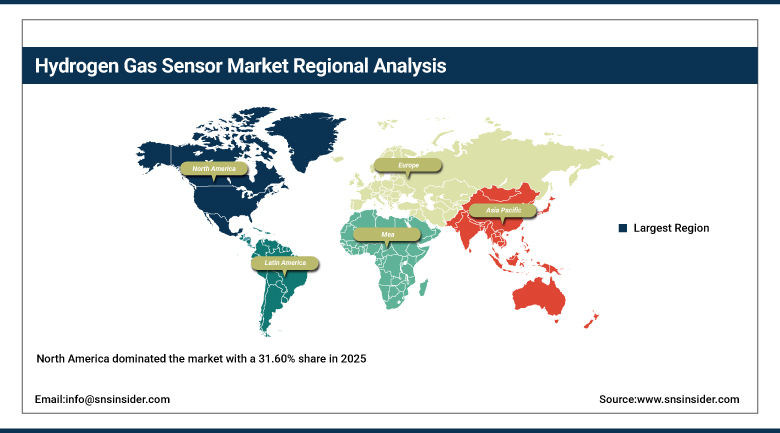
North America dominated the market with a 31.60% share in 2025. Strict occupational safety regulation, sustained industrial hydrogen production activity, and a concentration of leading sensor manufacturers headquartered within the region continue to anchor this leadership position across both established industrial applications and emerging fuel cell vehicle infrastructure.
Canada contributes incremental regional demand as its own industrial and energy sectors continue to expand hydrogen adoption. Continued domestic investment in hydrogen refueling infrastructure and portable detection technology is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms trails Europe's accelerating regulatory-driven adoption.
⮞In 2025, the U.S. Department of Energy continued highlighting the need for lower-cost, more-sensitive hydrogen leak detection, including research into sensors capable of measuring very small hydrogen losses.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Hydrogen Gas Sensor Market Insights
Europe is projected to be the fastest-growing region over the forecast period. Stringent regulations aimed at reducing carbon emissions, combined with ambitious national hydrogen strategies implemented by countries including France and Germany, continue to accelerate regional demand for certified hydrogen detection technology across both industrial and transportation applications.
Germany's substantial industrial base and aggressive hydrogen economy investment continue to anchor regional demand, while France's own national hydrogen strategy continues to drive parallel infrastructure investment. The United Kingdom and other major European markets contribute additional regional scale as national governments continue prioritising hydrogen as a cornerstone of broader decarbonisation policy, positioning Europe as the fastest-growing regional market through the forecast period.
⮞On July 21, 2026, Fraunhofer IPM announced the GRID_FUSE research project to develop sensor arrays for continuous hydrogen-purity monitoring, targeting detection of impurities at sub-parts-per-million levels.
Asia Pacific Hydrogen Gas Sensor Market Insights
Asia Pacific represents a significant share of the global market, anchored by China's substantial industrial manufacturing base and growing domestic hydrogen production capacity. Japan and South Korea continue contributing meaningful regional demand through established fuel cell vehicle programs and continued government investment in hydrogen infrastructure.
India's expanding industrial sector and growing interest in hydrogen as an alternative energy source continue to contribute incremental regional growth. Continued regional manufacturing capacity expansion is expected to sustain steady growth across the broader Asia Pacific market through the forecast period.
⮞In its 2026 Global Hydrogen Review, the International Energy Agency reported that China accounted for nearly three-quarters of new global electrolyser installations in 2025.
MEA & Latin America Hydrogen Gas Sensor Market Insights
The Middle East & Africa market is supported by growing industrial and energy sector investment across the United Arab Emirates and Saudi Arabia, where regional governments continue exploring hydrogen as part of broader economic diversification strategies alongside sustained oil and gas sector safety monitoring demand.
Latin America's market is anchored by Brazil, where a growing domestic industrial sector sustains steady demand for hydrogen detection technology. Mexico contributes further incremental growth as regional industrial safety standards continue to align with international regulatory frameworks.
⮞On September 22, 2026, Brazil’s Ministry of Finance outlined regulations implementing the country’s low-emissions hydrogen framework, including certification and incentive mechanisms for qualifying projects.
Market Dynamics
Growth Drivers: Hydrogen Economy Expansion and Safety Regulation
The increasing use of hydrogen as an alternate fuel is considered the main growth factor since the shift towards the cleaner energy source is still increasing the need for hydrogen sensors that can guarantee safe storage, transport, and consumption in various applications across the world.
Another important growth factor is the need for stringent safety regulations. Industries using or producing hydrogen continue being required by governments and regulatory authorities to install certified gas detection systems. Increased environmental concerns, seen through the rise in carbon dioxide emissions around the world, continue to push governments to promote hydrogen as a cleaner option, ensuring demand for sensors in hydrogen applications.
⮞In July 2026, India announced 12 hydrogen-mobility pilot projects covering 70 hydrogen-powered vehicles and 16 refueling stations. The planned rollout reinforces the importance of hydrogen leak detection and safety monitoring across refueling and vehicle infrastructure.
Restraints: High Sensor Costs and Calibration Requirements
High sensor costs remain a genuine restraint, as advanced hydrogen detection technology incorporating silicon carbide and gallium nitride materials continues to command premium pricing that smaller facilities and price-sensitive markets can struggle to justify against limited safety equipment budgets.
Ongoing calibration and maintenance requirements present a further restraint, as hydrogen sensors require periodic recalibration to maintain detection accuracy, adding recurring operational cost and complexity that continues to factor into facility total cost of ownership calculations across long deployment lifecycles.
Opportunities: Fuel Cell Vehicle Infrastructure and Advanced Materials Innovation
The continued development of the fuel cell vehicle infrastructure is a very promising area, since companies that will be able to provide affordable and reliable sensors for fueling stations and the safety system of vehicles will be able to benefit from the growing number of vehicles.
The development of silicon carbide and gallium nitride as a material for manufacturing the sensors is another direction that can bring more profit to the business of a manufacturer, as its clients will look for better sensitivity and reliability of their sensors.
⮞On September 29, 2026, India’s Technology Development Board committed ₹37.51 crore to support the advancement of a MEMS-based multi-gas sensor and signal-processing platform. The project highlights opportunities for compact, low-power sensors with potential applications in hydrogen leak detection, industrial process monitoring and connected safety systems.
Recent Developments:
-
In June 2026, Sensirion announced global availability of its STC42A Automotive H₂ Sensor, designed for hydrogen detection in EV battery thermal-runaway monitoring and hydrogen-leak applications. The automotive-qualified sensor uses thermal-conductivity measurement and an I²C digital interface.
-
In May 2025, Honeywell launched its Hydrogen Leak Detector (HLD) for industrial equipment, power generators, and hydrogen-powered vehicles. The thermal-conductivity sensor can detect hydrogen leaks as small as 50 ppm and is designed for long-term operation without regular manual calibration.
-
In November 2025, H2scan launched its next-generation HY-GUARD hydrogen sensor for battery-room safety applications. The solution is designed to detect hydrogen buildup in battery rooms and critical-power facilities such as data centers, telecommunications sites, and industrial facilities.
Hydrogen Gas Sensor Companies are:
-
Honeywell International Inc.
-
Nissha FIS, Inc.
-
Amphenol Corporation
-
Zhengzhou Winsen Electronics Technology Co., Ltd.
-
Aeroqual Limited
-
City Technology Ltd. (Honeywell)
-
Nemoto & Co., Ltd.
-
NGK Spark Plug Co., Ltd.
-
Makel Engineering, Inc.
-
Toshiba Corporation
-
MSA Safety Incorporated
-
Insplorion AB
-
NTM Sensors
-
Hydrogen Sense Technology
-
Suzhou TaKrMEMS
-
ProSense Technologies
-
Draeger Safety, Inc.
-
New Cosmos Electric Co., Ltd.
Hydrogen Gas Sensor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.49 Billion |
| Market Size by 2035 | USD 0.89 Billion |
| CAGR | CAGR of 6.01% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Technology (Electrochemical, Catalytic, MEMS, and Solid-State) • by Application (Industrial Safety, Hydrogen Refueling Stations, Fuel Cell Vehicles, and Chemical Processing) • by End User (Industrial Manufacturing, Automotive, Energy & Utilities, and Aerospace) • by Sensor Type (Fixed and Portable) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Honeywell International Inc., Figaro Engineering Inc., Nissha FIS, Inc., Amphenol Corporation, Zhengzhou Winsen Electronics Technology Co., Ltd., Aeroqual Limited, City Technology Ltd. (Honeywell), Membrapor AG, Nemoto & Co., Ltd., NGK Spark Plug Co., Ltd., Makel Engineering, Inc., Toshiba Corporation, MSA Safety Incorporated, Insplorion AB, NTM Sensors, Hydrogen Sense Technology, Suzhou TaKrMEMS, ProSense Technologies, Draeger Safety, Inc., New Cosmos Electric Co., Ltd. |
Frequently Asked Questions
Key players include Honeywell International Inc., Figaro Engineering Inc., Nissha FIS, Inc., Amphenol Corporation, and Zhengzhou Winsen Electronics Technology Co., Ltd., among other sensor manufacturers.
Continued expansion of fuel cell vehicle infrastructure and continued advancement in silicon carbide and gallium nitride sensor materials represent the primary opportunities for manufacturers.
Growth is primarily driven by rising adoption of hydrogen as an alternative fuel, combined with strict safety regulations requiring certified detection systems.
By Technology, Electrochemical dominated the market with a 42.60% share in 2025, reflecting its favourable balance of sensitivity, selectivity, and cost efficiency.
North America dominated the market with a 31.60% share in 2025, supported by strict occupational safety regulation and a concentration of leading sensor manufacturers.
