
Immunoassay Analyzers Market Report Scope & Overview:
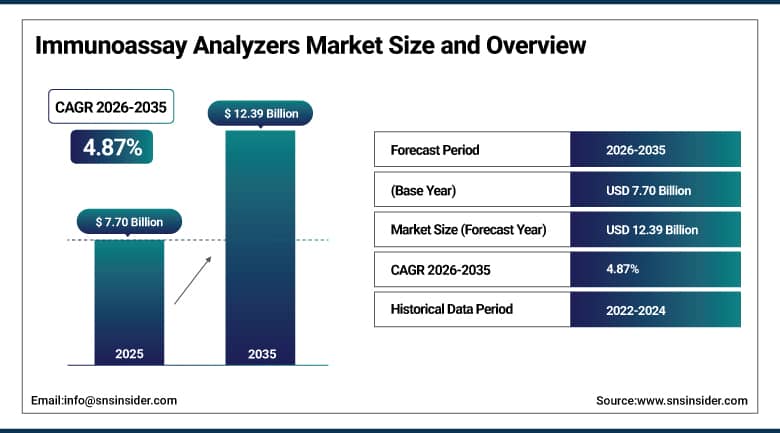
The Immunoassay Analyzers Market was valued at USD 7.70 Billion in 2025 and is expected to reach USD 12.39 Billion by 2035, growing at a CAGR of 4.87% from 2026-2035.
The Immunoassay Analyzers Market covers automated instruments that measure hormones, tumor markers, cardiac markers, infectious disease antigens, and antibodies in blood and other samples. Hospitals and reference laboratories depend on these analyzers for high volume routine testing. Demand is shaped by chronic disease, infectious disease screening, and the need for fast, accurate results. Manufacturers compete on throughput, menu breadth, and reagent supply. Integration with laboratory automation tracks and software is a growing priority. Placement of instruments under reagent rental contracts creates recurring revenue and long customer relationships. Regulatory change in Europe and price reform in China are reshaping strategies. Service contracts and software upgrades add further income over the life of each installed instrument.
⮞In July 2026, the World Health Organization reported an estimated 41.0 million people living with HIV at the end of 2025. Screening and monitoring of chronic infections on this scale keeps demand for immunoassay testing steady.
To Get More Information On Immunoassay Analyzers Market - Request Free Sample Report
Immunoassay Analyzers Market Trends
- Integration of immunoassay analyzers with total laboratory automation
- Growth of blood based biomarkers for neurological and oncology testing
- Compact point of care analyzers for decentralized testing
- Local manufacturers in China expanding into export markets
- Middleware and artificial intelligence for result review and quality control
U.S. Immunoassay Analyzers Market Outlook
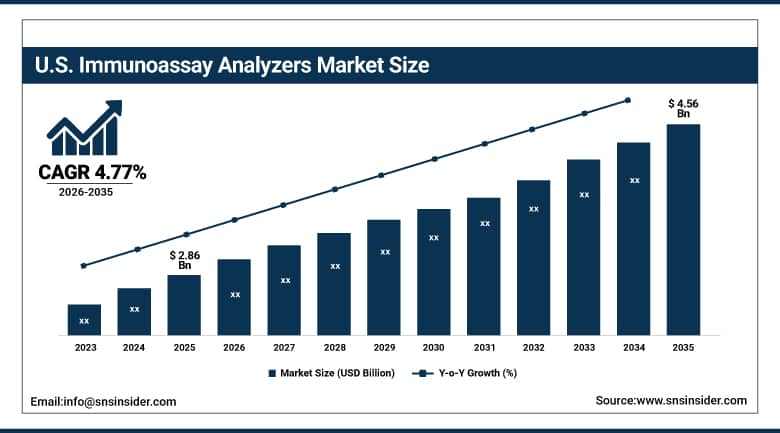
The U.S. Immunoassay Analyzers Market was valued at USD 2.86 Billion in 2025 and is expected to reach USD 4.56 Billion by 2035, growing at a CAGR of 4.77% from 2026-2035.
The U.S. immunoassay analyzers market is the biggest national market because it has extensive distribution of hospitals, reference labs, and physician office labs. Big health systems perform testing on high-throughput platforms, whereas smaller locations rely on smaller immunoassay analyzers. The manufacturers gain from the FDA approval of new assays, including Alzheimer's blood tests and sensitive cardiac markers. The pressure on reimbursement and shortage of lab personnel force buyers to adopt more automation and reagent agreements reducing cost per test. Competition between international players in the industry is tough, and prices are well-controlled. Group purchasing organizations influence the choice of suppliers for national contracts as well.
⮞In September 2026, the Centers for Medicare & Medicaid Services listed 301,284 registered CLIA laboratories in the United States. A testing base this broad creates demand for analyzers across every size of laboratory.
Immunoassay Analyzers Market Segment Analysis
- By Product, the Standalone and Integrated Systems segment dominated the Immunoassay Analyzers Market with approximately 46.72% share in 2025, while the Portable and Point of Care Analyzers segment is the fastest growing with a CAGR of approximately 9.33%.
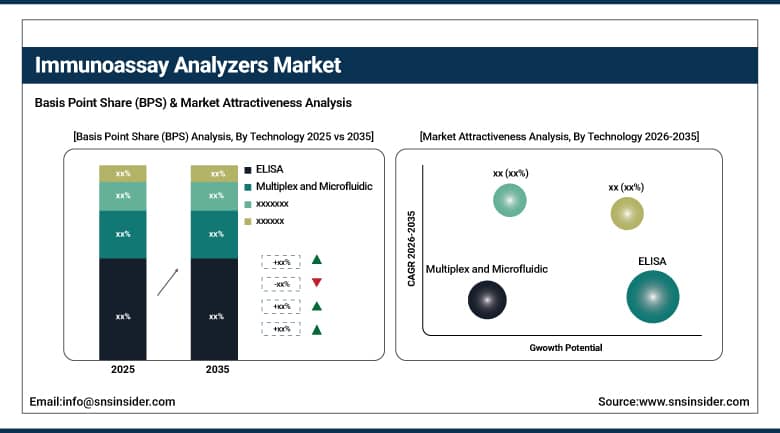
- By Technology, the ELISA segment dominated the Immunoassay Analyzers Market with approximately 63.42% share in 2025, while the Multiplex and Microfluidic segment is the fastest growing with a CAGR of approximately 7.91%.
- By Application, the Infectious Disease segment dominated the Immunoassay Analyzers Market with approximately 43.12% share in 2025, while the Oncology segment is the fastest growing with a CAGR of approximately 9.50%.
- By End User, the Hospital Laboratories segment dominated the Immunoassay Analyzers Market with approximately 54.67% share in 2025, while the Veterinary Clinics and Laboratories segment is the fastest growing with a CAGR of approximately 7.71%.
By Technology, ELISA Dominates the Immunoassay Analyzers Market and Multiplex and Microfluidic Grows Fastest
ELISA based methods lead because they are well established, flexible, and cost effective across a wide range of analytes. Laboratories have validated assays and trained staff for the format, and automated ELISA systems handle large batches. Chemiluminescence immunoassays hold a very large position in hospital laboratories and are growing in parallel because of high sensitivity and wide dynamic range. Immunofluorescence and radioimmunoassay serve more specialized needs. Reagent and kit suppliers offer extensive menus, which supports continued use of established platforms. Manual and semi automated ELISA kits also remain common in research and smaller laboratories.
Multiplex and microfluidic technologies are growing fastest because they measure several analytes from a small sample. Panels for autoimmune disease, allergy, cytokines, and neurological markers benefit from this capability. Microfluidic cartridges reduce reagent consumption and enable compact analyzers. Laboratories value the efficiency of running a panel in one step, and clinicians gain a richer picture from a single sample. Higher sensitivity formats are also enabling blood based tests for conditions once detected only with invasive procedures. Development costs are higher, which keeps these technologies concentrated among large suppliers. Regulatory pathways for multiplex claims are becoming clearer, which helps product planning.
⮞In April 2024, Mindray launched its CL-2600i chemiluminescence immunoassay analyzer, which processes up to 240 tests per hour for mid volume laboratories. Compact high speed systems are widening the customer base beyond the largest hospitals.
By Product, Standalone and Integrated Systems Dominates the Immunoassay Analyzers Market and Portable and Point of Care Analyzers Grows Fastest
Standalone and integrated systems lead because hospital and reference laboratories need high throughput platforms that run many assays on one instrument. Suppliers place these analyzers under reagent rental agreements, which tie customers to long term consumable supply. Modular designs let laboratories add capacity as volumes grow, and integration with automation tracks cuts manual handling. Broad menus covering hormones, tumor markers, infectious disease, and cardiac markers reduce the number of platforms a laboratory must run. Service networks and uptime guarantees strengthen supplier positions. Training programs for technologists and application specialists improve instrument utilization.
Portable and point of care analyzers are growing fastest as testing moves closer to patients. Emergency departments, clinics, and remote sites want results in minutes without a central laboratory. Compact cartridge based systems now deliver quantitative results for cardiac markers, hormones, and infectious disease antigens. Mid size benchtop analyzers also gain share in smaller hospitals and physician office laboratories that cannot justify large systems. Connectivity features allow results to flow into electronic records. Vendors that offer both high volume and compact platforms can serve every customer tier. Battery powered and handheld readers extend these tests to ambulances and field clinics.
⮞In May 2023, Beckman Coulter unveiled its DxI 9000 immunoassay analyzer, which runs up to 215 tests per hour per square meter and cuts annual maintenance routines by up to 96%. Gains in efficiency like this are central to purchasing decisions for large laboratories.
By Application, Infectious Disease Dominates the Immunoassay Analyzers Market and Oncology Grows Fastest
Infectious disease testing leads because immunoassays are the standard tool for screening blood donations and diagnosing HIV, hepatitis, syphilis, and respiratory infections. Public health programs and blood banks run very high volumes, and reagent supply contracts are large. Prenatal screening and transplant testing add further demand. Outbreaks raise testing quickly, and laboratories keep capacity to respond. The need to confirm and monitor chronic infections keeps analyzers busy throughout the year. Large suppliers focus heavily on this menu. Antibody and antigen tests for emerging pathogens can be developed quickly on existing platforms.
Oncology is the most rapidly advancing market with increasing applications of tumor markers, companion diagnostics, and blood-based cancer testing. Prostate, breast, ovarian, and colorectal markers are used for risk prediction and monitoring after diagnosis. More recent markers are involved in selecting therapy options and detecting early recurrence. Testing of endocrine glands, cardiological issues, and autoimmune diseases remains a significant stable market due to the prevalence of diabetes, thyroid disorders, and cardiovascular diseases. Neurology is one of the promising markets with the development of plasma biomarkers for Alzheimer’s disease. Panel-based testing of markers is increasing test utilization.
By End User, Hospital Laboratories Dominates the Immunoassay Analyzers Market and Veterinary Clinics and Laboratories Grows Fastest
Hospital laboratories lead because they handle the largest and most varied testing volumes, including emergency, inpatient, and outpatient samples. They run immunoassay analyzers around the clock for cardiac markers, hormones, and infectious disease tests. Purchasing decisions are made through multi year contracts that include instruments, reagents, and service. Large hospitals invest in automation tracks that connect several analyzers. Independent diagnostic laboratories form the second large group and operate high volume central facilities that benefit from scale. Accreditation requirements push these laboratories to maintain rigorous quality control programs.
Veterinary clinics and laboratories are growing fastest from a smaller base as pet ownership and spending on animal health rise. Practices adopt compact analyzers for hormone, infectious disease, and cardiac testing in dogs and cats. Livestock and food safety testing also use immunoassay formats. Research and academic laboratories remain steady buyers for studies and biomarker discovery. Pharmaceutical firms use analyzers in clinical trials. Suppliers adapt reagents and software for veterinary use, which opens a distinct customer group with different purchasing habits. Pet insurance coverage is also encouraging owners to approve diagnostic tests.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
88.60% |
|
Europe |
Germany |
27.35% |
|
Asia Pacific |
China |
42.18% |
|
Latin America |
Brazil |
49.62% |
|
Middle East & Africa |
Saudi Arabia |
30.47% |
North America Immunoassay Analyzers Market Insights
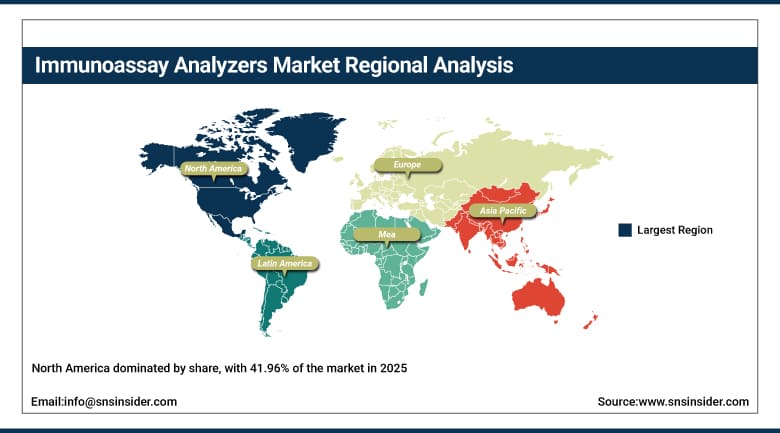
North America dominated by share, with 41.96% of the market in 2025, supported by a large installed base of hospital and reference laboratory analyzers, strong healthcare spending, and rapid adoption of new assays. The United States generates most regional demand, and Canada adds activity through provincial laboratory networks. Consolidation of laboratory services creates large purchasing groups that negotiate system wide contracts. Vendors compete on automation, connectivity, and menu breadth, and they invest in service networks that keep analyzers running. Academic medical centers add to demand through research programs and specialty testing services.
Regulatory clearances keep the pipeline active. Recent approvals include blood tests for neurological disease and high sensitivity cardiac assays, which expand the number of tests per instrument. Staff shortages push laboratories toward automation and remote monitoring. Reimbursement reform places pressure on pricing, so buyers seek lower cost per test and flexible contracts. Physician office and urgent care settings add demand for compact analyzers. Strong research activity in academic medical centers supports the introduction of new biomarkers and the validation of laboratory developed tests. Vendors also invest in cybersecurity features that hospitals now require from connected instruments.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Immunoassay Analyzers Market Insights
Europe holds the second largest position, led by Germany, the United Kingdom, France, Italy, and Spain. Public hospital laboratories purchase through tenders that favor reliable supply, strong service, and competitive reagent pricing. Consolidation of laboratories into regional hubs raises average analyzer size. The in vitro diagnostic regulation has raised the bar for documentation and clinical evidence, and manufacturers have invested in certification of their assay portfolios. Joint procurement across regions is becoming more common as health systems seek savings.
Aging population and increasing chronic diseases are driving constant testing volumes. Germany and France are taking the lead in high throughput systems, whereas in the southern and eastern regions, the mid-range instruments are used. Chinese companies are entering the European market with certified instruments and reasonable prices, thus posing additional competition for existing brands. Automation and IT solutions are common in the region, and there is a trend of connecting analyzers to the middleware system. Budget restrictions in public sector hamper the process of platform replacement, however, investments in modernization increase access to new platforms.
⮞In May 2026, the Dutch health inspectorate stated that the transition for Class D legacy devices under the in vitro diagnostic regulation ends on 31 December 2027, with Class C ending in 2028. Fixed deadlines like these shape certification spending across the industry.
Asia Pacific Immunoassay Analyzers Market Insights
Asia Pacific is the fastest growing region with an expected CAGR of 6.92% from 2026 to 2035, led by China, India, Japan, South Korea, and Australia. Expanding hospital networks, rising incomes, and public health programs are lifting test volumes. China hosts large local manufacturers that supply chemiluminescence analyzers at competitive prices, and some are expanding exports. Government procurement reform has pressed prices, which pushes suppliers toward efficiency and local production. Japan maintains a mature market with strong local brands. Training of laboratory staff and distributor support are important for rapid expansion in smaller cities.
India remains one of the fast-growing markets due to the government’s push towards making diagnostic tests available at district hospitals and community health centers. Laboratories in Southeast Asian countries improve their equipment and introduce automation. Medical tourism destinations, like Singapore and Thailand, make use of sophisticated platforms. Distributors contribute to serving smaller cities. Assay development and changes in registration help local brands develop. Suppliers address such trends by building partnerships, manufacturing regionally, and offering tiered pricing. Service and training become especially important when dealing with newly established labs. Chains of private laboratories in metropolitan cities also purchase automated systems.
⮞In December 2025, India's national health systems resource center guidelines stated that district hospitals offer 134 tests under the Free Diagnostics Service Initiative, against 97 at community health centers. Wider public test menus raise demand for automated laboratory equipment.
MEA & Latin America Immunoassay Analyzers Market Insights
Latin America is advancing as Brazil and Mexico modernize public and private laboratories. Mexico belongs to this region in market estimates, and its large private laboratory chains purchase analyzers under reagent rental contracts. Currency swings raise import costs, so distributors and financing arrangements are important. Regulatory agencies are working to clear backlogs, which affects the timing of product launches. Argentina, Chile, and Colombia add steady demand from hospital expansion and public screening programs. Pharmaceutical and clinical research activity in the region is also raising demand for biomarker testing.
⮞In July 2026, a regulatory dispatch reported that Brazil's health products agency reorganized 310 pending petitions into 81 technological groupings. Faster review of pending products could shorten the time to market for new analyzers.
Development in the Middle East and Africa Region is occurring due to health initiatives by the government in countries like Saudi Arabia, the United Arab Emirates, and Qatar. Hospitals are opening new facilities along with laboratories that will utilize high throughput automation technology. Public health programs in African nations such as those dealing with HIV/AIDS, hepatitis, and motherhood health create a need for immunoassay testing and midrange analyzer technologies. Constraints of funding and infrastructure have hindered some nations from adopting such solutions. Chinese and Indian vendors have made gains with their cost-effective systems, but global players are using distributors to ensure service levels.
Market Dynamics
Growth Drivers: Chronic Disease Burden and Laboratory Automation Drive Growth in the Immunoassay Analyzers Market
Chronic and infectious disease burdens drive steady growth in immunoassay testing. Diabetes, cardiovascular disease, cancer, thyroid disorders, and chronic infections all need regular biomarker measurement. Aging populations see physicians more often and receive more tests. Screening programs for blood safety, prenatal care, and cancer add further volume. Each new biomarker that gains guideline support raises the number of tests per patient, and hospitals expand analyzer fleets to handle it. This broad base gives the market resilience across economic cycles. Preventive health checks offered by employers and insurers also add to routine testing.
Laboratory automation adds momentum. Staff shortages and rising volumes push laboratories to connect analyzers through tracks and middleware that reduce manual work. Consolidation into hubs raises demand for high throughput systems with long uptime. Digital tools for quality control and remote monitoring improve efficiency. New technologies such as blood based neurological markers open fresh test categories. Reagent rental models allow hospitals to upgrade without large capital spending. Together these forces sustain growth through 2035 even though price pressure remains a concern. Remote service diagnostics can cut downtime and travel for field engineers.
Restraints: Pricing Pressure and Regulatory Compliance Costs Restrain Growth in the Immunoassay Analyzers Market
A major restriction in the market is pricing pressure. Centralized purchasing and price cuts by the authorities and payers of many nations lead to reduced prices for reagents. Laboratories merge to increase bargaining power and reduce the cost per test. Chinese companies introduce competitive technologies that make incumbent vendors fight for their share. Such conditions reduce profit margins and prolong replacement cycles, especially in budget-constrained public hospitals. Tendering purchases also decrease the duration of contracts, thus increasing the cost of acquisition.
Regulatory compliance expenditure acts as a further constraint. The regulation of in vitro diagnostics in Europe requires substantial clinical data and approval by a notified body, which involves significant investment of time and resources. Smaller companies can withdraw products instead of registration. Cybersecurity measures and software verification take efforts. Divergent national regulations create difficulties in launching globally. Disruptions in the supply chain affect reagents and componentry. The high capital cost of advanced analyzers impedes adoption in small laboratories and low-income nations, where manual techniques or outdated instruments prevail.
Opportunities: Blood-Based Biomarkers and Point of Care Expansion Create Opportunities in the Immunoassay Analyzers Market
A promising area is represented by blood-based biomarkers. Tests for Alzheimer's disease, myocardial injury, and cancer can become alternatives to more invasive methods. Thanks to a large installed base of analyzers, it becomes possible to launch novel assays without any additional equipment. Pharmaceutical companies have needs for diagnostic tools for novel treatments and therefore, there are chances for cooperation. Early adapters that get regulatory approval may get an edge due to the orders from neurologists and oncologists. Academic centers' cooperation is important for obtaining necessary clinical data for the development of guidelines.
Another option for business development is point of care solutions. Small devices make immunoassays accessible for tests in emergency vehicles, clinics, pharmacies, and other remote locations. Connectivity and cloud reporting are key features of the modern decentralized workflow. Affordable equipment is required in emerging markets where there is limited infrastructure and personnel. Veterinary and food safety testing represent the sources of new customers. Companies providing financing, training, and technical support will be able to establish themselves in these areas. The cooperation with distributors and public organizations is beneficial for penetration into unserved regions.
Recent Developments:
- In August 2026, Roche received FDA clearance for its Elecsys pTau217 plasma blood test, developed with Eli Lilly, to help assess amyloid pathology in adults aged 55 and older with cognitive decline.
- In February 2026, QuidelOrtho signed a long term supply agreement with Lifotronic Technology for immunoassay analyzer platforms outside the United States.
- In 2026, Siemens Healthineers launched the Atellica Forte clinical chemistry and immunoassay system, according to its third quarter fiscal 2026 results.
- In March 2025, Snibe Diagnostics secured IVDR CE certification from TUV SUD for 73 products.
Immunoassay Analyzers Market Key Players are:
- Roche
- Abbott
- Siemens Healthineers
- Beckman Coulter (Danaher)
- bioMérieux
- QuidelOrtho
- Sysmex
- DiaSorin
- Thermo Fisher Scientific
- Bio-Rad Laboratories
- Becton Dickinson
- Revvity
- Randox Laboratories
- Mindray
- Snibe Diagnostics
- Tecan
- Meso Scale Diagnostics
- Merck KGaA
Immunoassay Analyzers Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.70 Billion |
| Market Size by 2035 | USD 12.39 Billion |
| CAGR | CAGR of 4.87% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Standalone and Integrated Systems, Portable and Point of Care Analyzers, and Others) • By Technology (ELISA, Chemiluminescence, Multiplex and Microfluidic, and Others) • By Application (Infectious Disease, Oncology, Endocrinology, Cardiology, and Others) • By End User (Hospital Laboratories, Independent Diagnostic Laboratories, Veterinary Clinics and Laboratories, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Roche, Abbott, Siemens Healthineers, Beckman Coulter (Danaher), bioMérieux, QuidelOrtho, Sysmex, DiaSorin, Thermo Fisher Scientific, Bio-Rad Laboratories, Becton Dickinson, Revvity, Randox Laboratories, Mindray, Snibe Diagnostics, Tecan, Meso Scale Diagnostics, Merck KGaA |

Frequently Asked Questions
Key players in the market include Roche, Abbott, Siemens Healthineers, Beckman Coulter, bioMérieux, and QuidelOrtho, among others.
Key opportunities include blood based biomarkers for neurological and cancer testing and the expansion of point of care analyzers into clinics and remote settings.
Chronic disease burden and laboratory automation are the major growth factors, as aging populations and staff shortages raise demand for high throughput analyzers.
The Standalone and Integrated Systems segment dominated the market in 2025 with approximately 46.72% share, as laboratories need high throughput platforms that run many assays.
North America dominated the market in 2025 with approximately 41.96% share, supported by a large installed base of laboratory analyzers and strong healthcare spending.
