
Kitchen Appliances Market Report Scope & Overview:
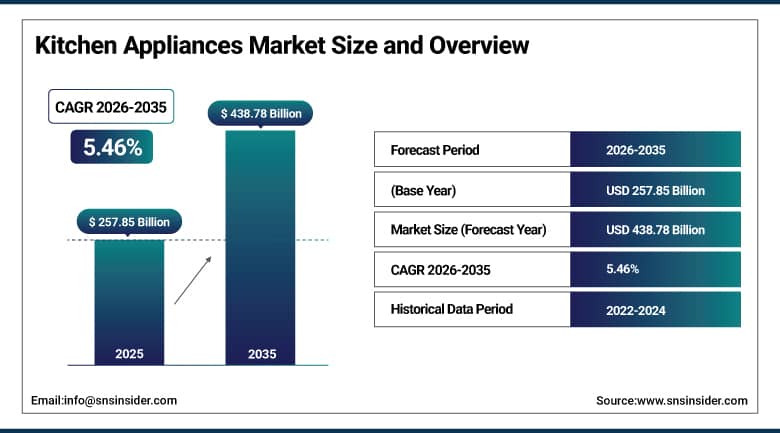
The Kitchen Appliances Market was valued at USD 257.85 Billion in 2025 and is expected to reach USD 438.78 Billion by 2035, growing at a CAGR of 5.46% from 2026-2035.
The Kitchen Appliances Market covers the equipment used to store, prepare, cook and clean up food, ranging from refrigerators, ranges, ovens and dishwashers to small devices such as blenders, air fryers, coffee machines and microwaves. Households account for most purchases, with restaurants, hotels, canteens and cloud kitchens forming the commercial base. Rising urbanization, higher incomes, smaller families and stricter efficiency rules keep replacement cycles active. Connectivity, artificial intelligence cooking assistance and built-in kitchen design are lifting average selling prices, supporting steady value growth through 2035 even where unit sales are flat. Manufacturers that balance premium features with dependable service are best placed to benefit. Premium segments should outpace the overall market. Retail promotions, financing and trade-in programs help sustain demand.
⮞Samsung introduced its 2024 Bespoke AI lineup, integrating artificial intelligence, Wi-Fi connectivity, cameras and SmartThings controls, reinforcing manufacturers’ focus on connected, personalized and premium home appliances.
To Get More Information On Kitchen Appliances Market - Request Free Sample Report
Kitchen Appliances Market Trends
-
Refrigerators and ovens with cameras, food recognition and recipe guidance are moving from flagship ranges into mid-priced models.
-
Countertop air fryers, multi-function ovens and combined microwave air-fry units are replacing single-purpose small appliances.
-
Full built-in kitchen suites with matching styling across fridge, oven, hob and dishwasher are gaining popularity in premium housing.
-
Induction cooking is spreading quickly as buyers seek faster heating, better safety and lower indoor air pollution.
-
Regulators are tightening energy labels and adding repairability and recyclability criteria for refrigerators and other major appliances.
U.S. Kitchen Appliances Market Outlook
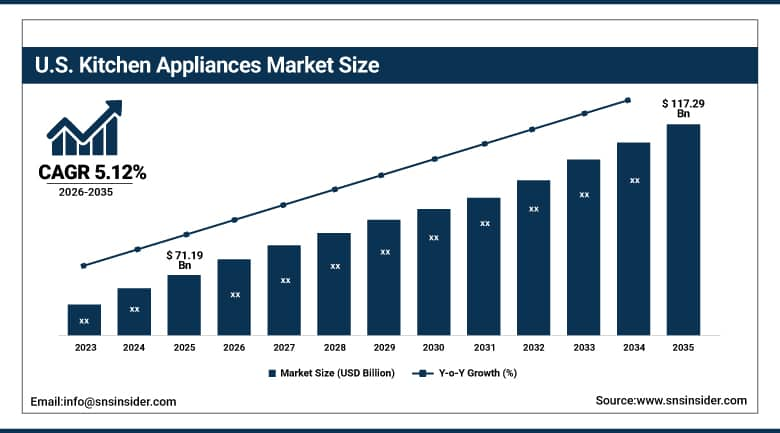
The U.S. Kitchen Appliances Market was valued at USD 71.19 Billion in 2025 and is expected to reach USD 117.29 Billion by 2035, growing at a CAGR of 5.12% from 2026-2035.
The U.S. Kitchen Appliances Market is the largest national market in the world, supported by large homes, high appliance ownership and a strong replacement and remodeling culture. Buyers favor large French-door refrigerators, dual-fuel ranges and wall ovens, and they quickly adopt countertop devices such as air fryers and espresso machines. Housing turnover and new construction influence purchase timing, while retailers and builders promote suites that match across the kitchen. Strong online sales and financing offers reinforce demand, and premium connected products lift the average value of each sale through 2035. Contractors and designers also influence which brands appear in new kitchens. Energy-efficiency tax credits and utility rebates further support upgrades.
⮞The U.S. Department of Energy finalized amended energy conservation standards for refrigerators, refrigerator-freezers and freezers in 2024, with compliance deadlines extending to 2029 or 2030.
Kitchen Appliances Market Segment Analysis
-
By Product, the Refrigerators segment dominated the Kitchen Appliances Market with approximately 35.27% share in 2025, while the Cooking Appliances segment is the fastest growing with a CAGR of approximately 7.41%.
-
By Technology, the Conventional segment dominated the Kitchen Appliances Market with approximately 69.58% share in 2025, while the Smart segment is the fastest growing with a CAGR of approximately 7.93%.
-
By Application, the Residential segment dominated the Kitchen Appliances Market with approximately 64.37% share in 2025, while the Commercial segment is the fastest growing with a CAGR of approximately 6.72%.
-
By Distribution Channel, the Offline segment dominated the Kitchen Appliances Market with approximately 66.39% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 8.46%.
By Product, Refrigerators Dominate the Kitchen Appliances Market and Cooking Appliances Grow Fastest
Refrigerators hold approximately 35.27% of the Kitchen Appliances Market in 2025 because nearly every household needs one, they run continuously and they carry the highest average selling price among kitchen products. Large French-door, side-by-side and multi-door models with water dispensers, wide temperature zones and digital screens are popular in developed markets, while compact single-door units serve fast-growing urban households in Asia and Africa. Replacement cycles of ten to fifteen years and efficiency upgrades sustain volumes. Door-in-door designs and flexible temperature drawers are widening appeal. Brands continue to refine models in this group. Efficiency labels strongly influence choices. Retailers often promote trade-up pricing.
Cooking appliances are the fastest growing product, with a CAGR of approximately 7.41% during 2026-2035. Induction hobs, combination ovens, steam ovens and range hoods are being upgraded as consumers invest in kitchen remodeling and seek faster, safer cooking. Gas stoves are being replaced by electric alternatives in several regions, and smart ovens with cameras and automatic doneness detection command higher prices. Rising interest in home cooking and food-content culture adds momentum. Cookware makers and appliance brands increasingly bundle compatible products, which strengthens sales of induction ranges. Gas-to-electric conversion incentives add further momentum.
⮞The Japan Electrical Manufacturers’ Association reported on 20 October 2026 that refrigerator shipments in Japan from April to September 2026 totaled 1,787,000 units, down 1.9%, with 703,000 units in the 401 liter and larger class.
By Technology, Conventional Dominates the Kitchen Appliances Market and Smart Grows Fastest
Conventional appliances account for approximately 69.58% of the market in 2025 because most households, especially in emerging economies, buy reliable products with mechanical or basic electronic controls at lower prices. Standard refrigerators, gas ranges, basic microwaves and dishwashers dominate retail shelves and housing developments. Simplicity, familiar repair practices and the absence of connectivity needs make them the default choice for budget-conscious buyers and rental properties. Replacement parts and technicians are easy to find, which also supports repair rather than premature disposal of such products across many neighborhoods. Brands continue to refine models in this group. Dealers promote them to value-focused buyers.
Smart devices are the most rapidly developing technologies, growing at a compound annual growth rate of about 7.93% between 2026 and 2035. WiFi-enabled refrigerators, ovens with cameras, app-controlled air fryers and dishwashers that optimize cycle times are becoming available outside the early adopter market. The artificial intelligence assistants give suggestions on meals, track inventory and alert users on the need for maintenance. At the same time, manufacturers have an additional income stream from service and valuable information about their use that inspires investments into the smart components. Software updates and recipe or maintenance subscriptions keep brands in touch with the buyers.
⮞The European Commission’s energy directorate opened a consultation on 4 December 2025 on ecodesign and energy labelling of household and commercial refrigerators, adding reparability and recyclability criteria across four regulations.
By Application, Residential Dominates the Kitchen Appliances Market and Commercial Grows Fastest
Residential use represents approximately 64.37% of the market in 2025 because every household requires a basic set of kitchen appliances, and replacement and upgrade purchases occur steadily. Home ownership, family size, income and remodeling activity shape demand, while new housing adds first-time installations. Consumers increasingly treat the kitchen as a social space, which supports spending on premium finishes and connected features. Small appliances for coffee, baking and healthy cooking add frequent, lower-priced purchases. Landlords and property managers also buy in bulk. Brands continue to refine models in this group. Seasonal promotions also drive sales. Larger households support spending on bigger refrigerators and ranges.
Commercial use is the fastest growing application, with a CAGR of approximately 6.72% through 2035. Restaurants, hotels, hospitals, schools, offices and cloud kitchens need durable refrigeration, cooking lines, dishwashers and beverage equipment. Growth of delivery-only kitchens, quick-service chains and tourism raises equipment demand, and energy-saving and labor-saving features are important purchasing criteria. Leasing programs also help smaller operators upgrade equipment without large upfront cost. Equipment suppliers are adding connected monitoring that tracks temperatures, energy use and maintenance needs, helping operators cut waste and comply with food safety rules. Food-delivery growth keeps new capacity coming.
By Distribution Channel, Offline Dominates the Kitchen Appliances Market and Online Grows Fastest
Offline retail holds approximately 66.39% of the market in 2025, since buyers of large appliances want to see dimensions, finishes and noise levels in person and to arrange delivery and installation. Specialty stores, electronics chains, home improvement centers and builders’ showrooms provide demonstration, financing and after-sales service. Kitchen designers and contractors also steer purchases of built-in products. Large retailers use exclusive models and extended warranties to protect margins. Appliance brands also operate showrooms and experience centers where customers can see live cooking demonstrations. Brands continue to refine models in this group. After-sales support is a clear differentiator.
Online sales are the fastest growing channel, at a CAGR of approximately 8.46% during 2026-2035. Small appliances are already bought extensively on marketplaces and brand websites, and delivery of large items with installation is improving. Price comparison, customer reviews and short-form video demonstrations influence decisions. Trade-in schemes, buy-now-pay-later offers and flash sales further raise online penetration, particularly among younger consumers. Manufacturers are building direct-to-consumer websites, which gives them data on buyers and better control over pricing and service. Live chat support also helps.
⮞China’s Ministry of Commerce reported on 3 April 2026 that about 23.21 million home appliances were traded in under the national subsidy program in the first quarter of 2026.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.71% |
|
Asia Pacific |
China |
38.64% |
|
Europe |
Germany |
23.18% |
|
Latin America |
Brazil |
47.52% |
|
Middle East & Africa |
Saudi Arabia |
25.76% |
North America Kitchen Appliances Market Insights
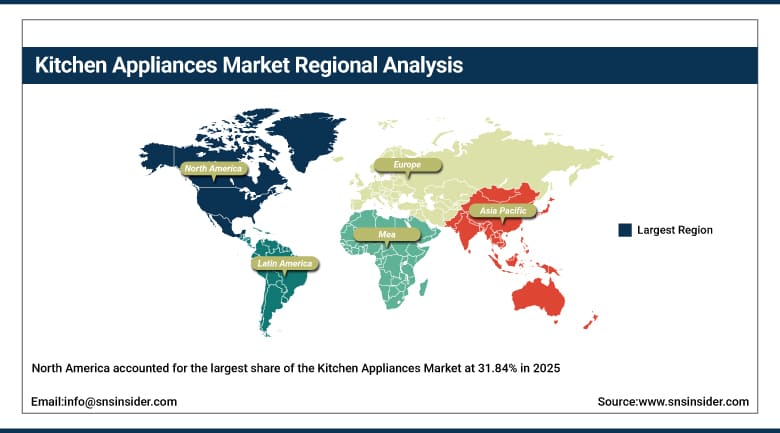
North America accounted for the largest share of the Kitchen Appliances Market at 31.84% in 2025, with the United States contributing about 86.71% of regional demand and Canada the balance. Households own a wide range of appliances, spend heavily on remodeling and replace products before the end of their useful lives to gain new features. Large capacity refrigerators, professional-style ranges and premium dishwashers sell strongly. Retail financing, strong brand loyalty and builder partnerships support volumes. Remodeling contractors strongly influence final brand selection. Appliance demand also benefits from steady immigration-led household formation.
Canada follows similar patterns, with a rising interest in induction cooking and energy-efficient models supported by utility rebates. Mexico, which belongs to Latin America, is a major production base for refrigerators, ranges and washers sold across the continent. Small appliance demand is strong, led by air fryers, coffee systems and blenders. Online retail continues to take share, while trade policy and tariffs influence pricing and the location of manufacturing. Builders buy appliance packages in bulk for new housing developments. Utility rebates for efficient models strengthen purchases.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Kitchen Appliances Market Insights
Asia Pacific held approximately 29.62% of the Kitchen Appliances Market in 2025 and is the fastest growing region, with a CAGR of 7.48% during 2026-2035. China, India, Japan, South Korea and Southeast Asia combine the world’s largest population with rapid urbanization, expanding middle classes and a huge manufacturing base. Rising household incomes lift ownership of refrigerators, microwaves, dishwashers and air fryers, while government subsidy and trade-in programs stimulate replacement. Local manufacturers supply both home markets and export customers. Trade-in programs expand the addressable market.
China represents the biggest market for household appliances and is the number one exporter where the competition revolves around features and pricing. India is fast developing as there are incentives for efficient units with star-rating regulations, as well as first-time purchase opportunities resulting from new construction. Japan and South Korea represent the leading manufacturers of premium and small appliances, while Southeast Asia, comprising Vietnam, Indonesia and Thailand, provide volume from young and urbanizing populations. Refrigerator sales are increasing due to urbanization and increased food safety awareness. Home cooking traditions, spice grinding and fresh foods storage influence product design.
⮞The China Household Electrical Appliances Association reported on 19 August 2026 that China’s home appliance exports from January to July 2026 reached 2.743 billion units, up 5.9% year on year.
Europe Kitchen Appliances Market Insights
Europe held approximately 25.47% of the Kitchen Appliances Market in 2025, led by Germany, the United Kingdom, France, Italy and Spain. The region is home to several premium and built-in brands, and buyers emphasize quality, design, energy efficiency and long service life. Built-in kitchens are widespread, which supports sales of integrated ovens, hobs, dishwashers and refrigerators. Energy labeling and ecodesign rules are among the strictest in the world and steer buyers toward efficient products. Retailers highlight energy ratings clearly on every product. Compact apartments in cities encourage slimline designs.
Germany is the biggest country in terms of market share owing to the high level of income and the design-focused kitchen industry. The United Kingdom and France demonstrate high levels of interest in both freestanding and built-in appliances, while Italy is the main country that specializes in designing and producing cooking appliances. Eastern Europe becomes the region of increasing importance, with the growing popularity of dishwashers and up-to-date hobs. Reparability and availability of spare parts are influencing product development and service approaches. Availability of spare parts and warranty period are starting to become key features of the brand.
⮞The German Federal Statistical Office reported on 9 December 2025 that, as of 1 January 2023, 99.9% of German households had a refrigerator, 78.0% had a dishwasher and 72.2% had a microwave.
MEA & Latin America Kitchen Appliances Market Insights
The Middle East and Africa and Latin America together account for approximately 13.07% of the Kitchen Appliances Market in 2025, with the Middle East and Africa at 6.78% and Latin America at 6.29%. In the Gulf, Saudi Arabia and the United Arab Emirates have high spending on premium appliances, large homes and hospitality projects. Africa is led by South Africa, Egypt, Nigeria and Kenya, where electrification and urban growth raise ownership of refrigerators and small cooking devices, though price sensitivity remains high. Large tourism and hospitality projects add commercial orders.
The key players of Latin America include Brazil and Mexico. Brazil offers strong home production of refrigerators, cooking range, and minor household goods; while Mexico acts as the exporter. Argentina, Colombia and Chile offer demand owing to expansion of urban housing and retail chains. Installment sales play a significant role in finance; whereas fluctuation in currency value and cost of imports play a major role in pricing of the products. The efficiency programs are slowly increasing the penetration rate of inverter refrigerators and induction goods. The retail chains are also expanding in secondary cities.
⮞The International Energy Agency reported in 2025 that four in five households in sub-Saharan Africa lack access to clean cooking, which contributes to about 3 million premature deaths a year.
Market Dynamics
Growth Drivers: Urbanization and Energy Efficiency Mandates Drive Growth in the Kitchen Appliances Market
Urbanization and rising incomes are the strongest forces behind the Kitchen Appliances Market. Millions of people move to cities each year, forming new households that need refrigeration, cooking and cleaning equipment. Smaller apartments favor compact and multi-function appliances, and busy work schedules increase use of microwaves, air fryers and dishwashers. Growth of the middle class in Asia, Africa and Latin America raises first-time ownership rates and shortens the time between upgrades. Government housing programs reinforce this trend. Growing awareness of food waste also favors better refrigeration.
Energy efficiency and safety regulations form the second driver. Mandatory star labels, minimum performance standards and incentives for induction and heat-pump appliances push consumers toward newer models and make older units obsolete. Utilities and governments offer rebates and trade-in programs that accelerate replacement. Manufacturers respond with inverter compressors, improved insulation and connected controls, which raise average selling prices and support the value of the market. Trade-in schemes in China and several European countries illustrate how policy support can lift sales during slow periods. Better financing options widen access.
⮞The Bureau of Energy Efficiency of India made star labels mandatory from 1 January 2026 for refrigerators, deep freezers, LPG stoves and several other appliance categories, with stricter five-star limits.
Restraints: Housing Weakness and Cost Pressures Restrain Growth in the Kitchen Appliances Market
As far as home sales and constructions go, high mortgage rates and low turn-over prevent both new installations and replacement. Consumers tend to put off making purchases under the strain of inflation, opting for repair as opposed to replacement. In mature markets where most people have ownership of essential items, there is little scope left for increase. Discounting tends to be quite high in such scenarios, hurting supplier margins. Retail promotions alone cannot compensate for all this.
There is also additional pressure in terms of costs. There are prices and tariff surges when it comes to the cost of steel, aluminum, copper, plastic, and electronic parts that manufacturers cannot pass to the customers. The tough competition in low-cost production reduces the margin, while freight and compliance costs increase. New legislation regarding the energy label, chemical and reparability standards makes redesigning necessary. Any disruption in supply affects launch schedules and creates uneven stocks of retail outlets. Trade measures of major countries make the situation even more complicated.
⮞The Brazilian Electrical and Electronics Industry Association reported in 2026 that sector output fell 1.8% from January to August 2026, and that 44% of firms reported lower September sales than a year earlier.
Opportunities: Connected Cooking and Efficiency Upgrades Create Opportunities in the Kitchen Appliances Market
There is an incredible opportunity through connected cooking. Appliances equipped with cameras, sensors and AI will be able to detect the food, recommend recipes, perform the cooking process automatically and also notify about the necessity for maintenance. Software updates will ensure longevity of the product for a lot of years, and brands can even develop additional services, such as meal planning and groceries ordering on the basis of these devices. Premium pricing and brand loyalty can serve as a great advantage for the companies which implement these technologies well while protecting the privacy of the users.
Efficiency upgrades in emerging markets provide a second opening. New minimum performance standards for refrigerators in the Middle East and elsewhere, together with growth in induction cooking, create demand for modern, inverter-based products. Built-in kitchens, commercial cloud kitchens and eco-friendly designs add further areas of growth. Suppliers that offer repairable, recyclable products with long warranties can win buyers and satisfy tightening regulations. Rental housing and hospitality refurbishments contribute additional volume. Partnerships with utilities and grocers broaden the ecosystem of services around the kitchen. Second-hand and rental models also appeal to young households.
⮞Saudi Arabia’s standards body SASO issued a draft standard, SASO 2892:2025, that sets minimum energy performance requirements and labeling for refrigerators and freezers of 10 to 1,500 liters.
Recent Developments:
-
2025: SharkNinja launched the Ninja CRISPi PRO glass air fryer with a 6-quart glass container and six cooking modes, including Air Fry, Bake, Roast, Dehydrate, Max Crisp and Re-Crisp.
-
2026: Whirlpool Corporation previewed its KBIS 2026 portfolio, including 36-inch True Counter Depth refrigerators with dispensed nugget ice, a KitchenAid double wall oven with camera and doneness detection, and a JennAir 48-inch induction range.
-
2026: LG Electronics unveiled a full built-in kitchen suite for EuroCucina, featuring a 384 liter Wide Combi refrigerator, a camera oven with AI food recognition, a 6-in-1 compact oven, a hood-integrated induction hob and a dishwasher with a one-hour full cycle.
-
2026: Samsung Electronics introduced its 2026 Bespoke AI range in India, including a Family Hub refrigerator with a 32 inch screen and AI Vision food recognition.
Kitchen Appliances Market Key Players are:
-
Whirlpool Corporation
-
SharkNinja, Inc.
-
Samsung Electronics Co., Ltd.
-
LG Electronics Inc.
-
Electrolux Group
-
Composition Brands
-
Midea Group Co., Ltd.
-
Breville Group Limited
-
Hamilton Beach Brands Holding Company
-
Miele & Cie. KG
-
Vita-Mix Corporation
Kitchen Appliances Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 257.85 Billion |
| Market Size by 2035 | USD 438.78 Billion |
| CAGR | CAGR of 5.46% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Refrigerators, Cooking Appliances, Dishwashers, and Others) • By Technology (Conventional and Smart) • By Application (Residential and Commercial) • By Distribution Channel (Offline and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Whirlpool Corporation, SharkNinja, Inc., Samsung Electronics Co., Ltd., LG Electronics Inc., Electrolux Group, Composition Brands, Midea Group Co., Ltd., Breville Group Limited, Hamilton Beach Brands Holding Company, Miele & Cie. KG, Vita-Mix Corporation |

Frequently Asked Questions
The key players in the Kitchen Appliances Market include Whirlpool Corporation, SharkNinja, Inc., Samsung Electronics Co., Ltd., LG Electronics Inc., Electrolux Group, among others.
Key opportunities include connected and AI-assisted cooking, efficiency upgrades in emerging markets, and growth in built-in kitchens and commercial cloud kitchens.
The major growth factor is urbanization and rising incomes, supported by energy efficiency mandates that accelerate replacement of older appliances.
The Refrigerators segment dominated the Kitchen Appliances Market with approximately 35.27% share in 2025, because nearly every household needs one and they carry the highest average selling price among kitchen products.
North America dominated the Kitchen Appliances Market with a 31.84% share in 2025, driven by high appliance ownership, remodeling activity and replacement demand in the United States.
