
Mass Flow Controller Market Report Scope & Overview:
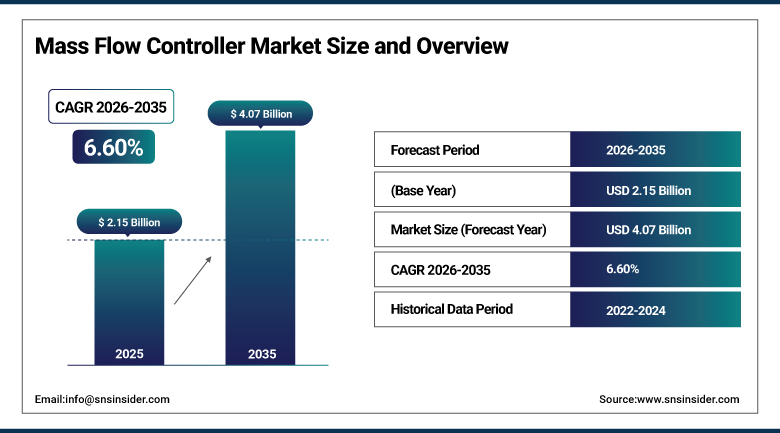
The Mass Flow Controller Market was valued at USD 2.15 Billion in 2025 and is expected to reach USD 4.07 Billion by 2035, growing at a CAGR of 6.60% from 2026 to 2035.
The mass flow controller market has been experiencing rapid growth owing to advancements in technology and the rise in demands from various sectors, including the semiconductor industry. A mass flow controller is an advanced device that is used in industries where there is a need for precise gas and liquid flow control. This is done by mechanical regulation of the flow rate based on a predetermined flow rate given through electric signals without being influenced by changes in pressure. They are commonly used in semiconductor, chemical, pharmaceutical industries, as well as for research purposes. The increase in demand for automation in developing countries is fueling the development of the market, as demonstrated by investments by firms like TSMC in its new plant in Phoenix and by Intel in its Arizona project.
As per data by Semiconductor Industry Association, the total worldwide revenue that has been generated through the sale of semiconductor products reached $627.6 billion in 2024, showing an increase of 19.1% compared to 2023 due to the increase in domestic manufacturing of semiconductors in the US by 203% since the introduction of the CHIPS and Science Act over the last decade. The growth in demand curve justifies the need for mass flow controllers, where millions of wafers are moved daily in semiconductor fabs.
To Get more information Mass Flow Controller Market - Request Free Sample Report
Mass Flow Controller Market Trends
- Rising development of smart mass flow controllers with integrated diagnostics and remote monitoring is supporting automated, connected semiconductor fabrication environments.
- Growing major fab investments, including TSMC's facility in Phoenix and Intel's expansion in Arizona, continue to add wafer fabrication capacity and demand for high-accuracy mass flow controllers.
- Increasing development of ultra-low-drift mass flow controller series designed for sub-parts-per-million flow control is supporting advanced semiconductor process requirements.
- Expanding rising demand for automation in emerging economies is driving mass flow controller adoption across chemicals, pharmaceuticals, and industrial gas applications requiring precise flow regulation.
- Strategic partnerships among mass flow controller manufacturers, semiconductor equipment providers, and pharmaceutical companies are supporting development of increasingly diverse, application-specific flow control solutions.
The U.S. Mass Flow Controller Market Outlook
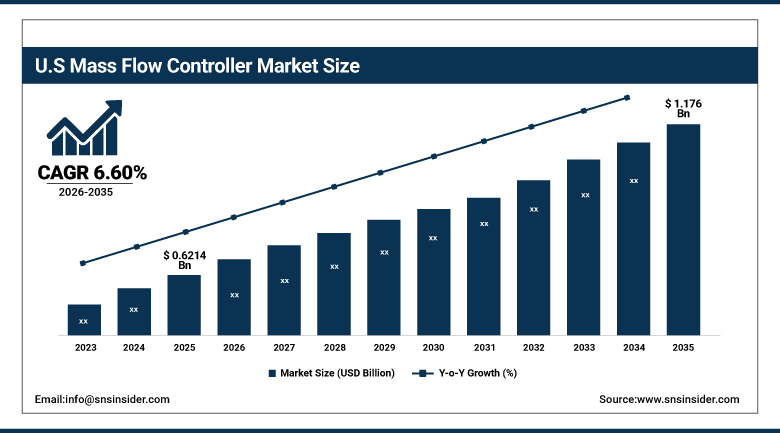
The U.S. mass flow controller market was valued at USD 0.6214 Billion in 2025 and is projected to reach USD 1.176 Billion by 2035, growing at a CAGR of 6.60% during 2026–2035.
Leading producers of mass flow controllers in the United States keep growing their production capacities amid substantial investments made by the country into the development of its semiconductor manufacturing industry. Major fabs, such as the one of TSMC and Intel’s Arizona expansion, keep investing in the growth of their capacity, with domestic chip manufacturing predicted to grow 203 percent in the next decade according to the CHIPS and Science Act.
In 2025, the U.S. mass flow controller market continued to benefit from substantial semiconductor manufacturing investments, particularly through new and expanded fabrication facilities in Arizona. With more homegrown chip manufacturers in the country, there is now an increased demand for precise gas and fluid flow control in wafer manufacturing and semiconductor processes. Moreover, the increasing demand from the pharmaceutical, chemical, and manufacturing industry segments further helps bolster mass flow controller sales, making the US a vital regional market.
Mass Flow Controller Market Segment Analysis
- By Material Type, stainless steel dominated the mass flow controller market with a 62.00% share in 2025, while alloy is the fastest-growing material type segment with a CAGR of 7.90% from 2026–2035.
- By Flow Rate, medium flow (>25 SLM–≤1000 SLM) dominated the mass flow controller market with a 52.00% share in 2025, while high flow (>1000 SLM) is the fastest-growing flow rate segment with a CAGR of 8.20% from 2026–2035.
- By Product Type, thermal MFC dominated the mass flow controller market with a 48.60% share in 2025, while Coriolis MFC is the fastest-growing product type segment with a CAGR of 8.20% from 2026–2035.
- By End-User Industry, semiconductor dominated the mass flow controller market with a 44.60% share in 2025, while pharmaceuticals is the fastest-growing end-user industry segment with a CAGR of 8.60% from 2026–2035.
- By Connectivity, analog dominated the mass flow controller market with a 56.80% share in 2025, while digital/fieldbus is the fastest-growing connectivity segment with a CAGR of 8.80% from 2026–2035.
- By Application, spray coating processes dominated the mass flow controller market with a 32.60% share in 2025, while semiconductor fabrication/etching is the fastest-growing application segment with a CAGR of 9.20% from 2026–2035.
By Product Type, thermal MFC dominated the mass flow controller market, while coriolis MFC is the fastest-growing segment.
Thermal mass flow controllers were prevalent in the market due to the effectiveness and reliability of this technology in the gas flow measurement industry. The thermal MFC is the dominant technology category due to its accuracy and reliability across most of the semiconductor manufacturing and industrial gas flow control processes. It constitutes the conventional flow control technology in the majority of commercially available MFC products worldwide.
The coriolis MFC segment is predicted to witness the fastest CAGR of 8.20% over the forecast period 2026-2035. Increasing demand for accurate liquid flow measurements in the pharmaceutical and chemical processing applications is fueling the growth of the Coriolis MFC segment since this technology can accurately measure the mass flow independent of the fluid density and viscosity changes.
By End-User Industry, semiconductor dominated the mass flow controller market, while pharmaceuticals is the fastest-growing segment.
The semiconductor manufacturing segment leads the market. Semiconductor manufacturing remains the dominant end-user industry category owing to mass flow controllers' essential role delivering precisely controlled gas flows as millions of wafers are processed in fabs, representing the largest and most established application driving overall mass flow controller demand across the global electronics manufacturing supply chain.
The pharmaceuticals segment is witnessing the fastest growth due to rising healthcare demands. Growing pharmaceutical manufacturing process automation requiring precise gas and liquid flow control for drug formulation and biotechnology applications is driving rising segment growth, as regulatory compliance increasingly requires sophisticated flow control instrumentation across pharmaceutical production facilities.
By Connectivity, analog dominated the mass flow controller market, while digital/fieldbus is the fastest-growing segment.
The analog category dominated the market. Analog connectivity remains the dominant category owing to its established, widely compatible integration with existing industrial control systems, representing the standard communication protocol across the majority of installed mass flow controller infrastructure across semiconductor and industrial gas applications worldwide.
The digital/fieldbus segment is expected to register the fastest CAGR of 8.80% during the forecast period 2026-2035. Suppliers advancing smart mass flow controllers with integrated diagnostics and remote monitoring for automated, connected semiconductor fabrication environments are driving rapid segment growth, as manufacturers increasingly transition toward digitally networked flow control systems.
By Application, spray coating processes dominated the mass flow controller market, while semiconductor fabrication/etching is the fastest-growing segment.
Spray coating processes segment was leading in the mass flow controller market based on application in 2025. Spray coating remains the dominant application category owing to mass flow controllers' essential role delivering precisely controlled gas flows supporting industrial and electronics coating processes, representing the largest single application driving overall mass flow controller demand worldwide.
The semiconductor fabrication/etching segment is expected to register the fastest CAGR of 9.20% during the forecast period 2026-2035. Major fab investments continuing to add wafer fabrication capacity, combined with growing demand for sub-parts-per-million flow control in advanced semiconductor processes, is driving rising segment growth across increasingly sophisticated chip manufacturing applications.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
Taiwan |
34.10% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
North America Mass Flow Controller Market Insights
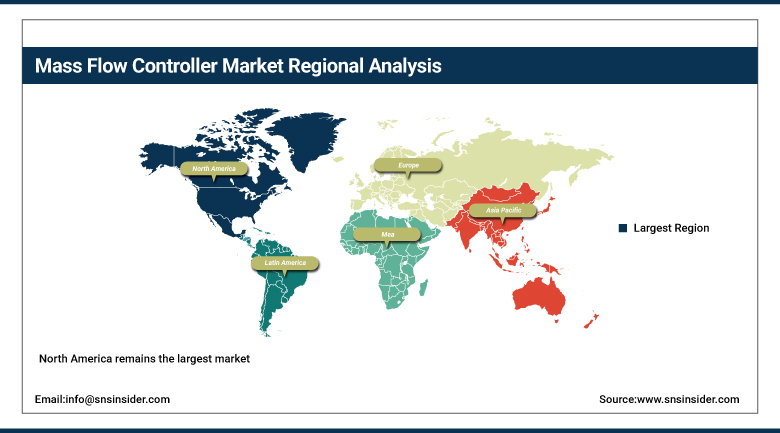
North America remains the largest market for mass flow controllers, primarily due to its strong semiconductor manufacturing sector, with major fab investments continuing to add wafer fabrication capacity across the region.
The US emerged as the dominant player in the North America mass flow controller market in 2025 owing to TSMC’s plant in Phoenix and Intel’s expansions in Arizona, both of which keep increasing their fab capacities. Canada has become an important contributor to the regional market growth because of its own industrial and chemical automation industry.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Mass Flow Controller Market Insights
The Europe mass flow controller market was a major contributor in 2025. This is attributed to the region's strong industrial automation base, presence of leading flow control instrumentation manufacturers, and growing pharmaceutical and chemical processing industry investment across member states.
Germany happens to be among the biggest markets in Europe due to the country’s advanced manufacturing industry base and availability of companies like Bürkert and Bronkhorst High-Tech involved in production of flow control instruments. Other countries such as Switzerland, home to Sensirion AG, are also contributing to market growth through extensive precision instrumentation manufacturing capacity.
Asia Pacific Mass Flow Controller Market Insights
Asia-Pacific is identified as the fastest-growing region, fueled by rapid industrialization and technological adoption, with the region projected to offer lucrative prospects with a share of 34.1% during the forecast period.
Taiwan is one of the main growth drivers in the Asia Pacific mass flow controller market, owing to its status as home to TSMC, the world's leading semiconductor foundry commanding 65% of the semiconductor foundry market share. China, Japan, and South Korea are also contributing to regional growth through expanding domestic semiconductor and electronics manufacturing capacity.
Middle East & Africa and Latin America Mass Flow Controller Market Insights
Middle East & Africa and Latin American regions are gradually expanding mass flow controller adoption as industrial automation and chemical processing infrastructure investment grows across both regions.
Brazil is set to be a prominent Latin American market fueled by growing domestic chemical processing and industrial manufacturing capacity. The Middle East & Africa region has UAE and Saudi Arabia investing in modern industrial infrastructure that is gradually increasing demand for precision flow control instrumentation across their expanding oil and gas and manufacturing sectors.
Market Dynamics
Growth Drivers: Rising semiconductor fabrication investment and automation demand driving market growth
Technological advancements and increasing demand across various sectors are primarily driving the mass flow controller market. The growing automation needs in developing countries is one of the key revenue drivers due to increasing fabs capacities through new fabs construction, such as TSMC Fab in Phoenix and Intel Fab in Arizona, which require high-accuracy mass flow controllers on a global scale.
The global semiconductor sales grew to USD 627.6 billion in 2024, representing a rise of 19.1% from the previous year, while domestic chip production in the United States is projected to grow by 203% within the next ten years as per CHIPS and Science Act. Suppliers advancing smart mass flow controllers with integrated diagnostics and remote monitoring for automated, connected fabrication environments, and increasing need for precise and accurate flow meters in chemical and pharmaceutical industries, are further supporting demand across the forecast period.
Restraints: High initial investment and technical complexity limiting market expansion
One of the major limitations to market expansion is the high level of initial investments in mass flow controllers, which continues to hinder wide adoption in small industrial companies and research institutions that have tight budgets for capital equipment.
Besides, the complicated process of developing flow control at sub-parts-per-million accuracy needed for advanced semiconductor processes continues to attract high levels of research and development investments by manufacturers. Fluctuating semiconductor industry capital expenditure cycles further introduce demand volatility for mass flow controller manufacturers reliant on wafer fabrication capacity expansion investment.
Opportunities: Expansion of smart connectivity and pharmaceutical applications creating new growth avenues
Suppliers advancing smart mass flow controllers with integrated diagnostics and remote monitoring represent a substantial market opportunity for manufacturers capable of developing digitally networked flow control systems supporting increasingly automated, connected fabrication environments.
There is a considerable growth opportunity in the continued expansion of pharmaceutical and biotechnology applications requiring precise gas and liquid flow control for drug formulation. The expansion of semiconductor manufacturing capacity and industrial automation investment in emerging markets across Asia Pacific is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Aalborg Instruments unveiled an ultra-low-drift mass flow controller series in May 2025, designed for sub-parts-per-million flow control in advanced semiconductor processes.
- 2025: Major fab investments, including TSMC's facility in Phoenix and Intel's expansion in Arizona, continued to add wafer fabrication capacity and demand for high-accuracy mass flow controllers.
- 2026: MKS Instruments launched an updated smart mass flow controller with integrated diagnostics and remote monitoring, offering semiconductor customers enhanced automated fabrication environment compatibility.
- 2026: Bronkhorst High-Tech expanded its Coriolis mass flow controller production capacity, strengthening its ability to supply growing pharmaceutical application demand for precision liquid flow measurement.
Mass Flow Controller Market key players are:
- MKS Instruments, Inc.
- Brooks Instrument LLC (ITW)
- Bronkhorst High-Tech B.V.
- Sensirion AG
- Horiba, Ltd.
- Azbil Corporation
- Teledyne Technologies Incorporated
- Halma plc (Alicat Scientific)
- Parker Hannifin Corporation
- Christian Bürkert GmbH & Co. KG
- TASI Group
- Tokyo Keiso Co., Ltd.
- FCTechnik AG
- Kojima Instruments (Kofloc)
- Aalborg Instruments & Controls, Inc.
- Axetris AG
- Dwyer Instruments, Inc.
- FCON Co., Ltd.
- Kelly Pneumatics, Inc.
- IMI plc
Mass Flow Controller Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.15 Billion |
| Market Size by 2035 | USD 4.07 Billion |
| CAGR | CAGR of 6.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (Stainless Steel, Alloy, Others) • By Product Type (Thermal MFC, Coriolis MFC) • By Flow Rate (Low Flow (≤ 25 SLM), Medium Flow (>25 SLM – ≤1000 SLM), High Flow (>1000 SLM)) • By Connectivity (Analog, Digital/Fieldbus) • By Application (Spray Coating Processes, Semiconductor Fabrication/Etching) • By End-User Industry (Semiconductor, Pharmaceuticals, Oil & Gas, Chemical, Food and Beverages, Water and Wastewater Treatment, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | MKS Instruments, Inc., Brooks Instrument LLC (ITW), Bronkhorst High-Tech B.V., Sensirion AG, Horiba, Ltd., Azbil Corporation, Teledyne Technologies Incorporated, Halma plc (Alicat Scientific), Parker Hannifin Corporation, Christian Bürkert GmbH & Co. KG, TASI Group, Tokyo Keiso Co., Ltd., FCTechnik AG, Kojima Instruments (Kofloc), Aalborg Instruments & Controls, Inc., Axetris AG, Dwyer Instruments, Inc., FCON Co., Ltd., Kelly Pneumatics, Inc., IMI plc. |
Frequently Asked Questions
Key players in the Mass Flow Controller Market include MKS Instruments, Inc., Brooks Instrument LLC, Bronkhorst High-Tech B.V., Sensirion AG, and HORIBA, Ltd., among others.
Key opportunities in the Mass Flow Controller Market include semiconductor fab expansion, increasing demand for high-precision gas control, pharmaceutical manufacturing, and adoption of digital and smart flow-control technologies.
The market is driven by rising demand for automation in emerging economies and major fab investments continuing to add wafer fabrication capacity.
The Thermal MFC segment dominated the Mass Flow Controller Market.
The North America region dominated the Mass Flow Controller Market in 2025, driven by its strong semiconductor manufacturing sector.
