
Memristor Market Report Scope & Overview:
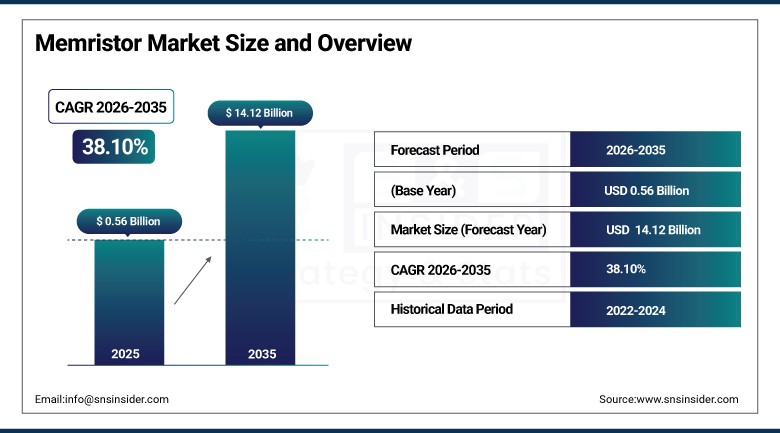
The Memristor Market size was valued at USD 0.56 Billion in 2025 and is expected to reach USD 14.12 Billion by 2035, growing at a CAGR of 38.10% from 2026-2035.
Memristors constitute an emerging category within advanced memory and computing hardware, resistive devices whose resistance depends on the history of current passing through them, enabling non-volatile storage, in-memory computation, and artificial synapses in a compact structure. Rising demand for energy-efficient computing, the growth of artificial intelligence and neuromorphic systems, and the limits of conventional memory scaling continue to draw investment from semiconductor makers, research institutions, and startups. Foundries, integrated device manufacturers, and technology licensors rely on resistive memory to support embedded, automotive, and edge applications. Sustained growth is being shaped by licensing agreements, automotive qualification, and progress from laboratory prototypes toward production silicon, reinforcing this market's position as a high-potential, technology-led segment of the wider semiconductor industry.
⮞In 2025, Weebit Nano announced that it had licensed its resistive random-access memory technology to Texas Instruments. The agreement followed a January 2025 license to Onsemi and reflects growing adoption of resistive memory as an embedded non-volatile option among leading semiconductor suppliers.
To Get more information On Memristor Market - Request Free Sample Report
Memristor Market Trends
-
Growing licensing of resistive memory technology to tier-one semiconductor suppliers for embedded applications.
-
Rising focus on neuromorphic and in-memory computing architectures for low-power artificial intelligence.
-
Expanding automotive qualification of resistive memory, including AEC-Q100 Grade 1 reliability milestones.
-
Increasing research into extreme-environment devices operating at very high temperatures.
-
Rising integration of hybrid CMOS-memristor chips within mainstream foundry process nodes.
-
Growing academic and government-funded programs advancing analog compute-in-memory technology.
U.S. Memristor Market Size Outlook
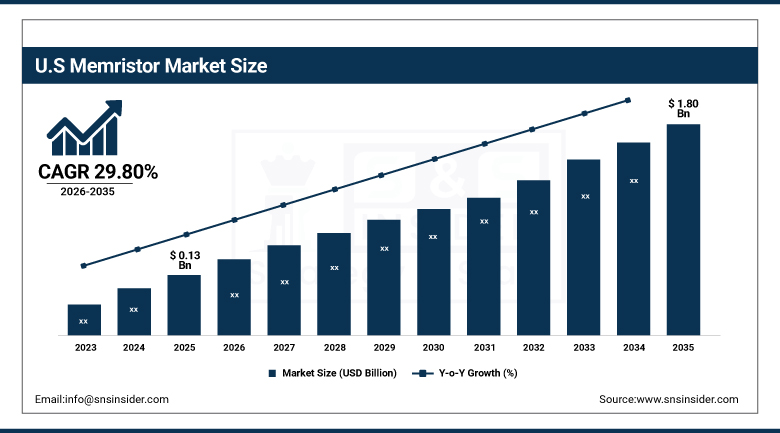
The U.S. Memristor Market was valued at USD 0.13 Billion in 2025 and is expected to reach USD 1.80 Billion by 2035, growing at a CAGR of 29.80% from 2026-2035.
Domestic demand is underpinned by the country's concentration of leading semiconductor companies, national laboratories, and startups pursuing resistive memory for artificial intelligence and edge computing. Federal support for domestic chip manufacturing and advanced packaging is encouraging trusted foundry qualification of resistive memory processes, while defense, aerospace, and space programs create demand for devices that tolerate radiation and extreme temperatures. Venture-backed companies continue to commercialize memristor-based compute and memory products, and academic partnerships supply a steady pipeline of device innovations. Growing interest in energy-efficient inference for data centers and edge devices further supports domestic market expansion, positioning U.S. developers to move from prototypes toward qualified production parts in the coming years, particularly where power budgets, radiation tolerance, and data movement costs matter most.
⮞In 2026, San Jose-based TetraMem announced that its academic and research collaborators had demonstrated resistive memory (memristor) devices capable of reliable operation at temperatures up to 700 degrees Celsius. The company stated the result marks a major advance for non-volatile memory in extreme-environment and deep-space computing.
Memristor Market Segment Analysis
-
By Technology, the Spin-Based & Magnetic segment dominated the market with a 40.22% share in 2025, while the Molecular & Ionic Thin Film segment is the fastest growing with a CAGR of 41.60% during 2026-2035.
-
By Material, the Metal Oxides segment dominated the market with a 37.25% share in 2025, while the Chalcogenides segment is the fastest growing with a CAGR of 42.30% during 2026-2035.
-
By Application, the Memory Storage segment dominated the market with a 46.80% share in 2025, while the Neuromorphic Computing segment is the fastest growing with a CAGR of 44.20% during 2026-2035.
-
By End-Use Industry, the Consumer Electronics segment dominated the market with a 31.55% share in 2025, while the Automotive segment is the fastest growing with a CAGR of 40.80% during 2026-2035.
By Technology, Spin-Based & Magnetic Dominates the Market and Molecular & Ionic Thin Film Grows Fastest
Spin-Based & Magnetic devices dominated the market in 2025, a position built on their relative maturity, proven endurance, and existing commercial products in embedded and specialty memory. Suppliers favour these devices precisely because they combine non-volatility with fast switching and strong reliability in demanding environments, a combination that has allowed magnetic memory to reach real revenue in industrial, aerospace, and automotive applications, even as newer resistive technologies continue to expand around it and compete for design wins with simpler materials and fewer manufacturing steps.
Molecular & Ionic Thin Film devices are projected to be the fastest-growing technology category over the forecast period. These devices offer low-voltage operation, multilevel conductance states, and structures well suited to analog compute-in-memory and synaptic emulation, which makes them attractive for neuromorphic hardware. As researchers move from simulation to production silicon and as foundries qualify new film stacks, these technologies continue to close the gap with spin-based memory in overall market demand.
By Material, Metal Oxides Dominates the Market and Chalcogenides Grows Fastest
Metal Oxides dominated the market in 2025. Materials such as hafnium, tantalum, and titanium oxides are compatible with standard semiconductor fabrication lines, offering reliable switching behavior and manageable process complexity. This compatibility with existing foundry infrastructure, together with a deep body of research on switching mechanisms, continues to sustain metal oxides as the largest material category across the broader market and the default choice for embedded resistive memory.
Chalcogenides are expected to be the fastest-growing material category over the forecast period. Their tunable electrical properties and fast switching support high-density arrays and multilevel storage, and they are drawing attention for storage-class memory and analog computing. As process engineers address variability and integration challenges, chalcogenide layers continue to close the gap with metal oxides in overall market demand.
By Application, Memory Storage Dominates the Market and Neuromorphic Computing Grows Fastest
Memory Storage applications dominated the market in 2025. The urgent need for faster, more durable, and more energy-efficient non-volatile memory has made storage the first and largest commercial use of memristive devices, particularly as embedded flash becomes harder to scale at advanced nodes. Steady licensing and qualification activity around embedded resistive memory sustains storage as the largest application category by a clear margin across the broader market.
Neuromorphic Computing applications are projected to expand fastest over the forecast period. Memristor crossbars can perform multiplication and accumulation directly within memory, dramatically reducing data movement and power consumption for neural network inference. As laboratories transition from simulation to production silicon and as demand for low-power artificial intelligence at the edge grows, neuromorphic applications continue to close the gap with storage in overall market demand.
By End-Use Industry, Consumer Electronics Dominates the Market and Automotive Grows Fastest
Consumer Electronics dominated the market in 2025. Smartphones, wearables, and connected devices continually demand compact, low-power, high-speed memory, and device makers are willing to evaluate new memory technologies that extend battery life. This steady push for smaller and more efficient components, and the high volumes involved, continue to sustain consumer electronics as the largest end-use category across the broader market.
Automotive is projected to be the fastest-growing end-use industry over the forecast period. Advanced driver assistance, electrification, and software-defined vehicles require reliable embedded non-volatile memory that withstands wide temperature ranges. Automotive qualification milestones for resistive memory are clearing the path to revenue, and as vehicles adopt more computing, automotive applications continue to close the gap with consumer electronics in overall market demand.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
Asia Pacific |
China |
38.40% |
|
North America |
United States |
78.20% |
|
Europe |
Germany |
34.60% |
|
Latin America |
Brazil |
44.20% |
|
Middle East & Africa |
Israel |
36.40% |
Asia Pacific Memristor Market Insights
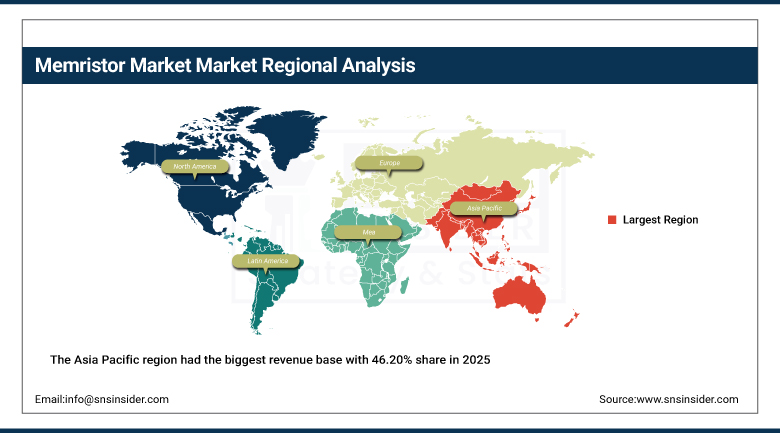
The Asia Pacific region had the biggest revenue base with 46.20% share in 2025. This is because it is home to most of the world's biggest producers of memory and foundries, as well as government programs favoring indigenous development of memory and logic. China remains the bedrock of demand in the region through ambitious initiatives and heavy research and development investments made by local chip makers and universities in the memristor sorters and computer architectures.
South Korea and Japan add further weight through major memory chip producers and research programs, including government funding for ultra-low-power analog compute-in-memory and university research for multilevel compute-in-memory chips. Process capability from Taiwan's foundry landscape is what ensures that the overall region maintains the biggest revenue base up to 2035.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Memristor Market Insights
North America represents a significant regional market for memristors, anchored by the United States' concentration of leading semiconductor firms, national laboratories, and venture-backed startups. The United States accounts for the substantial majority of regional demand, supported by federal investment in domestic semiconductor manufacturing, defense and aerospace requirements, and heavy interest in low-power artificial intelligence hardware.
Canada contributes additional regional research and development activity through university programs in neuromorphic computing. Continued trusted foundry qualification and commercialization efforts are expected to support steady regional growth, even as growth in percentage terms trails faster-scaling European markets building up from smaller bases. Partnerships between startups, universities, and established chipmakers also help translate laboratory results into products, keeping the region a key source of intellectual property for the global market.
Europe Memristor Market Insights
Europe is projected to be the fastest-growing region, registering a CAGR of 40.30% during 2026-2035, supported by a strong public research ecosystem, automotive demand for embedded memory, and coordinated funding for semiconductor sovereignty. Germany anchors regional demand through its automotive and industrial electronics sectors, which are increasingly interested in resistive memory that can be qualified for demanding operating conditions.
France, the Netherlands, and Italy contribute additional depth through advanced research institutes and semiconductor manufacturers, and European fabs are adding embedded non-volatile memory options. Regional initiatives aimed at reducing reliance on imported chips, together with cooperation between research institutes and industry on analog and embedded memory, are expected to keep Europe growing faster than other regions in percentage terms through the forecast period.
MEA & Latin America Memristor Market Insights
Latin America's market is anchored by Brazil, which accounts for the majority of regional demand through its consumer electronics and industrial sectors, though local semiconductor manufacturing remains limited and most demand is met through imported components. Mexico adds further volume through electronics assembly.
The Middle East & Africa region is growing from a small base, with activity concentrated in Israel, where a strong technology and research ecosystem has produced several memory technology companies. Gulf Cooperation Council states are investing in advanced technology programs, though commercial memristor demand remains at an early stage across the region.
Market Dynamics
Growth Drivers: Energy-Efficient Computing and Neuromorphic Demand
Rising demand for energy-efficient computing represents the primary growth driver, as artificial intelligence workloads and data center power consumption push designers toward architectures that reduce data movement. Memristors can store and compute in the same device, offering lower power and latency than conventional memory-and-processor separation, which makes them a compelling option for edge inference and embedded intelligence.
Growing demand for high-speed non-volatile memory and progress in neuromorphic computing provide a second major driver. Embedded flash is becoming difficult to scale, opening the door to resistive memory in microcontrollers, automotive systems, and industrial devices. Licensing agreements with major suppliers, automotive qualification, and public funding for compute-in-memory research further support market expansion.
Restraints: Manufacturing Scale-Up and Lack of Standardization
Restriction from achieving commercial production in mass quantities is one of the genuine constraints that exist in the market. Variability of the device, endurance limitations, and issues of compatibility present difficulties in obtaining the yield levels and reliability needed in manufacturing high volume products, while qualification in automotive and industrial applications involves capital expenditure and more time. The majority of advancements still are in laboratory or pilot stage rather than in full manufacturing.
Another constraint is the lack of standardization and test procedures. In the absence of standards, design kits, and reference architecture, there are problems in comparison and incorporation of the devices into the current chip flow process. Competing against the established memories and magnetic memories with strong supply chain also presents some constraints to immediate displacement of this technology.
Opportunities: Automotive Qualification and In-Memory AI Acceleration
Continued automotive qualification of resistive memory offers a substantial opportunity, as vehicles adopt more processing and require reliable embedded memory that tolerates wide temperature ranges. Companies that secure automotive-grade qualification and foundry support can access long-lifecycle, high-value design wins in a segment that is expected to grow faster than other end-use industries.
The expansion of in-memory and neuromorphic AI acceleration presents a further avenue for growth, as laboratories move toward production silicon and governments fund programs in analog compute-in-memory. Extreme-environment devices that operate at very high temperatures also open niche markets in aerospace, industrial systems, and deep-space computing, giving developers with differentiated materials and architectures room to establish leadership.
Recent Developments:
-
2025: researchers from Peking University and the Chinese Institute for Brain Research unveiled a memristor-based sorting system designed to improve artificial intelligence efficiency.
-
2025: the University of Tokyo unveiled a multilevel tantalum oxide compute-in-memory chip that balances storage density with ten-year data retention.
-
2026: Everspin Technologies signed a 10-year manufacturing agreement with Microchip Technology to support its magnetic memory products.
Memristor Companies are
-
Crossbar Inc.
-
Everspin Technologies, Inc.
-
Fujitsu Semiconductor Memory Solution
-
Honeywell International Inc.
-
Knowm Inc.
-
STMicroelectronics N.V.
-
Weebit Nano Ltd.
-
TetraMem Inc.
-
Toshiba Corporation
-
Samsung Electronics Co., Ltd.
-
International Business Machines Corporation
-
Intel Corporation
-
Micron Technology, Inc.
-
Rambus Inc.
-
Hewlett Packard Enterprise
-
TECHiFAB GmbH
-
SK hynix Inc.
-
Taiwan Semiconductor Manufacturing Company
Memristor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.56 Billion |
| Market Size by 2035 | USD 14.12 Billion |
| CAGR | CAGR of 38.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Spin-Based & Magnetic, Molecular & Ionic Thin Film, Hybrid CMOS-Memristor, Others) • By Material (Metal Oxides, Chalcogenides, Organic Polymers, Others) • By Application (Memory Storage, Neuromorphic Computing, Signal Processing, Sensing, Others) • By End-Use Industry (Consumer Electronics, IT & Telecommunications, Automotive, Healthcare, Industrial, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Avalanche Technology, Inc., Crossbar Inc., Everspin Technologies, Inc., Fujitsu Semiconductor Memory Solution, Honeywell International Inc., Knowm Inc., Renesas Electronics Corporation, STMicroelectronics N.V., Weebit Nano Ltd., TetraMem Inc., Toshiba Corporation, Samsung Electronics Co., Ltd., International Business Machines Corporation, Intel Corporation, Micron Technology, Inc., Rambus Inc., Hewlett Packard Enterprise, TECHiFAB GmbH, SK hynix Inc., Taiwan Semiconductor Manufacturing Company |

Frequently Asked Questions
Key players include Avalanche Technology, Crossbar, Everspin Technologies, Fujitsu Semiconductor Memory Solution, Honeywell, Knowm, Renesas Electronics, STMicroelectronics, Weebit Nano, and TetraMem, among others.
Continued automotive qualification of resistive memory and the expansion of in-memory and neuromorphic AI acceleration represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by rising demand for energy-efficient computing, combined with progress in neuromorphic computing and demand for high-speed non-volatile memory.
By End-Use Industry, Consumer Electronics dominated the market with a 31.55% share in 2025, reflecting continuous demand for compact, low-power memory in smartphones and wearables.
Asia Pacific dominated the market with a 46.20% share in 2025, supported by the region's concentration of leading memory manufacturers and foundries, led by China.
