
Mercaptan Market Report Scope & Overview:
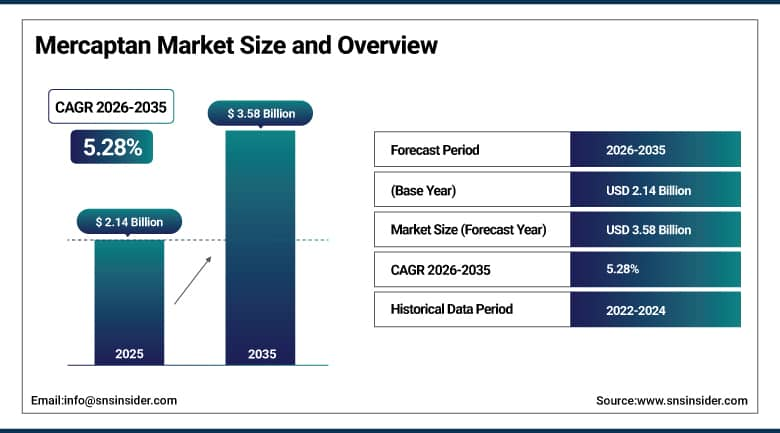
The Mercaptan Market size was valued at USD 2.14 Billion in 2025 and is expected to reach USD 2.25 Billion in 2026, rising to USD 3.58 Billion by 2035. The market is forecast to expand at a CAGR of 5.28% during 2026–2035. Mercaptans, also called thiols, are organosulfur compounds that carry a sulfhydryl group. Methyl and ethyl mercaptan serve as intermediates for methionine, as odorants that make natural gas and propane detectable, and as building blocks for crop protection products, while dodecyl grades act as chain transfer agents in synthetic rubber and plastics.
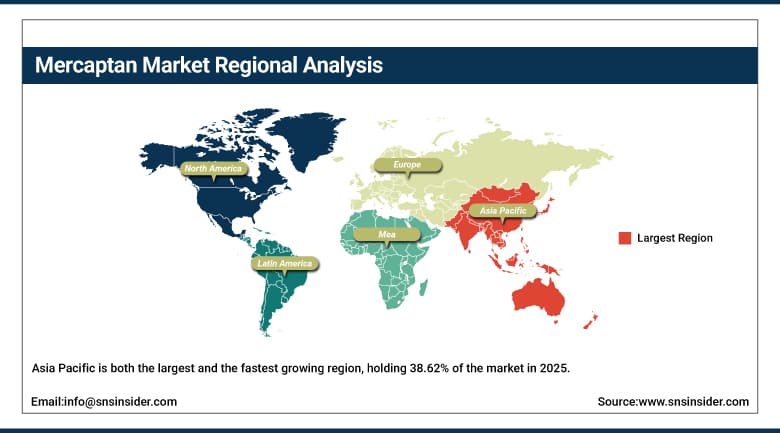
Asia Pacific accounted for the largest share of the market, at 38.62% in 2025, because China, Japan, South Korea and Singapore host large methionine, rubber and agrochemical industries. The region is also the fastest growing, expected to register a CAGR of 6.02% as feed additive capacity and gas distribution networks keep expanding. North America follows, supported by integrated Gulf Coast producers and an extensive pipeline network, while Europe relies on feed additive and specialty chemical demand. Rising meat consumption, expanding gas networks and tighter safety expectations continue to widen the base of buyers.
To Get More Information On Mercaptan Market - Request Free Sample Report
Key Report Takeaways:
-
By type, methyl mercaptan held a 43.18% share in 2025, while ethyl mercaptan is the fastest growing.
-
By application, methionine production held a 44.28% share in 2025, while agrochemical intermediates is the fastest growing.
-
By end use, animal nutrition held a 46.84% share in 2025, while oil and gas and utilities is the fastest growing.
-
By region, Asia Pacific held a 38.62% share in 2025 and is also the fastest growing.
Market Trends and Insights:
Methionine producers are integrating backward into methyl mercaptan. Operating mercaptan units on the same site as methionine plants removes the need to ship a toxic, malodorous intermediate, lowers the carbon footprint of the finished amino acid and shields producers from supply disruption, which pushes new capacity toward large integrated hubs.
Gas utilities are widening the range of odorant mixtures. Distributors combine sulfur-free and mercaptan-based products to manage odor fade, pipeline compatibility and community complaints, and growth in hydrogen-ready and biomethane networks opens new testing and qualification work for odorant suppliers.
Specialty thiol derivatives are gaining weight in lubricants, detergents and leather processing. Producers sell polysulfides and thio-based additives through regional distributors, which extends the reach of large thiochemical groups into smaller formulators that value technical support and dependable supply.
Drivers Impact Analysis:
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Methionine and animal feed demand |
+3.12% |
Global |
Long term (4 years or more) |
|
Natural gas and LPG odorization |
+1.46% |
Asia Pacific and North America |
Medium term (2 to 4 years) |
|
Crop protection and agrochemical intermediates |
+1.04% |
Asia Pacific and Latin America |
Medium term (2 to 4 years) |
|
Rubber and plastics polymerization |
+0.82% |
Asia Pacific and Europe |
Short term (2 years or less) |
|
Pharmaceutical and specialty uses |
+0.52% |
Global |
Long term (4 years or more) |
Methionine and Animal Feed Demand
Methionine is the first limiting amino acid in poultry and swine diets, and nearly all synthetic methionine is made from methyl mercaptan, acrolein and hydrogen cyanide or related intermediates. In June 2026, the OECD and the Food and Agriculture Organization projected in their Agricultural Outlook 2026–2035 that global agricultural production will rise by 13.00% over the coming decade. Higher poultry and aquaculture output lifts feed additive use, so methionine plants and the mercaptan units that supply them keep expanding in Asia, Europe and the Americas. Integrated producers also benefit from lower logistics risk and better cost control.
Natural Gas and LPG Odorization
Natural gas and propane are colorless and odorless, so safety regulations in most countries require suppliers to add a distinctive smell that warns of leaks. Ethyl mercaptan is the standard odorant for LPG, and mixtures based on tertiary butyl and other mercaptans are widely used in gas grids. New distribution networks in Asia, expanding household connections and rising biomethane injection all add odorant volume, and utilities hold safety stock that supports steady purchases. Utilities also upgrade odorization stations and leak detection programs, and operators of propane cylinders in rural areas of Asia and Africa increase odorant purchases as household adoption rises.
Crop Protection and Agrochemical Intermediates
Several herbicides, insecticides and fungicides are produced from methyl mercaptan and related sulfur intermediates, including products for cereals, rice, soybeans and vegetables. Farmers in Brazil, India and Southeast Asia are increasing planted area and input intensity, while manufacturers in China and India expand formulation capacity for export. Registration of newer actives and growth in generic production keep intermediate purchases rising, even when product prices fluctuate. Contract manufacturers supply intermediates to multinational crop protection companies, and supply chain diversification away from single-country sourcing is creating opportunities for producers in India, Europe and the Americas. Long product life cycles also provide stable demand across seasons.
Rubber and Plastics Polymerization
Tertiary and normal dodecyl mercaptans control molecular weight during emulsion polymerization of styrene-butadiene rubber, nitrile rubber, acrylonitrile-butadiene-styrene and other polymers. Tire production, footwear, hoses and automotive parts rely on these grades, and growth in vehicle output across Asia raises consumption. Producers also tailor mercaptan quality for lower odor and tighter specifications, which supports premium pricing for high purity products. Demand for passenger and commercial vehicle tires in India, Southeast Asia and Africa is rising, and synthetic rubber plants are investing in capacity and better polymer grades. Chain transfer agents are a small cost item but a critical one, so buyers prioritize reliable supply over minor price differences.
Pharmaceutical and Specialty Uses
Thiols are building blocks for active pharmaceutical ingredients, electronic chemicals, mining collectors, lubricant additives and leather auxiliaries. Demand in these uses is smaller but stable, and customers pay for consistent purity and documented supply chains. Regional distributors expand their thiochemical portfolios to serve formulators, and specialty customers increasingly qualify two sources, which broadens the addressable base for established producers. Mining operations use thiol-based collectors in flotation, and electronics makers use sulfur-containing surface treatments for printed circuit boards and photoresist processes. Because volumes per customer are small, suppliers compete through service quality, packaging flexibility and regulatory documentation rather than price alone.
Restraints Impact Analysis:
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Toxicity, odor and handling restrictions |
-0.72% |
Global |
Long term (4 years or more) |
|
Raw material and sulfur price volatility |
-0.58% |
Global |
Short term (2 years or less) |
|
Alternative methionine and odorant routes |
-0.38% |
Europe and North America |
Medium term (2 to 4 years) |
Toxicity, Odor and Handling Restrictions
Methyl mercaptan is a flammable, toxic gas with a very low odor threshold, so storage, transport and use are tightly controlled. Producers invest in closed systems, emergency response and community monitoring, which raises operating cost. Neighbors of chemical plants and distribution terminals file complaints over odor releases, and permitting for new units can take years, especially in densely populated regions, which slows capacity additions and limits flexibility. Transport of liquefied methyl mercaptan requires specialized tankers and route approvals, which adds cost and limits trade to a small group of qualified carriers. Insurance premiums and training obligations also rise after any incident.
Raw Material and Sulfur Price Volatility
Mercaptans are made from methanol, hydrogen sulfide, sulfur and olefins, so their cost follows energy, sulfur and petrochemical markets. Sulfur supply is tied to refinery and gas processing output, and shortages or logistics disruptions can lift costs quickly, which shows how fast the input chain can move. Contract mechanisms pass part of the increase on, but smaller producers and distributors absorb margin pressure in volatile quarters. Disruptions in shipping lanes and energy markets add further variability, and customers in rubber, feed and gas distribution resist price changes outside contract formulas, so producers carry inventory and hedging costs.
Alternative Methionine and Odorant Routes
Fermentation-based methionine, hydroxy analogs and enzyme-based feed additives compete with chemically synthesized methionine in some markets, and feed formulators can lower inclusion rates through precise nutrition. In gas distribution, some utilities test sulfur-free odorants to reduce corrosion and catalyst poisoning, and hydrogen projects may require different chemistries. These alternatives remain small today, yet they may cap growth in selected applications over the forecast period. Producers of competing products invest in process improvements, and large feed companies run trials to confirm that alternative sources match animal performance. Any wider acceptance would shift purchases away from conventional intermediates.
Mercaptan Market Segment Analysis:
By Type, Methyl Mercaptan Dominates Mercaptan Market; Ethyl Mercaptan to Register Fastest Growth.
Methyl mercaptan represents 43.18% of the market in 2025 because it is the key intermediate for methionine, a feed additive produced at very large scale, and it also serves agrochemical and pharmaceutical synthesis. Most of the volume is consumed captively inside integrated plants, and merchant trade is limited by transport rules. Capacity additions at methionine hubs keep this segment well ahead of other types. Producers with captive supply enjoy lasting cost and quality advantages over smaller merchant sellers.
Ethyl mercaptan is projected to grow at a CAGR of 6.74% during 2026–2035. It is the standard odorant for LPG and a component of natural gas odorant mixtures, and it also serves as an intermediate in some agrochemicals. Expanding household gas connections in Asia, Africa and Latin America increase propane and gas distribution, and safety rules require reliable odorization, which supports steady volume growth. Odorant suppliers also sell tailored mixtures that match pipeline conditions and local odor preferences.
By Application, Methionine Production Dominates Mercaptan Market; Agrochemical Intermediates to Register Fastest Growth.
Methionine production accounts for 44.28% of the market in 2025, since feed producers add synthetic methionine to poultry, swine and aquaculture diets to improve growth and reduce protein use. Producers in Germany, France, Singapore, the United States, China and Spain operate large plants, and many have secured their mercaptan supply through on-site units. Meat consumption growth sustains long term expansion. Contracts between methionine makers and feed companies often run for several years, which supports predictable utilization and investment planning.
Agrochemical intermediates are expected to register the highest CAGR, at 6.34% from 2026 to 2035. Methyl mercaptan and related thiols feed into herbicides, insecticides and fungicides used on cereals, rice, soybeans and vegetables. Rising planted area in Latin America and South Asia, together with growth in generic active ingredient production, supports consistent demand from intermediate manufacturers and formulators. Manufacturers in India and China are also moving into higher value formulated products, which pulls additional intermediate volume through regional supply chains.
By End Use, Animal Nutrition Dominates Mercaptan Market; Oil and Gas and Utilities to Register Fastest Growth.
Animal nutrition represents a 46.84% share in 2025 because methionine consumption in compound feed dwarfs other mercaptan uses. Poultry integrators, swine producers and aquaculture farms depend on balanced amino acid supply, and feed millers in Asia and Latin America steadily raise inclusion of synthetic amino acids. Cost advantages from integration keep large producers firmly in control of this segment. Regional feed mills also negotiate multi-year supply agreements, which reinforce relationships with established amino acid suppliers and limit new entrants.
Oil and gas and utilities are projected to expand at a CAGR of 6.38% over 2026–2035. Gas distributors, LPG suppliers and pipeline operators purchase odorants to meet safety rules, and midstream firms use mercaptans in refining and sulfur management. New networks in Asia, growth in biomethane injection and stricter leak detection practices all raise odorant use. Safety codes in many countries require odorization of every distributed gas stream, so utilities purchase odorants regularly regardless of the economic cycle.
Geography Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
46.28% |
|
North America |
United States |
82.46% |
|
Europe |
Germany |
31.72% |
|
Latin America |
Brazil |
52.36% |
|
Middle East & Africa |
Saudi Arabia |
34.18% |
Asia Pacific Mercaptan Market
Asia Pacific is both the largest and the fastest growing region, holding 38.62% of the market in 2025 and projected to register a CAGR of 6.02% over 2026–2035. China leads, with a large methionine industry, big rubber and agrochemical sectors and a gas network that is expanding rapidly. Local producers are investing in larger plants that lower unit cost and reduce dependence on imports. Producers also export mercaptan-derived products to Southeast Asia and the Middle East, supporting regional trade and encouraging further capacity additions.
Japan hosts experienced thiochemical and feed additive producers, South Korea supplies rubber and electronics demand, and Singapore serves as a hub for integrated amino acid production. India raises consumption through agrochemicals, feed and city gas projects, while Southeast Asia adds tire and glove manufacturing. These sources of demand should keep the region ahead of the global rate. Australia supplies mining chemistry demand, and Vietnam, Thailand and Indonesia are building methionine, rubber and agrochemical formulation capacity as foreign investors diversify supply chains away from single locations.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Mercaptan Market
North America accounted for 26.84% of the market in 2025. The U.S. market was valued at USD 0.47 Billion in 2025 and is expected to register a CAGR of 4.68% during 2026–2035. Producers on the Gulf Coast operate integrated sulfur chemistry units serving feed additive plants, odorant formulators and agrochemical makers, and the extensive pipeline and propane distribution network sustains stable odorant demand. Large poultry integrators and a well developed propane retail sector maintain consistent demand for methionine and ethyl mercaptan odorants.
Canada contributes through oil sands sulfur chemistry and gas distribution, while Mexico is included in Latin America in this report. Mature safety rules and moderate vehicle and construction growth limit expansion, although reshoring of agrochemical intermediates and investment in biomethane provide pockets of growth for suppliers with strong technical service. Federal and state programs promoting renewable natural gas bring new odorization requirements, and reshoring of agrochemical intermediates offers further opportunity. Cross-border trade with Canada also shapes sourcing decisions for gas utilities and feed producers.
Europe Mercaptan Market
Europe held 21.48% of the market in 2025. Germany leads, supported by a strong chemical industry, amino acid producers and specialty thiochemical suppliers, while France and Belgium host important intermediates and feed additive sites. The region applies strict chemical safety and industrial emission rules, which shapes how mercaptans are stored and transported. The European Union regulation of classification, labeling and packaging of chemicals requires clear hazard communication for thiols, and producers maintain extensive safety documentation. Feed and polymer customers expect full traceability.
Spain, Italy and the Netherlands add demand through feed, leather, lubricants and agrochemicals, and utilities across the region maintain strict odorization practices. High energy cost challenges older units, yet established producers defend their position through integration, high purity grades and close relationships with regional formulators. Eastern European countries add rubber, tire and agrochemical production, and the United Kingdom maintains demand through gas distribution and specialty chemicals. Sustainability reporting rules encourage producers to document footprint reductions from integration and cleaner processes.
Latin America Mercaptan Market
Latin America accounted for 6.94% of the market in 2025. Brazil leads, with one of the largest poultry and swine sectors in the world and a vast agricultural area that consumes crop protection chemicals and feed additives. Most mercaptan-derived products are imported, so local demand follows trade flows and exchange rates. Local formulators and distributors import mercaptans and odorants, so supply reliability and price depend on shipping schedules and port capacity. Investment in feed mills continues as integrated poultry companies expand.
Mexico contributes through poultry production, rubber processing and propane distribution, while Argentina and Colombia add agricultural demand. Expanding LPG use in households and growing feed output support gradual expansion, and regional distributors play an important role in supplying small and mid-sized formulators. Peru and Chile require mining reagents, and Chile and Argentina also operate sizable livestock sectors, which sustain demand for feed additives. Regional integration agreements and growing local formulation capacity could encourage suppliers to build storage terminals and mixing facilities closer to customers.
Middle East & Africa Mercaptan Market
Middle East & Africa held 6.12% of the market in 2025. Saudi Arabia leads, supported by sour gas processing, sulfur availability and a large gas distribution system that requires odorants. The United Arab Emirates and Qatar add demand through petrochemical and gas infrastructure. Natural gas distribution is growing in Gulf cities, and the construction of new residential and industrial areas increases the need for odorization services. Agriculture in the region relies on imported crop protection products, giving suppliers a stable export market.
In Africa, South Africa has an established agrochemical and mining sector, while Egypt, Nigeria and Kenya expand household LPG use and poultry production. Limited local mercaptan manufacturing means most supply is imported, but sulfur recovery projects in the Gulf offer a path to future regional production. Industrial zones in Egypt and Morocco are attracting chemical investors, and poultry and aquaculture sectors are expanding across North Africa. Investment in sulfur handling and logistics will determine how quickly regional demand converts into local supply.
Competitive Landscape:
The Mercaptan Market is moderately consolidated. Large chemical groups such as Arkema, Chevron Phillips Chemical, Evonik, Adisseo and Novus International lead through integrated sulfur chemistry, methionine capacity and established odorant and polymer additive businesses, while regional producers and distributors serve local gas utilities, rubber makers and agrochemical firms. Competition centers on feedstock access, safe logistics, product purity and technical service.
Vendors follow several strategies. Leading groups integrate backward into methyl mercaptan, expand capacity near customers, strengthen distributor networks for specialty thiochemicals and reorganize business units to focus on high growth feed and specialty segments. Long term supply agreements with feed, gas and polymer customers are common.
Mercaptan Market Industry Leaders:
1. Arkema: French specialty chemicals group producing methyl and ethyl mercaptan, odorants and other thiochemicals.
2. Chevron Phillips Chemical: U.S. producer of mercaptans, including n-dodecyl mercaptan for polymerization.
3. Evonik: German specialty chemicals group with integrated methyl mercaptan and methionine production.
4. Adisseo: French-headquartered feed additive producer with large methionine capacity.
5. Novus International: U.S. animal nutrition company with a dedicated methionine business unit.
Companies Covered in this Report:
-
Arkema S.A.
-
Chevron Phillips Chemical Company LLC
-
Evonik Industries AG
-
Adisseo
-
Novus International, Inc.
-
Lanxess AG
Recent Industry Developments:
-
June 2025: Novus International split its operations into a methionine business unit and a specialty feed ingredients unit.
-
March 2026: Adisseo reported that construction of its 150,000-ton powder methionine plant in Quanzhou, China, was more than 80.00% complete.
-
April 2026: Lanxess raised prices for its sulfur-based products by 40.00%.
-
July 2026: Evonik completed the backward integration of its Mobile, Alabama, methionine hub with an on-site methyl mercaptan unit.
-
August 2026: Arkema expanded its distribution partnership with Eigenmann & Veronelli in Italy to cover detergency, lubricant and leather thiochemicals.
-
August 2026: Chevron Phillips Chemical issued a revised safety data sheet for n-dodecyl mercaptan, a polymerization process regulator.
Scope and Research Methodology
This study estimates the Mercaptan Market for 2025 as the base year and forecasts it through 2035. The scope covers methyl, ethyl, butyl, dodecyl and other alkyl mercaptans produced for sale or for captive use, supplied for methionine production, gas odorization, agrochemical intermediates, polymerization regulation and other uses. Values are reported in USD at the producer level. Segmentation covers type, application, end use and region. Related sulfur chemicals such as dimethyl disulfide and thioglycolic acid are excluded. Prices are reported in nominal terms, and currency effects are normalized across regions.
Secondary research included company annual reports, investor presentations and filings, regulator and government databases, industry association data, product documentation, and peer-reviewed and industry publications. Primary research consisted of structured interviews and surveys with executives, product and business heads, procurement managers and technical specialists across the value chain. These inputs were used to validate production volumes, pricing and the mix of types, applications and end uses. Interviews covered mercaptan producers, methionine makers, gas utilities and polymer manufacturers, which allowed assumptions on capacity and demand to be tested against current practice. Responses from different stakeholder groups were compared, and conflicting views were resolved through follow-up discussions with additional experts and review of plant-level evidence.
Market size was built from the bottom up using producer revenue, plant capacity and utilization, and was cross-checked from the top down against methionine, odorant and rubber demand. Triangulation across these views fixed the base year value. Forecasts reflect feed demand, gas network growth, feedstock prices, safety regulation, capacity additions and macroeconomic conditions, and segment and regional shares were assigned from consumption patterns in each setting. An analyst quality review checked consistency before release. The report also profiles competitive positioning using product portfolios, capacity, geographic reach and announced investments, and each company profile was verified against published company material and expert feedback.
Mercaptan Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.14 Billion |
| Market Size by 2035 | USD 3.58 Billion |
| CAGR | CAGR of 5.28% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Methyl Mercaptan, Ethyl Mercaptan, Tertiary Dodecyl Mercaptan, and Butyl and Other Mercaptans) • By Application (Methionine Production, Gas Odorization, Agrochemical Intermediates, Polymerization Regulators, and Others) • By End Use (Animal Nutrition, Oil and Gas and Utilities, Agriculture, Plastics and Rubber, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Chevron Phillips Chemical Company LLC, Evonik Industries AG, Adisseo, Novus International, Inc., Lanxess AG |

Frequently Asked Questions
Arkema, Chevron Phillips Chemical, Evonik, Adisseo and Novus International lead.
Toxicity and handling rules, sulfur and feedstock price swings and alternative routes restrain faster growth.
Ans: The outbreak has had a considerable influence on global manufacturing processes, trade, and supply chains for chemicals and minerals. Due to market participants' need to close production facilities or run them at less than optimal production levels in order to prevent the spread of the new coronavirus COVID-19, mecaptan output fell during the COVID-19 pandemic. Mercaptan manufacturing has also been hampered by the scarcity of raw materials due to supply disruptions brought on by border and trade restrictions. However, some significant market participants have kept running their manufacturing plants. Additionally, the low demand from the end-use sectors and the falling costs of raw materials have led to surplus stockpiles and decreased production.
The market was valued at USD 2.14 Billion in 2025 and is projected to reach USD 3.58 Billion by 2035, growing at a CAGR of 5.28% during 2026–2035.
Asia Pacific leads, with a 38.62% share in 2025, supported by large methionine, rubber and agrochemical industries.
Methyl mercaptan, methionine production and animal nutrition lead, while ethyl mercaptan, agrochemical intermediates and oil and gas and utilities grow fastest within their segments.
Asia Pacific is also expected to grow fastest, at a CAGR of 6.02% during 2026–2035, led by China and India.
