
Molecular Quality Controls Market Report Scope & Overview:
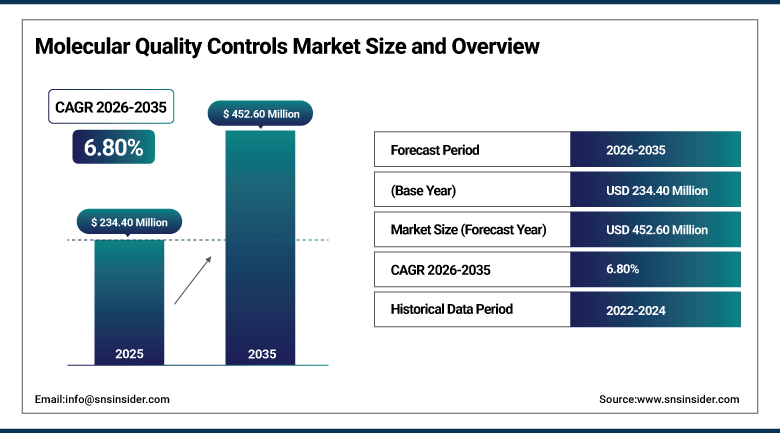
The Molecular Quality Controls Market was valued at USD 234.40 Million in 2025 and is expected to reach USD 452.60 Million by 2035, growing at a CAGR of 6.80% from 2026-2035.
The Molecular Quality Control Market includes reference materials, synthesized controls, and proficiency panels that are utilized for confirming the accuracy, precision, and performance reliability of molecular diagnostic tests on PCR, NGS, or any other nucleic acid amplification test platform. This market is driven by increasing use of molecular diagnostics for infectious disease, oncology, or genetic tests, as well as regulatory compliance requirements to assess the performance of these assays regularly. Historically, the market was growing from positive/negative controls to quantified reference standard or consistency materials due to increased regulatory pressures following diseases such as SARS-CoV-2 outbreak, forcing vendors to ramp up their production capacity. Independent vendor-neutral controls still remain popular among laboratories due to their objectivity.
In December 2024, LGC Limited announced the acquisition of DiaMex GmbH, a manufacturer of third-party serology and molecular quality controls used in clinical laboratories and blood banks, a transaction framed as enhancing product choice in the core laboratory and blood-bank segments while complementing LGC's existing SeraCare-branded molecular quality control portfolio.
To Get more information Molecular Quality Controls Market - Request Free Sample Report
Molecular Quality Controls Market Trends
-
Growing laboratory preference for vendor-neutral, independent controls that satisfy accreditation requirements across multiple instrument platforms.
-
Rising adoption of multi-analyte controls that allow laboratories to verify numerous assay parameters using a single reference material.
-
Continued consolidation among quality control and reference material suppliers through targeted regional acquisitions.
-
Expanding demand for oncology and companion diagnostic quality controls tied to growing precision medicine adoption.
-
Increasing regulatory emphasis on lot-to-lot consistency and quantified reference standards following pandemic-era diagnostic scrutiny.
U.S. Molecular Quality Controls Market Outlook
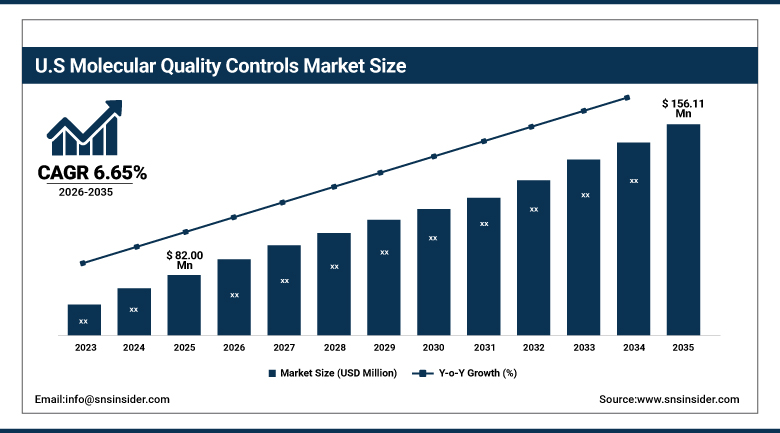
The U.S. Molecular Quality Controls Market was valued at USD 82.00 Million in 2025 and is expected to reach USD 156.11 Million by 2035, growing at a CAGR of 6.65% from 2026-2035.
The US continues to dominate the molecular quality controls industry as the biggest individual market on account of its extensive system of accredited clinical laboratories, substantial manufacturing of molecular diagnostics reagents, and strict regulations under which performance verification of assays must be done on a continuous basis. The domestic vendors like Bio-Rad, Thermo Fisher Scientific, and the SeraCare range of LGC have established deep ties within hospital, reference, and public health laboratories around the country. Molecular oncology and companion diagnostics tests continue to drive demand for quality controls for more complicated test formats.
In April 2024, Bio-Rad Laboratories entered a collaboration agreement with Oncocyte Corporation to co-commercialize the GraftAssure assay, which uses droplet digital PCR technology on Bio-Rad's QX600 platform to quantify donor-derived cell-free DNA for transplant rejection monitoring, with Bio-Rad securing exclusive global distribution rights outside the United States and Germany.
Molecular Quality Controls Market Segment Analysis
-
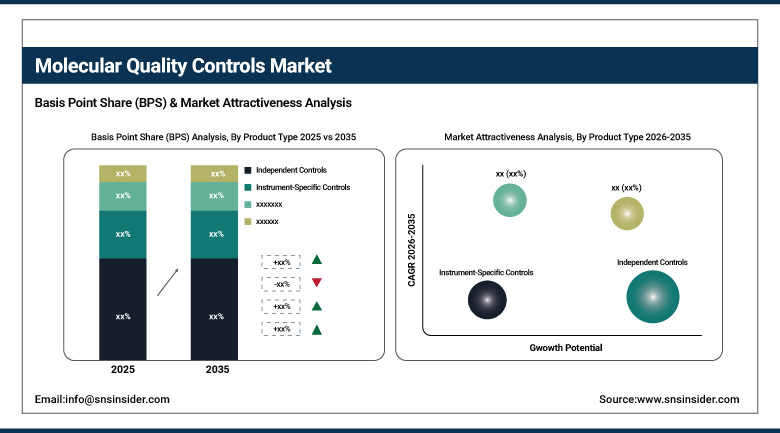
By Product Type, the Independent Controls segment dominated the Molecular Quality Controls Market with approximately 57.52% share in 2025, while the Instrument-Specific Controls segment is the fastest growing with a CAGR of approximately 7.85%.
-
By Analyte Type, the Single-Analyte segment dominated the Molecular Quality Controls Market with approximately 61.40% share in 2025, while the Multi-Analyte segment is the fastest growing with a CAGR of approximately 8.20%.
-
By Application, the Infectious Disease Diagnosis segment dominated the Molecular Quality Controls Market with approximately 44.75% share in 2025, while the Oncology Testing segment is the fastest growing with a CAGR of approximately 8.65%.
By Product Type, Independent Controls dominate, and Instrument-Specific Controls grow fastest
Independent controls held the largest product-type share in 2025, reflecting laboratories' preference for vendor-neutral verification tools manufactured separately from the test kits they validate, which satisfies accreditation requirements for objective, unbiased assay performance assessment across multiple instrument platforms. Because independent controls are not tied to a single manufacturer's assay chemistry, they also help laboratories identify performance issues that instrument-specific controls, designed to work optimally with a particular assay, might not detect.
Instrument-specific controls are the fastest-growing product-type segment as molecular diagnostic platform manufacturers increasingly bundle proprietary quality control materials with new assay launches, particularly for complex next-generation sequencing and companion diagnostic platforms where instrument-specific optimization delivers measurable performance advantages. The proliferation of new molecular diagnostic platforms entering clinical use is directly expanding the addressable market for instrument-specific controls tailored to each new system.
By Analyte Type, Single-Analyte dominates, and Multi-Analyte grows fastest
Single-analyte controls have the highest share by analyte type due to their popularity in hospital and reference labs where single-plex tests are performed, since single-analyte controls are easier to analyze and interpret and have a very low risk of cross reactivity, making them an optimal option for routine diagnostics.
Multi-analyte controls are the fastest growing segment by analyte type since many laboratories have switched to multi-analyte controls, which are combination reference materials that verify the performance of all assay parameters using one control sample, instead of having more than thirty different controls historically needed for complete quality control processes in the past.
By Application, Infectious Disease Diagnosis dominates, and Oncology Testing grows fastest
Infectious Disease Diagnosis held the largest application share in 2025, reflecting the long-established use of molecular quality controls in verifying HIV, hepatitis, and respiratory pathogen assay performance, a category that saw substantial capacity expansion following the SARS-CoV-2 pandemic as laboratories scaled molecular testing infrastructure and regulatory scrutiny of diagnostic accuracy intensified.
Oncology Testing is the fastest-growing application segment as expanding adoption of molecular and companion diagnostic testing for cancer treatment selection drives demand for specialized quality control materials validated for tumor marker, liquid biopsy, and next-generation sequencing-based oncology assays. Rising global cancer incidence and continued growth in precision oncology treatment approaches, which depend on accurate molecular biomarker testing, are reinforcing this segment's above-average growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
83.60 |
|
Europe |
Germany |
28.75 |
|
Asia Pacific |
China |
36.90 |
|
Middle East & Africa |
United Arab Emirates |
31.45 |
|
Latin America |
Brazil |
44.20 |
North America Molecular Quality Controls Market Insights
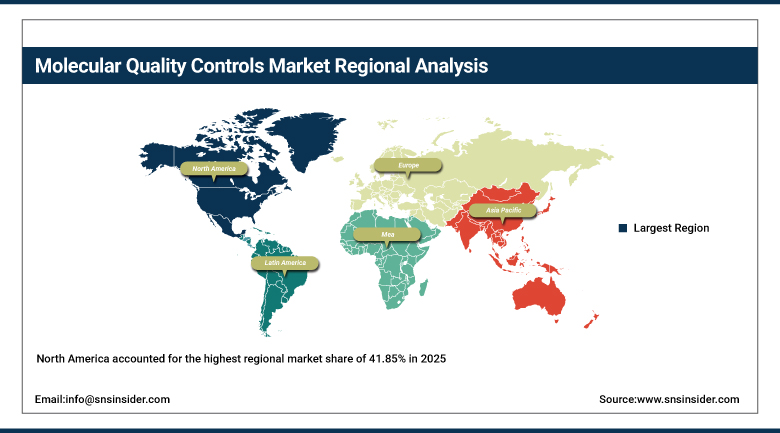
North America accounted for the highest regional market share of 41.85% in 2025, driven by the presence of a vast number of accredited clinical laboratories, advanced healthcare infrastructure, and strict regulations imposed by CLIA and FDA for regular molecular test performance validation. The major players in this region include Bio-Rad Laboratories, Thermo Fisher Scientific, and LGC's SeraCare brand.
Future growth of the molecular oncology and companion diagnostics industry, along with investments made in public health laboratories for the surveillance of infectious diseases after the COVID-19 pandemic, are expected to drive the regional market further. Canada, too, generates regional demand due to its accredited clinical laboratories and public health testing facilities.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Molecular Quality Controls Market Insights
Asia Pacific is the fastest-growing region in the Molecular Quality Controls Market, expected to witness a CAGR of approximately 7.90% during the forecast period from 2026 to 2035, owing to the rapid growth of the adoption of molecular diagnostics, increasing number of accredited laboratories, and rising investments made by the government towards the development of genomic and precision medicine infrastructures in China, Japan, and India. The rapidly growing molecular diagnostics testing infrastructure in China is driving the demand for independent as well as instrument-specific quality controls.
Japan has an established molecular diagnostics testing infrastructure that contributes a sizable portion of the demand for infectious disease diagnostics, while the growing network of accredited clinical and reference laboratories in India is driving incremental regional demand. The rising investments made by the governments towards genomic research and rising adoption of precision oncology across the region is anticipated to drive the above average growth of the region in the coming years.
Europe Molecular Quality Controls Market Insights
Europe represents a significant molecular quality controls market, shaped by the EU's In Vitro Diagnostic Regulation, which has tightened certification requirements for quality control materials and reference standards used with in vitro diagnostic devices sold across member states. Germany leads regional demand, supported by a well-established molecular diagnostics manufacturing base and extensive accredited clinical laboratory network.
The United Kingdom, France, and other Western European markets contribute significant additional regional demand, with the UK home to established suppliers including Randox Laboratories and its Qnostics subsidiary, which supply analytical panels and external quality assessment solutions supporting infectious disease testing accuracy across the region. Continued regulatory tightening under the EU's In Vitro Diagnostic Regulation is expected to sustain steady demand for certified quality control materials through the forecast period.
MEA & Latin America Molecular Quality Controls Market Insights
The Middle East & Africa molecular quality control market is experiencing growth due to investments made in healthcare facilities and diagnostics laboratories by countries that are part of the Gulf Cooperation Council with the UAE being the main demand driver due to its position as a healthcare and medical tourism center in the region. Investment in clinical laboratories within the entire region is set to contribute to the adoption of standard quality control procedures.
Brazil is the market leader in Latin America, with growth in both the accredited clinical laboratory sector and the adoption of molecular diagnostics contributing to rising demand for quality control materials. Mexico adds to regional demand in Latin America owing to expansion of its clinical laboratory sector.
Market Dynamics
Growth Drivers: Molecular Diagnostics Expansion and Laboratory Accreditation Requirements
The rapid global expansion of molecular diagnostics testing, spanning infectious disease, oncology, and genetic testing applications, remains the primary driver of molecular quality controls demand, as each new assay and testing platform introduced into clinical use requires corresponding quality control materials to verify performance before and during routine use. The proliferation of next-generation sequencing and companion diagnostic testing is directly expanding the range of specialized quality control materials laboratories must maintain.
Growing numbers of accredited clinical laboratories worldwide, combined with tightening regulatory requirements for diagnostic accuracy following heightened scrutiny after the SARS-CoV-2 pandemic, are reinforcing this driver by making routine quality control verification a non-negotiable component of laboratory accreditation rather than a discretionary best practice. This regulatory-driven demand provides molecular quality controls suppliers with unusually stable, accreditation-anchored revenue visibility relative to many other diagnostics-adjacent product categories.
Restraints: High Development Cost and Fragmented Regulatory Requirements
The development and validation of quality control materials on emerging test platforms involves significant investments in characterizing reference materials, stability studies, and regulatory compliance documentation, thereby constituting an effective barrier to entry that slows down the speed of expansion of suppliers into the increasing array of molecular test platforms entering the marketplace.
The fragmented nature of regulatory compliance, including the In Vitro Diagnostic Regulation of the European Union and national accreditation standards, increases costs and complexities for suppliers who wish to sell their quality control products internationally, often having to go through separate certification procedures for products that are, in essence, identical in each market. The fragmented regulatory environment is especially detrimental to small specialized suppliers compared to large diversified diagnostics firms that have regulatory departments.
Opportunities: Companion Diagnostics Expansion and Emerging Market Laboratory Accreditation
The continued expansion of companion diagnostic testing tied to precision oncology treatment selection presents a significant opportunity for suppliers to develop specialized quality control materials validated for increasingly complex molecular biomarker panels, an application where testing accuracy carries direct treatment decision consequences and where laboratories are willing to pay a premium for rigorously validated control materials.
Expanding clinical laboratory accreditation programs across emerging markets in Asia Pacific, the Middle East, and Latin America present a further opportunity for suppliers to establish early distribution relationships as newly accredited laboratories build out their quality control programs from the ground up. Suppliers that establish strong regional distribution and technical support capability in these fast-growing markets are positioned to capture a disproportionate share of incremental demand as laboratory accreditation continues to expand globally.
Recent Developments:
-
November 2024- Bio-Techne Corporation obtained In Vitro Diagnostic Regulation certification for its R&D Systems Hematology Controls and Calibrators, confirming compliance with EU in vitro diagnostic device standards.
-
May 2023- ZeptoMetrix Corporation introduced PROtrol, a new product line designed for antigen-based diagnostic methods to mimic true clinical specimens and monitor lateral-flow immunoassay performance.
-
August 2022- Bio-Rad Laboratories completed its acquisition of Curiosity Diagnostics, facilitating entry into molecular disease testing and complementing its Clinical Diagnostics product offerings.
Molecular Quality Controls Market Key Players
-
LGC Limited (SeraCare)
-
QIAGEN N.V.
-
Microbiologics, Inc.
-
Maine Molecular Quality Controls, Inc.
-
Randox Laboratories Ltd.
-
Streck, Inc.
-
Danaher Corporation
-
ZeptoMetrix Corporation
-
Bio-Techne Corporation
-
F. Hoffmann-La Roche Ltd.
-
Abbott Laboratories
-
Siemens Healthineers AG
-
QuidelOrtho Corporation
-
Sysmex Corporation
-
Microbix Biosystems Inc.
-
Fortress Diagnostics Ltd.
-
Helena Laboratories Corporation
-
Sun Diagnostics, LLC
Molecular Quality Controls Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 234.40 Million |
| Market Size by 2035 | USD 452.60 Billion |
| CAGR | CAGR of 6.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Independent Controls and Instrument-Specific Controls) • by Analyte Type (Single-Analyte and Multi-Analyte) • by Application (Infectious Disease Diagnosis, Oncology Testing, and Genetic Testing) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Bio-Rad Laboratories, Inc., Thermo Fisher Scientific Inc., LGC Limited (SeraCare), QIAGEN N.V., Microbiologics, Inc., Maine Molecular Quality Controls, Inc., Randox Laboratories Ltd., Streck, Inc., Danaher Corporation, ZeptoMetrix Corporation, Bio-Techne Corporation, F. Hoffmann-La Roche Ltd., Abbott Laboratories, Siemens Healthineers AG, QuidelOrtho Corporation, Sysmex Corporation, Microbix Biosystems Inc., Fortress Diagnostics Ltd., Helena Laboratories Corporation, Sun Diagnostics, LLC |

Frequently Asked Questions
Key players in the Molecular Quality Controls Market include Bio-Rad Laboratories, Inc., Thermo Fisher Scientific Inc., LGC Limited (SeraCare), QIAGEN N.V., and Microbiologics, Inc., among others.
Key opportunities lie in developing specialized quality control materials for expanding companion diagnostic testing, and in establishing early distribution relationships in fast-growing emerging market laboratory accreditation programs.
The rapid global expansion of molecular diagnostics testing, combined with tightening laboratory accreditation and regulatory requirements for diagnostic accuracy, is the major growth factor.
By Product Type, the Independent Controls segment dominated the Molecular Quality Controls Market with approximately 57.52% share in 2025.
North America dominated the Molecular Quality Controls Market with approximately 41.85% share in 2025, supported by an extensive accredited clinical laboratory network and stringent regulatory requirements.
