
Oil and Gas Data Management Market Report Scope & Overview:
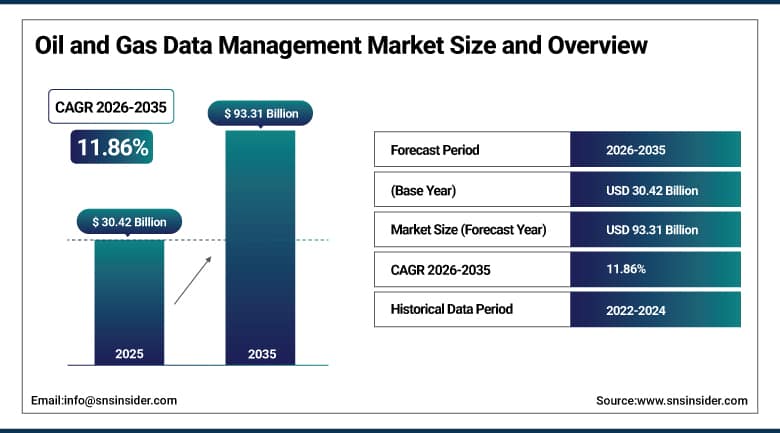
The Oil and Gas Data Management Market was valued at USD 30.42 Billion in 2025 and is expected to reach USD 93.31 Billion by 2035, growing at a CAGR of 11.86% from 2026-2035.
The Oil and Gas Data Management Market is showing consistent growth as the oil and gas industry looks to organize and analyze increasing amounts of subsurface, drilling, production, and asset data. The amount of seismic, well logging, real-time drilling sensor data, production data, and pipeline monitoring data being produced by the industry is measured in petabytes and must be managed and stored to be available for analysis. Traditionally, fragmented legacy systems, lack of standardization, and data silos have held back the industry's ability to gain value from this data. The adoption of the OSDU Data Platform, cloud computing, and industrial data platforms is allowing operators to build a standardized data foundation to support their activities in exploration, development, and production.
⮞In March 2026, Industrial AI for the energy sector moved forward when SLB expanded its collaboration with NVIDIA to develop an AI Factory for Energy, a reference environment built on domain-specific generative and agentic AI models running on SLB's digital platforms to help energy companies scale AI across their data and operations.
To Get More Information On Oil and Gas Data Management Market - Request Free Sample Report
Oil and Gas Data Management Market Trends:
-
Rising adoption of the OSDU Data Platform for standardized subsurface and well data.
-
Growing migration of seismic and production data to cloud platforms.
-
Expanding use of generative and agentic AI on industrial data foundations.
-
Increasing deployment of real-time drilling and production data streaming.
-
Rising investment in data governance, quality, and cybersecurity frameworks.
-
Growing integration of emissions and methane monitoring data into enterprise systems.
U.S. Oil and Gas Data Management Market Outlook:
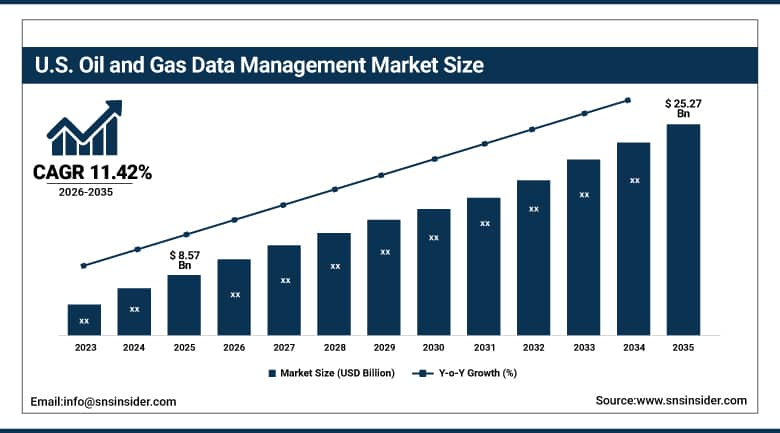
The U.S. Oil and Gas Data Management Market was valued at USD 8.57 Billion in 2025 and is expected to reach USD 25.27 Billion by 2035, growing at a CAGR of 11.42% from 2026-2035.
The U.S. Oil and Gas Data Management Market continues to grow due to the high levels of shale drillings, digitalization practices by operators, and the availability of technology and oil field services companies. Drilling, completions, and production data is produced in large amounts by operators in Permian Basin, Eagle Ford, Bakken, and Gulf of America and need to be managed and analyzed. ExxonMobil, Chevron, ConocoPhillips, and Occidental are making investments in cloud-based platforms, data lakes, and artificial intelligence to improve well performance and cost efficiency. SLB, Halliburton, and Baker Hughes, companies based in Houston, together with Microsoft, AWS, and Google Cloud are facilitating the process. Federal requirements for reporting methane emissions and sustainability disclosures are boosting the need for data.
⮞In May 2026, Digital wellsite execution in the United States advanced when Halliburton hosted its Technology Showcase in Houston, demonstrating its ZEUS IQ intelligent fracturing platform, OCTIV Auto Frac service, and LOGIX automation and remote operations platform for closed-loop drilling and geosteering control.
Oil and Gas Data Management Market Segment Analysis:
-
By Component, the Software segment dominated the Oil and Gas Data Management Market with approximately 66.84% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 13.12%.
-
By Deployment, the On-Premises segment dominated the Oil and Gas Data Management Market with approximately 56.42% share in 2025, while the Cloud segment is the fastest growing with a CAGR of approximately 14.86%.
-
By Application, the Exploration & Drilling segment dominated the Oil and Gas Data Management Market with approximately 31.24% share in 2025, while the Reservoir Management segment is the fastest growing with a CAGR of approximately 13.48%.
-
By Operation, the Upstream segment dominated the Oil and Gas Data Management Market with approximately 58.26% share in 2025, while the Midstream segment is the fastest growing with a CAGR of approximately 12.64%.
By Component, Software Dominates the Oil and Gas Data Management Market and Services Grows Fastest
Software dominated the market in 2025 since data management platforms, databases, analytics, and visualization applications are utilized to store, process, and analyze subsurface and operational data. Increasingly, operators are standardizing these solutions across their asset portfolios. Software solutions offered by companies, such as SLB, Halliburton, AVEVA, Emerson, Cognite, IBM, Oracle, and SAP can be used for seismic data management, well data, production history, and enterprise asset data. The subscription and enterprise licensing models create recurring revenues for vendors due to standardization of platforms across assets. Increased usage of AI-based software solutions for interpretation, prediction, and optimization activities drives up investments, thus making software the dominant segment in oil and gas data management market.
⮞In September 2024, software-led transformation in the oil and gas data space advanced when SLB launched its Lumi data and AI platform at the SLB Digital Forum in Monaco, embedding large language models and industry-specific generative AI into a single platform that leverages Cognite Data Fusion to connect, contextualize, and analyze subsurface, surface, planning, and operations data at scale.
Services are the fastest-growing component as providers are looking for support in their data migration, cleaning, integration, governance, and management processes. The demand for outsourcing of data management services is growing amongst mid-sized companies. Many organizations have decades worth of legacy seismic tapes, well files, and production data that needs to be digitized and cleaned up before it can be utilized in any modern system. Implementation of the OSDU Data Platform and transition to the cloud involves special competencies that only service providers, such as Accenture, Tata Consultancy Services, Wipro, Katalyst Data Management, and TGS can provide.
By Deployment, On-Premises Dominates the Oil and Gas Data Management Market and Cloud Grows Fastest
On-premises deployment led the market in 2025, owing to the fact that most oil and gas firms still store their confidential subsurface, reservoir, and operational data on their own data centers. Most firms carry out seismic processing on their on-premises high-performance computing clusters, which are close to their engineering teams. Reasons such as data sovereignty, cybersecurity, latency in remote facilities, and compliance with certain regulations in other nations continue to favor the use of the on-premises model. The national oil firms in the Middle East and Asia usually need local storage of data in the interest of strategic information.
Cloud deployment is the fastest-growing segment due to the shift in operators storing their seismic data archives, well data, and production operations on cloud-based platforms, such as Microsoft Azure, Amazon Web Services, and Google Cloud. Cloud-based deployments and hybrid cloud models are also helping operators achieve a balance between security and flexibility. Benefits of cloud include scalable storage and elastic computing for seismic data processing and AI operations and better collaboration within global teams. OSDU Data Platform is available through managed services from various cloud providers, which speeds up its adoption. Low infrastructure cost, rapid development of applications, and security of data on clouds will be key factors driving the fastest-growing deployment categories in the oil and gas data management market.
⮞In 2026, cloud-based OSDU adoption gained momentum when Amazon Web Services selected 47Lining and Hitachi Digital Services as its strategic delivery partner to deliver Energy Data Insights on AWS, a fully managed as-a-Service offering that helps operators stand up OSDU-compliant subsurface and well-data environments on the cloud without building the infrastructure in-house.
By Application, Exploration & Drilling Dominates the Oil and Gas Data Management Market and Reservoir Management Grows Fastest
Exploration and drilling led the market in 2025, due to the high amounts of data being collected by such activities in the oil and gas industry through surveys, well logs, core data, and real-time drilling data. Exploration needs large and reliable volumes of data to be accessed very quickly. The three dimensional and four-dimensional seismic datasets could amount to several petabytes per survey, necessitating large capacity storage and dedicated systems. Real-time drilling data plays an important role in geosteering, optimization of drilling process, and safety, thereby making the need for a platform higher.
Reservoir management is the fastest-growing application as operators leverage the power of integrated data and AI to increase production from their reservoirs while cutting back on development costs. Management of reservoirs can help make reserve calculations and investment decisions more accurate. Reservoir modeling integrates seismic, well, production, and pressure data in order to predict the performance of the well and determine the placement of infill wells and optimize water and gas injections. Digital reservoirs and digital oil fields need to be supported by continuous data integration between all relevant disciplines. Projects for carbon capture and storage require reservoir data management as well.
⮞In 2026, reservoir management data integration advanced in Brazil when Petrobras moved to deploy AI and digital rock models for its Mero field in the Libra Block, aiming to build high-resolution conceptual models of the area's complex, high-salinity carbonate reservoir and reduce uncertainty in well placement and long-term production forecasting.
By Operation, Upstream Dominates the Oil and Gas Data Management Market and Midstream Grows Fastest
Upstream operations led the market in 2025, as exploration, development, and production processes result in large and most complex data in the industry. In addition, the use of upstream data for regulatory reports, partnership communication, and reserves estimation is important. Upstream organizations have to deal with seismic data, well data, reservoir models, production data, and equipment data for multiple assets and joint ventures. For instance, industry initiatives, such as OSDU Data Platform are mainly concerned about upstream subsurface and well data. Capital intensive nature of the business and the importance of making better subsurface decisions make significant investments into data management.
Midstream operations are the fastest-growing segment as the investments being made by pipeline, storage and liquefied natural gas companies to utilize data platforms for integrity management, leak detection, and regulation. A majority of midstream companies are also investing in digitizing their paper records and as-built documents. Pipeline companies collect inspection data, sensor data, maintenance information, and geospatial information on assets covering hundreds of kilometers. There are increased regulatory pressures for pipeline safety and methane emissions reduction, which have increased demands for accurate and auditable data records. Increased liquefied natural gas exports from countries, such as the United States and Qatar have increased data demands even further.
⮞In July 2026, midstream data integration took a step forward when Forsite launched PatrolView, an AI-powered aerial intelligence platform that unifies pipeline patrol, hyperspectral liquid-leak detection, methane plume monitoring, and DOT compliance reporting into a single data system, already deployed across more than 70 North American pipeline operators.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.36% |
|
Asia Pacific |
China |
36.48% |
|
Europe |
Norway |
26.84% |
|
Latin America |
Brazil |
42.62% |
|
Middle East & Africa |
Saudi Arabia |
38.46% |
North America Oil and Gas Data Management Market Insights
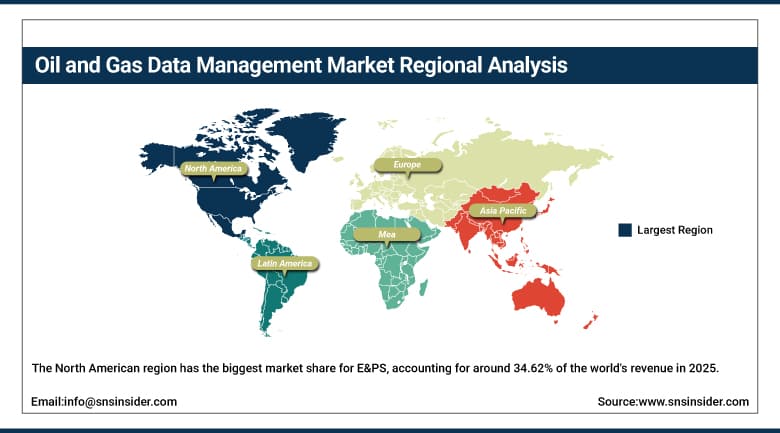
The North American region has the biggest market share for E&PS, accounting for around 34.62% of the world's revenue in 2025, owing to the high number of shale wells drilled, high digital adoption rate, and the presence of major players in the field of oilfield services and technologies. Besides, there is good maturity level of digital oilfield programs in addition to good cooperation with technology partners. Data platforms, cloud services, and analytics solutions by SLB, Halliburton, Baker Hughes, Microsoft, Amazon Web Services, Google Cloud, Oracle, and IBM are offered to operators in the region.
⮞In 2026, North America's data infrastructure build-out continued when SLB expanded its Shreveport, Louisiana, facility, nearly doubling its footprint to increase manufacturing capacity for data center equipment, strengthening the region's supply chain for hyperscalers and AI-driven oilfield data operations.
In the U.S., demand is driven by operators from the Permian Basin, Eagle Ford, Bakken, Appalachia, and Gulf of America who make extensive investments in the cloud, AI, and data management solutions to lower costs and increase well efficiency. Independent operators are also adopting SaaS data solutions. In Canada, demand comes from operators in the oil sands of Alberta and natural gas in British Columbia, where data platforms are used for reservoir management, emissions management, and asset integrity. Mexico is updating its upstream data solutions at Pemex and other operators. Continued technology adoption and digital transformation initiatives are expected to maintain North America as the leading regional market.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Oil and Gas Data Management Market Insights
The Asia Pacific region is currently experiencing the most rapid growth in terms of its regional market share, which accounts for roughly 22.48% of the global market in 2025 with an approximate CAGR of about 13.24% between 2026 and 2035. Oil companies within the region are also teaming up with the world's major cloud computing companies to develop local data centers, artificial intelligence capacity, and sub-surface data repositories. This growth in the region can be attributed to increasing energy consumption, exploration and production activities, and digital transformation initiatives by national oil companies. China's CNPC, Sinopec, and CNOOC are focusing on developing data platforms, cloud computing, and AI capacity to increase efficiencies in exploration and production.
India is among the key growth drivers, with ONGC, Oil India, and Reliance Industries increasing exploration initiatives and adopting digital oil field services, along with the national data repository ensuring easier access to subsurface data. Regional governments have been promoting the exchange of data and adoption of digital capabilities to enable investments in the upstream sector. Operators of liquefied natural gas in Australia have adopted sophisticated data platforms to optimize production and maintenance and manage their emissions. Japan and South Korea are contributing through refining and liquefied natural gas imports and petrochemical activities, which are dependent on data systems.
⮞In 2026, India's digital upstream transformation advanced when Oil and Natural Gas Corporation (ONGC) selected SLB as its digital transformation partner, deploying the Lumi data and AI platform, powered by Cognite Data Fusion, across every ONGC asset to unify 100% of the company's well data for scalable analytics.
Europe Oil and Gas Data Management Market Insights
The European region represents a considerable segment of the Oil and Gas Data Management Market, fueled by advanced offshore activities in the North Sea region along with a leading presence of digitalization amongst operators in Norway and Britain. Norwegian Continental Shelf operators are also early innovators in the area of remote operations, digital twins, and maintenance via data, which is being replicated elsewhere. The Norwegian market represents the biggest country segment within Europe, with Equinor and Aker BP leading the way through adoption of cloud platforms, OSDU Data Platform, and Industrial data solutions offered by Cognite and Kongsberg Digital respectively.
Data collection from offshore production activities, decommissioning, and carbon capture and storage projects in the United Kingdom, the Netherlands, Italy, and Denmark is crucial. The European players have been spearheading the adoption of data platforms in decommissioning and carbon storage projects. TotalEnergies, Shell, BP, and Eni are developing data platforms for their operations around the globe. Data requirements from North Sea Transition Authority and European emission regulations have increased the need for reliable information. It is expected that robust adoption of technologies, energy transition projects, and regulations will continue to make Europe an important regional market for oil and gas data management during the forecast period.
⮞In 2026, Norway's digital oilfield push advanced when Cognite and Equinor entered a robotics collaboration at Equinor's Mongstad facility near Bergen, using Cognite Data Fusion as the data foundation for a digital twin that integrates operational, engineering, and robotics data to power autonomous inspection and predictive maintenance.
MEA & Latin America Oil and Gas Data Management Market Insights
The Middle East & Africa is a fast-emerging market that is spearheaded by Saudi Arabia, UAE, Qatar, and Kuwait. There are also collaborations from the regional players in partnership with international technology firms to develop artificial intelligence and integrate subsurface, drilling, and production data in one platform. National oil companies such as Saudi Aramco, ADNOC, QatarEnergy, and Kuwait Oil Company are making big investments in digital transformation, AI, and data platforms in order to maximize their reserves and boost production capacities. Data sovereignty laws push for the establishment of data centers and cloud regions within the country. In Africa, Nigeria, Angola, and Mozambique are updating their data systems in order to conduct offshore and LNG projects.
⮞In 2026, Kuwait's subsurface data capabilities advanced when Kuwait Oil Company awarded SLB a five-year contract to deliver seismic data processing and reprocessing services, incorporating AI workflows to accelerate interpretation insights across the country's fields.
Latin America is developing consistently, with the help of Brazil, Mexico, Argentina, and Guyana. Data rooms and licensing rounds in the national oil companies of the region are based on comprehensive subsurface data. Petrobras, which leads the way in the development of deep-water pre-salt fields, invests heavily in high performance computing, data management, and AI for seismic interpretation and reservoir modeling. The expansion of drilling and production in Vaca Muerta shale play in Argentina will be adding to the requirement for drilling and production data systems. The offshore drilling and production in Guyana, spearheaded by ExxonMobil, needs an advanced data management right away.
⮞In September 2026, Brazil's offshore data infrastructure advanced when Brazil's Advanced Research and Systems Center (CESAR), in partnership with Petrobras, unveiled an offshore digital twin system at the Rio Oil, Gas and Energy Show that monitors 40 subsea flexible pipelines connecting wells to FPSOs, fusing real-time operational data with physical models to track corrosion and fatigue and extend equipment service life well beyond original design estimates.
Market Dynamics:
Growth Drivers: Rapid Growth in Oil and Gas Data Volumes and Rising Adoption of AI and Analytics
The rapid increase in the quantity of oil and gas data is the main reason driving the Oil and Gas Data Management Market due to high-resolution seismic surveys, drilling sensors, production monitoring systems, and Internet of Things technology that produce tremendous amounts of data. The ability to keep and reuse the old data also brings value in decision-making on exploration and development. One seismic survey may create several petabytes of data, while wells and facilities constantly produce operation data. It is necessary to store, structure, and govern the data to make it usable. More sensors, digital oilfields, and increased data retention periods will drive the need for data management solutions even further. The increase in the use of AI and analytics is helping drive market growth as there is the application of machine learning technology in the interpretation of seismic activity, drill optimization, predictive maintenance, and production forecasting.
⮞In 2026, rising AI adoption in upstream data workflows advanced when Aker BP deepened its strategic partnership with Cognite through the expanded deployment of Cognite Atlas AI™, aiming to scale AI-driven decision-making across the company's exploration and production operations.
Restraints: Data Silos and Legacy System Complexity and Cybersecurity Concerns
Data silos and complexities associated with legacy systems continue to form one of the major constraints in the Oil & Gas Data Management Market. Companies have hundreds of applications and databases running for decades with varying formats. Inadequate expertise in data engineers and domain specialists poses as a constraint during such integration programs. Integration becomes cumbersome due to seismic tapes, well files, and propriety formats of the software. The process becomes complicated when mergers and acquisitions are involved due to varied data environments. Data quality issues and naming conventions are other issues faced. Cybersecurity issues limit growth for the industry because the oil and gas industry has been known to fall victim to cyberattacks against their operational technology, data, and infrastructure.
Opportunities: OSDU and Open Data Platform Adoption and Emissions and Energy Transition Data Management
The use of the OSDU Data Platform and the open data standards will create several opportunities for the Oil and Gas Data Management Market in view of efforts by oil and gas organizations to remove data silos and eliminate the reliance on proprietary systems. Open data systems make it easier for operators to utilize innovative applications and AI technologies from smaller software vendors. The OSDU Data Platform creates a unified and cloud-based data platform for subsurface and well data, which makes it possible for applications from various vendors to access the same data. This standard is backed by major operators, service companies, and cloud vendors, hence the need for migration, integration, and application development services.
⮞In December 2025, OSDU standardization opportunities advanced when members of The Open Group OSDU Forum, including Chevron, used the Houston Summit to progress plans to launch Version 1 of the OSDU Data Platform Standard in 2026, with a specific focus on making subsurface data AI-ready and simplifying consumption for operators and application providers across the industry.
Recent Developments:
-
2026: Emerson launched the AspenTech AVA industrial AI platform, built on the AspenTech Inmation Data Platform to organize operational technology data across cloud, edge, and on-premise systems, with four operational optimization and decision-support advisors at launch.
-
2026: AVEVA announced new capabilities at AVEVA World 2026, including Snowflake and ServiceNow integrations for its CONNECT industrial intelligence platform, Flows real-time data pipelines with over 800 connectors, and PI Server performance and scalability enhancements.
Oil and Gas Data Management Market Key Players are:
-
SLB
-
Halliburton Company
-
Baker Hughes Company
-
IBM Corporation
-
Oracle Corporation
-
SAP SE
-
Microsoft Corporation
-
Amazon Web Services, Inc.
-
Honeywell International Inc.
-
Emerson Electric Co. (AspenTech)
-
AVEVA Group Limited
-
Cognite AS
-
Kongsberg Digital AS
-
Hitachi Vantara LLC
-
Accenture plc
-
Tata Consultancy Services Limited
-
Wipro Limited
-
TGS ASA
-
Viridien (formerly CGG)
-
Katalyst Data Management Inc.
Oil and Gas Data Management Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 30.42 Billion |
| Market Size by 2035 | USD 93.31 Billion |
| CAGR | 11.86% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component: Dominant – Software (66.84% share in 2025); Fastest-Growing – Services (CAGR 13.12%) • By Deployment: Dominant – On-Premises (56.42% share in 2025); Fastest-Growing – Cloud (CAGR 14.86%) • By Application: Dominant – Exploration & Drilling (31.24% share in 2025); Fastest-Growing – Reservoir Management (CAGR 13.48%) • By Operation: Dominant – Upstream (58.26% share in 2025); Fastest-Growing – Midstream (CAGR 12.64%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | SLB, Halliburton Company, Baker Hughes Company, IBM Corporation, Oracle Corporation, SAP SE, Microsoft Corporation, Amazon Web Services, Inc., Honeywell International Inc., Emerson Electric Co. (AspenTech), AVEVA Group Limited, Cognite AS, Kongsberg Digital AS, Hitachi Vantara LLC, Accenture plc, Tata Consultancy Services Limited, Wipro Limited, TGS ASA, Viridien (formerly CGG), Katalyst Data Management Inc. |

Frequently Asked Questions
Key players include SLB, Halliburton Company, Baker Hughes Company, IBM Corporation, Oracle Corporation, SAP SE, and Microsoft Corporation, among other global technology and oilfield service companies.
OSDU and open data platform adoption, along with emissions and energy transition data management, represent the primary opportunities.
Growth is primarily driven by rapid growth in oil and gas data volumes combined with rising adoption of AI and analytics.
By Component, Software dominated the market with approximately 66.84% share in 2025, reflecting broad use of data platforms, analytics, and visualization tools.
North America dominated the market with approximately 34.62% share in 2025, driven by intensive shale drilling and strong digital adoption among operators.
