
Oncology Nutrition Market Report Scope & Overview:
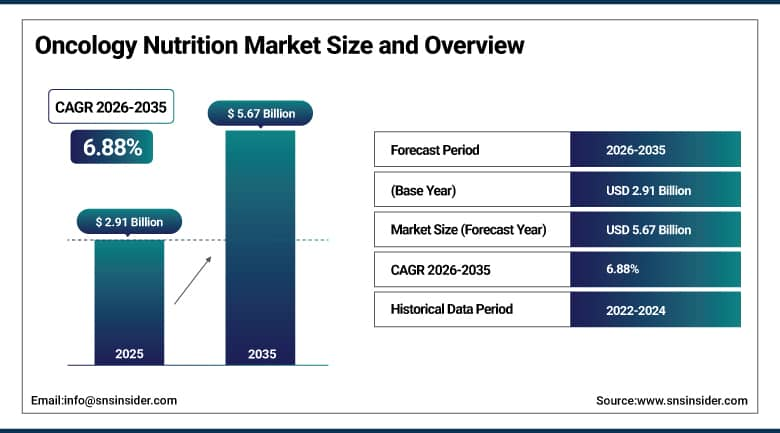
The Oncology Nutrition Market was valued at USD 2.91 Billion in 2025 and is expected to reach USD 5.67 Billion by 2035, growing at a CAGR of 6.88% from 2026-2035.
The Oncology Nutrition Market covers medical nutrition products designed for people with cancer, including oral supplements, tube feeds and intravenous formulas. Cancer and its treatment often cause weight loss, muscle wasting and poor appetite, which raise the risk of infection, treatment delays and shorter survival. Hospitals and cancer centers increasingly screen patients for malnutrition and prescribe specialized products. Rising cancer cases and survivor numbers, together with greater awareness among oncologists, support steady growth. Limited reimbursement and low screening rates remain barriers. Products with higher protein, immune-supporting nutrients and easy tolerability are gaining attention. Manufacturers also invest in education so that clinicians can recognize risk early.
⮞In July 2026, the World Health Organization reported about 20.6 million new cancer cases and nearly 10 million deaths each year, with new cases projected to reach nearly 35 million a year by 2050. The scale of disease underpins long-term demand for supportive nutrition.
To Get More Information On Oncology Nutrition Market - Request Free Sample Report
Oncology Nutrition Market Trends:
-
Routine malnutrition screening at cancer diagnosis in leading cancer centers
-
Rising use of high-protein, immunonutrition and disease-specific formulas
-
Prehabilitation nutrition before surgery and chemotherapy
-
Shift of enteral and oral supplement care from hospitals to the home
-
Growth of online and retail channels for medical nutrition
U.S. Oncology Nutrition Market Outlook:
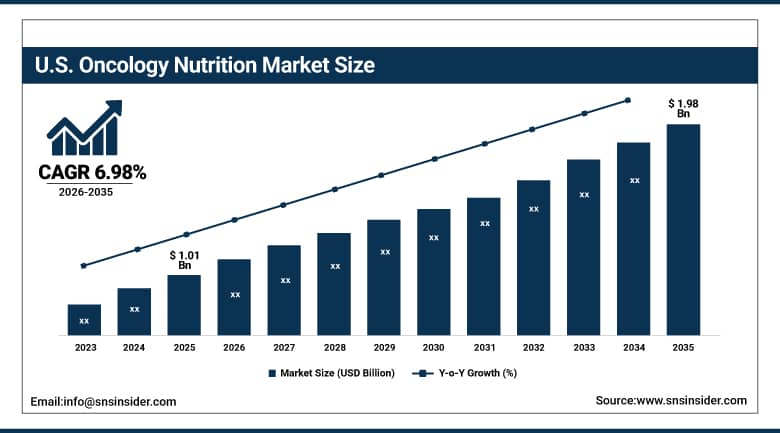
The U.S. Oncology Nutrition Market was valued at USD 1.01 Billion in 2025 and is expected to reach USD 1.98 Billion by 2035, growing at a CAGR of 6.98% from 2026-2035.
The U.S. Oncology Nutrition Market is the biggest national market due to a substantial number of patients, cancer centers, and high awareness among health professionals. Dietitians from top hospitals screen the risk of malnutrition and recommend oral and tube feed supplements. The increase in the number of cancer survivors boosts the need for nutritional products. Insurance coverage of supplements is not consistent across all payers; hence, most of the patients buy the products on their own, either in retail stores or online. The trend of home-based treatments increases the market due to the shift from inpatient to outpatient care facilities. There is stiff competition between established brands and new clean label products.
⮞In January 2026, the American Cancer Society projected 2,114,850 new cancer cases and 626,140 cancer deaths in the United States in 2026, with a five-year relative survival rate of 70%. Higher survival means more patients live with the nutritional effects of cancer.
Oncology Nutrition Market Segment Analysis:
-
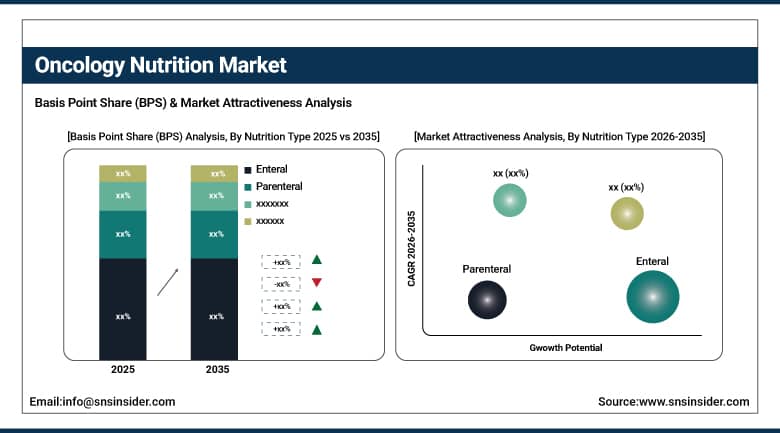
By Nutrition Type, the Enteral segment dominated the Oncology Nutrition Market with approximately 73.91% share in 2025, while the Parenteral segment is the fastest growing with a CAGR of approximately 7.43%.
-
By Cancer Type, the Head & Neck segment dominated the Oncology Nutrition Market with approximately 28.11% share in 2025, while the Lung segment is the fastest growing with a CAGR of approximately 8.05%.
-
By Distribution Channel, the Hospital Pharmacies segment dominated the Oncology Nutrition Market with approximately 55.83% share in 2025, while the Online Pharmacies segment is the fastest growing with a CAGR of approximately 10.88%.
-
By End User, the Hospitals segment dominated the Oncology Nutrition Market with approximately 59.22% share in 2025, while the Home Care segment is the fastest growing with a CAGR of approximately 9.26%.
By Nutrition Type, Enteral Dominates the Oncology Nutrition Market and Parenteral Grows Fastest
Enteral nutrition leads because it keeps the gut working and is safer, cheaper and easier to give than intravenous feeding. It includes oral nutritional supplements for patients who can still eat and tube feeding for those who cannot swallow safely. Guidelines favor the enteral route whenever the digestive tract functions. Products come in liquid, powder and semisolid forms with high protein and energy density. Dietitians can adjust volume and composition to treatment plans. Manufacturers also offer flavors and textures to help patients who have taste changes or mouth sores.
Parenteral nutrition is the fastest growing type because patients with bowel obstruction, severe mucositis or after major abdominal surgery cannot absorb enough through the gut. Advances in multi-chamber bags, safer lipid emulsions and home infusion services have improved safety and convenience. Hospitals use parenteral feeding for the sickest patients, and survivors with long-term gut problems may continue at home. Infection risk and cost limit use to those who truly need it, but rising complexity of cancer surgery supports growth. Specialist home infusion providers have made longer use more practical.
⮞In May 2025, Otsuka Pharmaceutical Factory announced the launch of HINEX Jelly Aqua, a semisolid enteral product with 303 mL of water in each 300 kcal pouch. The launch shows product innovation aimed at patients who struggle with fluids and swallowing.
By Cancer Type, Head & Neck Dominates the Oncology Nutrition Market and Lung Grows Fastest
Head and neck cancers lead because tumors and treatment directly affect chewing, swallowing and taste. Radiation to the throat and mouth often causes pain, dryness and difficulty eating, and many patients need tube feeding during therapy. Nutrition teams are therefore involved from diagnosis. Malnutrition rates in this group are among the highest of all cancers, and weight loss can interrupt radiation. Hospitals with head and neck programs often use specialized supplements and feeding tubes as standard parts of care.
Lung cancer is the fastest growing cancer type as large patient numbers, longer survival with targeted drugs and immunotherapy, and high rates of weight loss combine to raise demand. Patients with lung cancer often lose muscle mass, which can limit treatment options. Clinicians are paying more attention to protein intake and exercise alongside drug therapy. Gastrointestinal, breast and colorectal cancers also use large volumes of nutrition, especially around surgery and chemotherapy, and they remain important contributors to market revenue. Early dietitian referral is becoming more common in lung cancer clinics.
⮞In 2025, researchers at the Hawassa University Comprehensive Specialized Hospital Cancer Treatment Center reported in PeerJ that 58% of 393 adult cancer patients were undernourished. The finding shows how common malnutrition remains in cancer care.
By Distribution Channel, Hospital Pharmacies Dominates the Oncology Nutrition Market and Online Pharmacies Grows Fastest
Hospital pharmacies dominate this market since a lot of oncology nutritional formulas are prescribed or recommended while inpatient or during treatment sessions. Dietitians and oncologists choose the products and order them according to the agreements with the hospitals that buy from manufacturers. Tube feeding and parenteral formulas need to be prescribed clinically; therefore, they are provided mostly via hospitals and specialized homecare. Hospital formularies influence on which particular brands will be prescribed post-hospitalization. Strong relationship between suppliers and clinical practitioners support dominance of this distribution channel. Group purchasing contracts increase influence of large suppliers.
The online pharmacies have the highest growth rates due to patients' and caregivers' desire to get supplements delivered discretely at home conveniently. Online channels provide subscriptions and product comparison, as well as can deliver to areas where there are not enough specialized retail stores. Manufacturers create their websites to sell directly to consumers and cooperate with e-commerce companies. High importance of quality and safety requires proper labeling and link to professional consultation. Retail pharmacies still are dominant channel for daily supplements; however, its share remains constant. Teleconsultations with dietitians also result in online purchases.
⮞In July 2026, Kate Farms said retail distribution of its high-protein shake had grown more than sevenfold since a Walmart launch in the fourth quarter of 2025, with more than 6,800 Walmart and CVS stores expected by August 2026. The expansion shows demand for medical-grade nutrition in mainstream retail.
By End User, Hospitals Dominates the Oncology Nutrition Market and Home Care Grows Fastest
Hospitals lead because they diagnose cancer, deliver surgery and chemotherapy, and employ the dietitians who assess nutritional risk. Inpatient stays involve the highest use of tube feeding and parenteral nutrition. Cancer centers have protocols for screening at admission, and many provide counseling and supplements as part of care. Procurement is centralized, which gives large manufacturers an advantage. Hospital-based programs also create the first contact through which patients learn about products that they later buy for home use. Large academic centers also run clinical trials that test new formulas.
Home care is the fastest growing end user as cancer treatment moves to outpatient settings and health systems try to shorten hospital stays. Patients receive oral supplements, tube feeds and infusion support at home, supported by nurses and telehealth. Caregivers need training, and suppliers are adding education, hotlines and delivery services. Reimbursement for home nutrition varies widely, which shapes uptake. Growth in cancer survivorship also adds a group who need nutrition guidance long after hospital care ends. Telehealth follow-up helps dietitians adjust plans without clinic visits.
⮞In autumn 2025, the European Society for Clinical Nutrition and Metabolism recommended nutritional risk assessment for all patients before surgery and noted that prehabilitation may improve recovery after gastrointestinal cancer surgery. The guidance supports earlier nutrition care in hospitals.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
87.12 |
|
Europe |
Germany |
24.37 |
|
Asia Pacific |
China |
38.54 |
|
Latin America |
Brazil |
52.68 |
|
Middle East & Africa |
Saudi Arabia |
31.46 |
North America Oncology Nutrition Market Insights
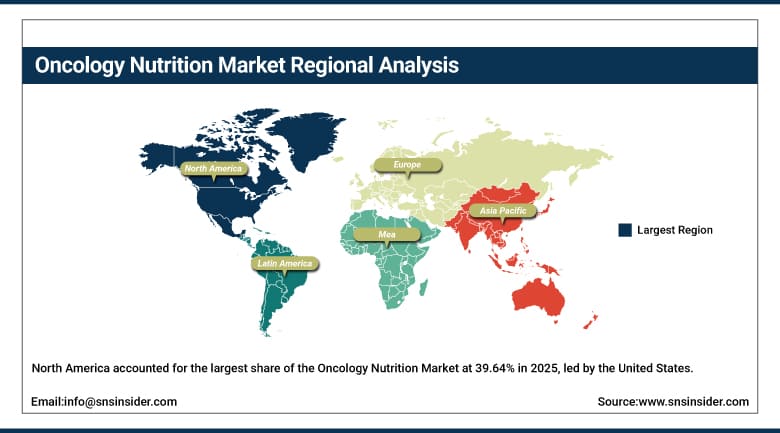
North America accounted for the largest share of the Oncology Nutrition Market at 39.64% in 2025, led by the United States. The region has many cancer centers with dietitian teams, strong awareness among oncologists and well-established supply from global manufacturers. Canada adds demand through provincial cancer programs. Retail and online channels are well developed, so patients can buy supplements with or without a prescription. Clinician education from manufacturers is well established.
Clinical guidelines and survivorship growth support steady demand. Professional societies in the region recommend screening for malnutrition and early nutrition support, and academic centers publish studies that link nutrition to better outcomes. Reimbursement is mixed, with some plans covering tube feeding but few covering oral supplements. Manufacturers invest in education programs for clinicians and in plant-based and clean-label products to appeal to patients who want food-like options. Cancer centers also run survivorship clinics that include dietitians.
⮞In April 2026, the Canadian Medical Association Journal published projections of 254,100 new cancer cases and 87,900 cancer deaths in Canada in 2026. The numbers show a large and growing patient group for supportive care.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Oncology Nutrition Market Insights
Europe Oncology Nutrition Market in 2025 is led by Germany, the United Kingdom, France, Italy and Spain. The region is home to several of the largest clinical nutrition manufacturers, and national health systems often fund tube feeding and supplements for malnourished patients. Societies such as ESPEN publish guidelines that shape practice across borders, and hospitals in Northern and Western Europe have mature nutrition support teams. Cross-border clinical networks share protocols and research.
Policy and cost control influence the market. Health technology bodies review the evidence for oral supplements, and reimbursement rules differ by country, from broad coverage in some systems to strict criteria in others. Ageing populations raise cancer incidence, and prehabilitation programs before surgery are spreading. Manufacturers hold large scientific meetings and educational events to engage clinicians, and regional launches of food-based enteral products show a push for more natural formulations. Public tenders for hospital supplies favor suppliers with broad ranges.
⮞In February 2026, the European Commission's Joint Research Centre estimated about 2.7 million new cancer cases in the EU-27 in 2024. The burden drives sustained need for oncology nutrition services.
Asia Pacific Oncology Nutrition Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 8.87% during 2026-2035. China, Japan, India, South Korea and Australia lead. Rising cancer incidence with ageing populations, expanding hospital capacity and greater awareness of nutrition in treatment all support demand. Japan has a mature clinical nutrition industry with local makers, while China and India are building access through hospital networks and online sales. Medical tourism hubs also add demand in some countries.
Several forces shape growth. Governments are widening insurance coverage for cancer care, and professional societies in the region are issuing nutrition guidance adapted to local diets. Local manufacturers launch semisolid and easy-to-swallow products suited to older patients, and global firms form partnerships with hospitals and distributors. Affordability and uneven access to dietitians remain challenges, particularly outside major cities, yet the sheer size of the patient population gives the region long-term potential. Online marketplaces are especially influential in China.
⮞In February 2025, India's Indian Council of Medical Research reported, through a journal analysis of national registry data, that India was projected to have 1,569,793 cancer cases by 2025. The number illustrates the scale of need in the region.
MEA & Latin America Oncology Nutrition Market Insights
Latin America and the Middle East and Africa together hold about 10.09% of the Oncology Nutrition Market. In Latin America, Brazil, Mexico, Argentina and Colombia lead, with private hospitals and public cancer institutes adopting screening and supplements. Studies in the region show that about half of hospitalized cancer patients are malnourished or at risk, which supports the case for wider use. Public coverage for supplements is limited, and imports raise prices. Local distributors play a major role in reaching hospitals.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Turkey and South Africa are the main markets. Gulf countries are investing in specialized cancer hospitals and are among the first in the region to build clinical nutrition teams. In sub-Saharan Africa, late diagnosis, limited dietitian numbers and cost keep use low, though local studies document very high malnutrition rates among patients. International partnerships and training programs may gradually lift access. Training of dietitians is a growing priority for health ministries.
⮞In February 2025, the Pan American Health Organization reported more than 4 million new cancer cases and 1.4 million deaths each year in the Americas. The burden shows the long-term need for supportive care across Latin America.
Market Dynamics:
Growth Drivers: Rising Cancer Survivorship and Malnutrition Awareness Drive Growth in the Oncology Nutrition Market
Rising cancer survivorship and greater awareness of malnutrition are the main drivers. More people are diagnosed, and better treatments mean they live longer, so the number needing nutritional support over the long term is growing. Clinicians now understand that weight and muscle loss reduce tolerance to chemotherapy, raise complications and shorten survival. Screening tools are spreading in hospitals, and dietitians are being embedded in cancer teams. Each of these steps raises the share of patients who receive suitable products. Cancer charities and patient groups also promote nutrition education.
Product innovation and guideline support add momentum. Manufacturers are launching high-protein, easy-to-swallow and food-based formulas, as well as products with nutrients studied for immune support. Professional societies recommend early nutrition intervention and prehabilitation before surgery. Studies linking nutrition to fewer complications strengthen the case for payers. Home care models and online sales widen access, and partnerships with universities and cancer centers support further research and clinician education. Hospitals value products that help patients complete planned treatment cycles. Supportive care programs also help patients stay on treatment schedules.
⮞In May 2025, the U.S. National Cancer Institute reported 18.6 million cancer survivors in the United States, projected to reach 22.4 million by 2035. The growing survivor group extends demand for nutrition support beyond active treatment.
Restraints: Low Screening Rates and Limited Reimbursement Restrain Growth in the Oncology Nutrition Market
Low screening rates and limited reimbursement restrain growth. In many hospitals, malnutrition goes unrecognized because screening is not routine or dietitians are scarce. Patients and doctors often focus on drug therapy and treat nutrition as secondary. Without early identification, patients start supplements late or not at all. This under-treatment limits the market even where products are available and effective. Short appointment times leave little room for nutrition discussion, and referral pathways to dietitians are often unclear. Short appointment times leave little room for nutrition discussion.
Cost and coverage add further barriers. Many insurers and health systems cover tube feeding but not oral supplements, so patients pay out of pocket. Evidence on the impact of nutrition on survival is still being built, which makes some payers cautious. Price competition from general nutrition drinks, and the difficulty of persuading patients with poor appetite to use products regularly, also limit volumes. In low-income countries, import costs and weak supply chains make access harder. Smaller clinics may also lack space and staff to manage feeding programs. Procurement teams at public hospitals often negotiate hard on price.
⮞In June 2025, researchers publishing in SOLCA's Oncología (Ecuador) journal reported that about half of 390 cancer patients in five hospitals were malnourished or at risk. The result shows how common unaddressed nutrition problems remain.
Opportunities: Personalized Nutrition and Home Care Expansion Create Opportunities in the Oncology Nutrition Market
Personalized nutrition represents an important opportunity. Research on tumor metabolism, muscle atrophy, and the gut microbiome is expected to result in formulas specifically tailored according to cancer type, therapy, and individual characteristics. Products containing certain proteins, fatty acids, or other components, as well as digital applications for tracking the intake of calories and body weight can be used to adjust the personalized plans. The results of carefully designed clinical trials will likely convince insurance companies to pay and make the formula accessible for more patients. The early clinical trials are encouraging companies to develop their solutions.
Further opportunity comes from expansion in home care and developing countries. With the trend of outpatient therapy, the suppliers can design service that consists of delivery, nutrition advice, and remote consultation with a dietician. In aging populations of Asia, the growing incidence of cancer drives the development of supportive care programs. The plant- and food-based enteral nutrition products are appealing for those patients who prefer a natural product. Collaboration with academic organizations is helpful in developing new credible products in underpenetrated markets. Digital applications for monitoring food intake and reporting adverse effects may increase compliance.
⮞In May 2025, the National Cancer Center Japan reported 382,504 cancer deaths in Japan in 2023. The size of the burden in an ageing society points to rising need for supportive products.
Recent Developments:
-
In September 2025, Danone's Nutricia called for action on cancer-related malnutrition at the ESPEN congress in Prague and presented seven scientific abstracts. The company also highlighted its Fortimel and Nutrison ranges for patients with cancer.
-
In September 2025, Fresenius Kabi held a satellite symposium titled Fit for Therapy: Transforming Oncology Care with Medical Nutrition at ESPEN 2025. The event brought clinicians together to discuss nutrition as part of cancer treatment plans.
-
In October 2025, Nestlé Health Science announced a partnership with the UC Davis Innovation Institute for Food and Health that names oncology as a focus. The work aims to develop science-based nutrition solutions for patients.
Oncology Nutrition Market Key Players are:
-
Abbott Laboratories
-
Nestlé Health Science
-
Danone S.A. (Nutricia)
-
Fresenius Kabi AG
-
Hormel Foods Corporation
-
Baxter International Inc.
-
B. Braun SE
-
Kate Farms, Inc.
-
Meiji Holdings Co., Ltd.
Oncology Nutrition Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.91 Billion |
| Market Size by 2035 | USD 5.67 Billion |
| CAGR | CAGR of 6.88% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Nutrition Type (Enteral and Parenteral) • By Cancer Type (Head & Neck, Gastrointestinal, Lung, Breast, and Others) • By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, and Online Pharmacies) • By End User (Hospitals, Home Care, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Abbott Laboratories, Nestlé Health Science, Danone S.A. (Nutricia), Fresenius Kabi AG, Hormel Foods Corporation, Baxter International Inc., B. Braun SE, Kate Farms, Inc., Meiji Holdings Co., Ltd. |

Frequently Asked Questions
Key players include Danone (Nutricia), Fresenius Kabi, Abbott Nutrition, Nestlé Health Science, Otsuka Pharmaceutical Factory and Kate Farms.
Key opportunities include personalized and disease-specific formulas, home care services, online channels and expansion in Asia and other emerging regions.
Rising cancer survivorship and growing recognition of malnutrition as a cause of poor outcomes are the main growth factors, supported by clinical guidelines.
By Nutrition Type, the Enteral segment dominated the market in 2025 with an estimated 73.91% share, supported by its safety, lower cost and ease of use.
North America dominated the market with a share of 39.64% in 2025, driven by advanced cancer centers, strong clinician awareness and established supply.
