
Pipeline & Process Services Market Report Scope & Overview:
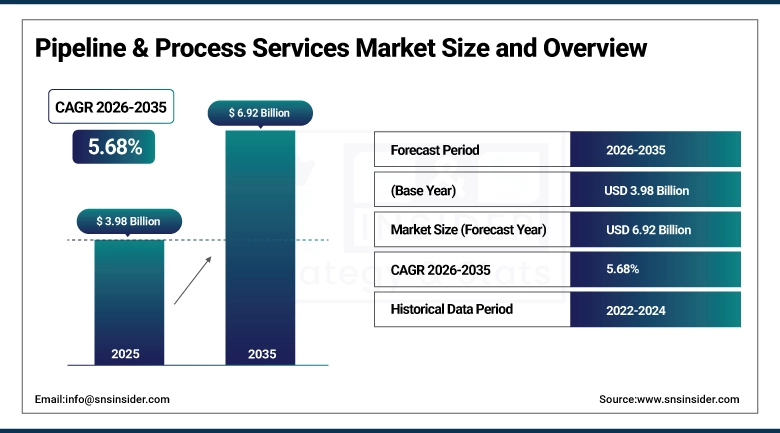
The Pipeline & Process Services Market was valued at USD 3.98 Billion in 2025 and is expected to reach USD 6.92 Billion by 2035, growing at a CAGR of 5.68% from 2026-2035.
The Pipeline & Process Services Market is advancing at a steady pace as operators sanction new pipelines, LNG trains, and processing plants while extending the working life of assets built decades ago. Demand spans the full asset lifecycle, from flooding, cleaning, gauging, and hydrotesting before first product to pigging, inline inspection, isolation, and nitrogen services during operation, and flushing ahead of decommissioning. Providers are bundling these scopes into multi-year agreements, investing in digital pig tracking and leak detection, and acquiring regional specialists to widen their reach. Offshore tie-backs, gas-fired power, and emerging hydrogen and carbon dioxide networks add fresh work, while owners in mature regions allocate larger budgets to integrity programs and shutdown support.
⮞In June 2025, funds managed by Apollo made a strategic investment in T.D. Williamson (TDW), with SCF Partners retaining majority ownership. The company said the capital would support innovation and global expansion across pipeline isolation, integrated pigging, in-line integrity assessment, and repair, serving both infrastructure and utility end markets.
To Get more information On Pipeline & Process Services Market - Request Free Sample Report
Pipeline & Process Services Market Trends
-
Rising adoption of digital pig tracking, leak detection, and automated pig-speed control that improve inspection quality.
-
Growing demand for pipeline isolation, hot tapping, and repair services that keep lines in operation during maintenance.
-
Expanding bundling of pre-commissioning, commissioning, and process services into multi-year lifecycle agreements.
-
Increasing use of ultra-high-resolution inspection and non-intrusive assessment for ageing and unpiggable pipelines.
-
Rising readiness work for hydrogen and carbon dioxide pipelines, including inspection and isolation trials.
U.S. Pipeline & Process Services Market Outlook
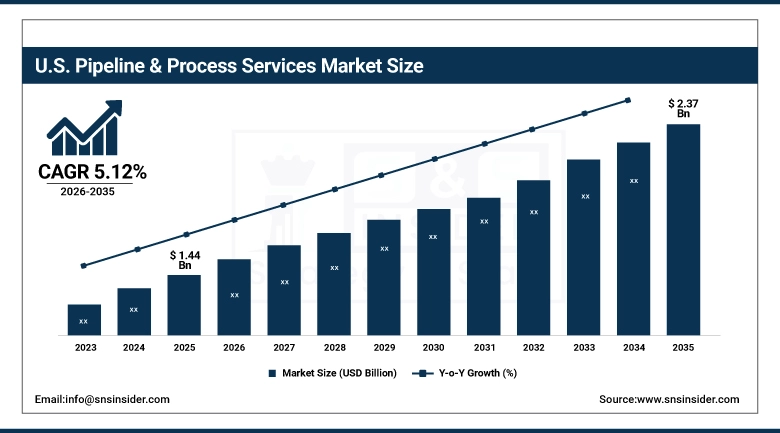
The U.S. Pipeline & Process Services Market was valued at USD 1.44 Billion in 2025 and is expected to reach USD 2.37 Billion by 2035, growing at a CAGR of 5.12% from 2026-2035.
The U.S. Pipeline & Process Services Market is expanding as operators maintain one of the largest pipeline networks in the world while adding Permian takeaway capacity and LNG feedgas corridors along the Gulf Coast. STATS Group estimates that about half of regulated U.S. pipelines were built before 1970, which keeps inline inspection, cleaning, isolation, and repair programs at the center of integrity budgets. Houston and Tulsa host the headquarters and field bases of leading providers, and manufacturers are localizing hot tap and line stop fittings to shorten lead times. Midstream consolidation, including Energy Transfer's agreement to acquire Vaquero Midstream and its 300-mile West Texas network, signals continued investment in assets that require ongoing services.
⮞In May 2026, STATS Group opened an 80,000-square-foot manufacturing facility in Rosenberg, Texas, its first dedicated U.S. manufacturing operation and the largest capital investment in the company's history. The site produces hot tap and line stop fittings and components for the proprietary systems behind its pipeline isolation and intervention services across North America.
Pipeline & Process Services Market Segment Analysis
-
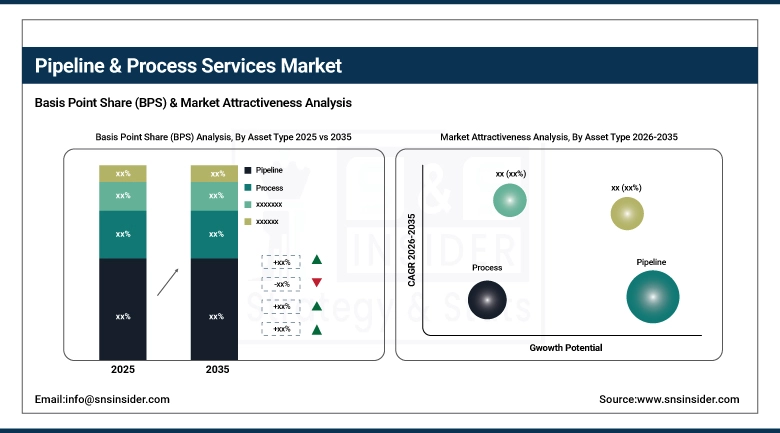
By Asset Type, the Pipeline segment dominated the Pipeline & Process Services Market with approximately 69.42% share in 2025, while the Process segment is the fastest growing with a CAGR of approximately 6.47%.
-
By Operation, the Maintenance segment dominated the Pipeline & Process Services Market with approximately 36.42% share in 2025, while the Decommissioning segment is the fastest growing with a CAGR of approximately 7.34%.
-
By Service Type, the Pipeline Inspection segment dominated the Pipeline & Process Services Market with approximately 22.86% share in 2025, while the Leak Detection segment is the fastest growing with a CAGR of approximately 8.12%.
-
By End-User, the Oil and Gas segment dominated the Pipeline & Process Services Market with approximately 61.27% share in 2025, while the Water and Wastewater segment is the fastest growing with a CAGR of approximately 7.43%.
-
By Location, the Onshore segment dominated the Pipeline & Process Services Market with approximately 68.93% share in 2025, while the Offshore segment is the fastest growing with a CAGR of approximately 6.74%.
By Asset Type, Pipeline Dominates the Pipeline & Process Services Market and Process Grows Fastest
Pipeline assets hold the leading position because transmission and distribution networks are long, geographically dispersed, and subject to recurring cleaning, inspection, and repair cycles. Every new section requires flooding, cleaning, gauging, and hydrotesting before product flows, and every operating line needs periodic pigging and integrity assessment. Operators of gas transmission systems, crude gathering lines, and subsea flowlines purchase these services as a continuing budget item rather than a one-time project. Specialist providers such as TDW and ROSEN have built global field networks around this base, and owners value suppliers able to mobilize quickly to remote locations.
Process services are advancing more rapidly as new LNG trains, floating production units, refineries, and gas processing plants reach start-up and require extensive cleaning and conditioning. Chemical cleaning of acid gas removal units, nitrogen purging and helium leak testing, oil flushing, and bolt tensioning are scheduled around tight commissioning windows, which favors providers with deep equipment fleets. Topside operators in the North Sea are signing multi-year agreements for these scopes, and Norwegian specialists are adding facilities to serve offshore customers. Turnarounds at refineries and petrochemical complexes supply a second stream of work, and integrated commissioning contracts are pulling process scopes into larger pipeline packages.
⮞In September 2026, Pipetech opened a 950-square-meter facility in Sandnes, Norway, with six offices, a workshop, and yard space to support on-site pipe and process cleaning. The company invested more than NOK 6 million, including a high-flow pump rated at up to 1,020 bar for Aqua Milling and high-pressure water jetting to remove wax and hard scale.
By Operation, Maintenance Dominates the Pipeline & Process Services Market and Decommissioning Grows Fastest
Maintenance accounts for the largest pool of work since producing assets must be kept clean, protected, and repaired throughout decades of service. Operators schedule routine pigging, cleaning, corrosion management, leak repair, and isolation campaigns, and many award these scopes on multi-year terms that give providers stable revenue. The ageing of transmission systems adds repair and replacement volume, while the need to keep lines flowing has lifted demand for hot tapping and pressure isolation. Providers that combine cleaning, repair, and data capabilities can address an owner's entire upkeep cycle through a single contract, which strengthens customer retention and encourages consolidation among regional specialists.
Decommissioning is rising fastest as offshore fields in mature basins reach end of life and onshore lines are retired or repurposed. Each abandoned line must be flushed, cleaned, and verified free of hydrocarbons before it is cut, capped, or removed, which creates demand for high-pressure pumping, filtration, and vessel-based equipment spreads. Operators increasingly expect documented evidence of cleanliness before abandonment, and engineering-led scopes are replacing simple flushing orders. Programs in the Gulf of America, the North Sea, and Southeast Asia should supply multi-year pipelines of work, and companies able to pair engineering with offshore execution are winning repeat awards. Conversion of gas lines to hydrogen or carbon dioxide adds a related class of preparation work.
⮞In April 2026, STATS Group, backed by Mitsui & Co., agreed to acquire Aberdeen-based Pipelines 2 Data (P2D), a specialist in smart pipeline cleaning, surveys, and data analytics with about 30 staff and hubs in Canada and the USA. The acquisition lets STATS combine inspection, diagnostics, maintenance, and repair on one platform.
By Service Type, Pipeline Inspection Dominates the Pipeline & Process Services Market and Leak Detection Grows Fastest
Inspection holds the top position within the service mix because no pipeline owner can plan maintenance or satisfy integrity obligations without condition data. Inline tools using magnetic flux leakage, ultrasonics, and geometry sensors are run on a defined cycle, and non-destructive testing crews supplement them on facilities and unpiggable segments. Awards such as Oceaneering's five-year contract from a Qatar-based oil company reflect the preference for long-term inspection frameworks backed by digital reporting. Inspection results also drive downstream spending on cleaning, repair, and replacement, so providers treat the activity as the entry point to wider relationships with each operator.
Leak detection is the fastest growing service as operators face tighter emissions expectations, higher product values, and public sensitivity to releases. Pressure-pulse systems, acoustic sensors, fiber-optic monitoring, free-swimming platforms, and satellite imagery now detect small losses that earlier methods missed. Water utilities are among the keenest adopters, seeking to reduce non-revenue water, while gas and liquids operators deploy continuous monitoring on high-consequence segments. Providers are packaging detection with analytics and automated reporting, which shortens the path from alert to repair and supports subscription-style contracts. Hydrogen and carbon dioxide lines, where tolerance for losses is lower, supply a further stimulus.
⮞In July 2026, a Qatar-based oil company awarded Oceaneering's Integrity Management and Digital Solutions segment a five-year inspection and asset integrity services contract following a competitive tender. The scope covers non-destructive testing, inspection, and digital reporting delivered by Oceaneering's Qatar-based workforce, with two optional one-year extensions.
By End-User, Oil and Gas Dominates the Pipeline & Process Services Market and Water and Wastewater Grows Fastest
Oil and gas companies are the anchor customers, buying services for upstream gathering, midstream transmission, and downstream process plants alike. Their asset base is large, their products are hazardous, and their regulators and insurers expect documented integrity, which together create sustained service budgets. National oil companies, integrated majors, and pipeline operators contract global providers for commissioning of LNG, floating production, and refinery facilities, and for inspection and cleaning of operating lines. Projects in the Gulf of America, Guyana, Mexico, and the North Sea provide visibility for several years, and the sector's long familiarity with pigging makes it the most mature buyer of the full service range.
Water and wastewater utilities are expanding their purchases fastest from a smaller base, driven by ageing mains, leakage losses, and funding earmarked for asset renewal. Free-swimming inspection platforms that locate leaks, gas pockets, and pipe position in a single run allow utilities to assess large-diameter mains without interrupting service. Condition assessment results feed capital plans, so inspection leads naturally to rehabilitation and relining work. Utilities are also adopting pressure monitoring, acoustic sensing, and automated reporting that align with digital asset records. Technology suppliers with oil and gas pedigree are adapting tools to water networks, widening the service pool and shortening procurement cycles.
⮞In August 2026, Xylem launched SmartBall x, an inspection platform that lets water and wastewater utilities detect leaks and gas pockets, map pipeline position, and record pressure profiles in a single run. The platform deploys through existing pipeline access points and includes automated analysis and digital reporting, allowing long-distance inspections without interrupting service.
By Location, Onshore Dominates the Pipeline & Process Services Market and Offshore Grows Fastest
Onshore operations account for the larger share because the bulk of pipeline length, gas processing capacity, and refining sits on land, where access is straightforward and mobilization costs are comparatively low. Service crews run pigs, test sections, and perform hot tapping with standard equipment spreads, and contracts are frequently awarded by region to local branches of global providers. Shale basins, interstate gas transmission, and urban distribution networks generate frequent campaigns, and regulatory inspection cycles keep schedules full. Local manufacturing of fittings and tooling, as seen in new Gulf Coast facilities, further shortens lead times for onshore customers and reinforces the segment's position.
Offshore work is growing fastest as deepwater developments in Guyana, Mexico, Brazil, West Africa, and Southeast Asia move from installation to start-up. Subsea flowlines, risers, and umbilicals must be flooded, cleaned, gauged, hydrotested, and dewatered from vessels or floating hosts before production, and the equipment spreads involved are large and specialized. Pre-commissioning is typically sequenced around the installation vessel's critical path, so providers with embedded planners and pre-positioned equipment are favored. Late-life fields add flushing and decommissioning scopes, while unmanned pumping units and remote monitoring are lowering the cost and risk of working at depth.
⮞In August 2026, PipeSense completed its first offshore deployment, using its pressure-pulse PipeScan technology off Angola to locate obstructions for a multinational operator. The Houston-based company found a blockage about 11 kilometers downstream of the launch facility on a 20-inch gas pipeline and another within roughly 700 meters on a flooded 16-inch crude and multiphase line.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.47% |
|
Europe |
United Kingdom |
24.58% |
|
Asia Pacific |
China |
38.92% |
|
Latin America |
Brazil |
44.81% |
|
Middle East & Africa |
Saudi Arabia |
28.73% |
North America Pipeline & Process Services Market Insights
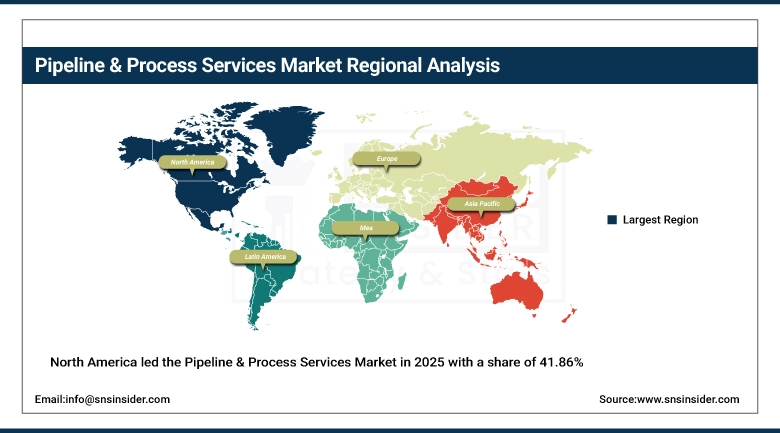
North America led the Pipeline & Process Services Market in 2025 with a share of 41.86%, reflecting the size of its pipeline network, the density of shale gathering systems, and the concentration of service providers in Houston, Tulsa, and Calgary. Operators maintain extensive transmission, gathering, and distribution networks, with a large portion built several decades ago, so integrity programs, cleaning campaigns, and isolation work recur each year. LNG export growth on the Gulf Coast and takeaway projects in the Permian add pre-commissioning and commissioning scope. Providers are localizing manufacturing and expanding field bases to shorten response times, and acquisitions among midstream owners keep the asset base under active management.
Canada contributes through oil sands, gas, and export systems in Alberta and British Columbia, where a CAN$2.7 billion joint venture led by KKR with Apollo is funding expansions on the Westcoast Pipeline System and Canadian Utilities has begun construction of the Yellowhead Pipeline. Each new line brings cleaning, hydrotesting, and commissioning work, and Calgary hosts inspection and pigging specialists. Mexico adds deepwater pre-commissioning demand through developments such as Trion, as well as gas pipeline rehabilitation by national operators. Cross-border gas flows between the three countries keep inspection and repair campaigns active, and regional suppliers export tools and crews to Latin America.
⮞In March 2026, Houston-based PipeSense launched PipeTrack, a system that tracks pigs during pigging operations using pressure sensors at small-diameter branch points, leak-detection software, and AI-based analysis. The set-and-forget installation estimates pig speed and location on a remote dashboard, reducing crew movement along the right-of-way and personnel exposure in hazardous conditions.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Pipeline & Process Services Market Insights
Europe holds the second-largest regional position, supported by North Sea topside and subsea assets, an extensive cross-border gas grid, and a growing hydrogen and carbon dioxide agenda. British, Norwegian, and Dutch contractors supply pre-commissioning, process cleaning, and integrity services to offshore operators, and several are adding capacity near Aberdeen and Stavanger. Gas transmission operators schedule inline inspection programs and assess unpiggable lines with non-intrusive methods. Decommissioning of older North Sea fields is generating flushing and cleaning contracts that should extend into the next decade, and alliances between service firms and installation contractors are becoming more common.
The United Kingdom is the largest national market, with Aberdeen and Aberdeenshire serving as bases for Halliburton's Pipeline & Process Services unit, EnerMech, and STATS Group, and with the Northern Endurance Partnership's carbon storage network bringing a pipelay vessel to the Southern North Sea in September 2026. Germany and the Netherlands combine large process industries with hydrogen core network planning, and German specialists such as 3P Services supply inline inspection. Norway's offshore operators award long integrity frameworks, while Baltic and Central European gas operators renew inspection capability. Regional providers also export crews to Africa and the Middle East.
⮞In August 2026, Lithuania's gas transmission operator Amber Grid awarded ROSEN a three-year contract for its Non-Intrusive Pipeline Assessment service on about 221 kilometers of complex, unpiggable pipeline. The service assesses pipeline condition from above ground, extending integrity assessment to lines that standard inline cleaning and inspection tools cannot traverse.
Asia Pacific Pipeline & Process Services Market Insights
Asia Pacific is the fastest growing regional market, projected to register a CAGR of 7.21% from 2026 to 2035, as new pipelines, LNG terminals, refineries, and offshore developments come on stream across China, India, Australia, and Southeast Asia. Governments and national oil companies are expanding gas networks to reduce reliance on coal, and many of these assets are young, so early-life commissioning work dominates before maintenance volumes rise. Providers are establishing local bases to meet in-country requirements: Trans Asia operates from the UAE, Singapore, Indonesia, and India, and global firms are buying regional maintenance specialists to secure field capacity.
China's pipeline network is the largest in the region, supported by national inspection firms that participate in industry bodies such as the Pigging Products and Services Association. In Malaysia, PETRONAS awarded ROSEN a five-year Pan Malaysia in-line inspection contract covering about 200 pipelines, and STATS Group has signed a three-year pipeline isolation contract with a Malaysian operator. India's providers, such as Noida-based VDT Pipeline Integrity Solutions, are developing inline inspection tools locally, while Australia's LNG sector sustains demand for process cleaning and hydrotesting. Southeast Asian offshore tie-backs add subsea pre-commissioning work.
⮞In December 2025, T.D. Williamson acquired the assets and operations of Pro Pipe Services, a pipeline maintenance provider in Australia. The deal combines Pro Pipe's pipeline intervention and isolation work with TDW's hot tapping, pressure isolation, inline inspection, and pigging technologies, bringing faster mobilization and local support to Australian operators.
MEA & Latin America Pipeline & Process Services Market Insights
The Middle East & Africa is anchored by Gulf producers with large-diameter crude and gas networks and by service hubs in the UAE, Qatar, Saudi Arabia, and Kuwait. National oil companies award multi-year inspection and integrity contracts, and offshore pipelines in the Gulf call for specialized inline tools and nitrogen and pumping spreads. Trans Asia, headquartered in Sharjah, supplies pre-commissioning and process services across the region. In West Africa, offshore operators off Angola and Nigeria are adopting remote obstruction and leak location methods, and East African LNG developments in Mozambique are entering the supply stage, with line pipe awards signaling future commissioning work. Local-content expectations are pushing providers to open regional bases.
⮞In July 2026, Applus+ secured a renewal and significant scope expansion of a long-term offshore pipeline integrity contract with a leading UAE organization for an additional five years. The scope covers nitrogen supply, pumping spreads, mechanical cleaning, gauging, and inline inspection of piggable and unpiggable pipelines using the DTI Trekscan free-swimming, bi-directional tool.
Latin America is a growing market led by Brazil, Guyana, Mexico, and Argentina, with Trinidad and Tobago adding gas and subsea developments. Brazilian operators run extensive offshore flowlines that require pigging and flushing, and local providers such as 4Pipe Hidropig support mining and industrial pigging. In Guyana, Saipem awarded EnerMech subsea pre-commissioning for the Whiptail development in the Stabroek Block in January 2026, extending a pattern of repeat work for ExxonMobil's programs. Trinidad and Tobago hosts bp's Ginger and Shell's Manatee developments, and Argentina's shale infrastructure needs gathering line and processing services. Houston-based providers support the region from shared equipment pools.
⮞In October 2026, EnerMech won a Subsea7 contract for the full pre-commissioning package for the Ginger subsea development offshore Trinidad and Tobago, covering testing, flushing, hydrotesting, water filling, leak testing, and commissioning support. The company is mobilizing local staff and equipment already in the Caribbean region.
Market Dynamics
Growth Drivers: Ageing Pipeline Infrastructure and New Gas, LNG, and Offshore Capacity
Ageing pipeline infrastructure is the foundation of recurring service demand. Many transmission and gathering systems in North America, Europe, and the Middle East were built decades ago, and wall loss, cracking, and seam defects become more probable with each year in service. STATS Group estimates that about half of regulated U.S. pipelines were built before 1970, and operators in other mature regions face comparable profiles. Integrity programs therefore call for regular cleaning, inline inspection, assessment of unpiggable lines, and repair, usually under multi-year frameworks. Larger diameters and higher operating pressures raise the stakes, pushing buyers toward higher-resolution tools and more frequent campaigns that benefit established inspection and pigging providers.
New gas, LNG, and offshore capacity forms the second driver, because each new line or plant requires cleaning, testing, drying, and commissioning before it can operate. LNG liquefaction trains, floating production units, subsea tie-backs, and processing plants are scheduled across North America, Australia, Africa, and Guyana, and each creates multi-week mobilizations for pumping, filtration, nitrogen, and chemical cleaning crews. Pipeline additions for power generation, industrial users, and export terminals extend the work onshore. Operators and EPC contractors are awarding pre-commissioning packages earlier in project schedules, which improves equipment planning for providers and lifts the visibility of their order books.
⮞In October 2024, NDT Global and Aramco unveiled a 56-inch ultrasonic inline inspection tool, the largest of its kind NDT Global has developed, for large-diameter pipelines traditionally inspected with magnetic flux leakage and caliper methods. The tool is designed to navigate complex networks, detect cracks and metal loss, and generate data for predictive analysis and risk management.
Restraints: Capital Spending Cyclicality and Skilled Labor and Equipment Constraints
Spending on pipeline and process services follows the capital and operating budgets of oil and gas companies, which respond to commodity prices, project sanction timing, and financing conditions. Pre-commissioning and commissioning awards are tied to construction schedules, so delays in permitting or equipment delivery push work into later periods and leave crews and pumping spreads idle. Operators also defer discretionary maintenance when margins tighten, and tender processes frequently emphasize price, compressing margins on standard scopes. Revenue for providers is lumpy as a result, and smaller firms with limited diversification face pressure when a major project slips or a framework agreement is rebid. Payment and sanctions issues add risk in selected markets.
Skilled labor, safety requirements, and equipment availability constrain how quickly providers can scale. Pipeline pigging, nitrogen, hydrotesting, and isolation work involves high pressures and hazardous fluids, so personnel require specialist certification and long field experience, and the pool of experienced supervisors is limited. Offshore programs depend on vessel availability and complex logistics, while large pumping and nitrogen fleets represent significant capital that must be maintained and certified. Local-content expectations in Africa, the Middle East, and Latin America require providers to establish regional bases and train staff, adding cost and time. A single incident can also affect contract eligibility, which makes safety performance a competitive gate.
Opportunities: Hydrogen and Carbon Dioxide Pipeline Readiness and Digital Automation
Hydrogen and carbon dioxide pipeline readiness offers a new class of work. Operators evaluating blending, conversion, or new-build networks need inspection to establish baseline condition, cleaning and drying before new media are introduced, and isolation capability for live tie-ins. Trials in the United Kingdom and Europe have shown that line stopping and inline inspection can be performed in hydrogen service, and carbon capture projects in the North Sea are adding offshore pipeline scopes. Providers with qualified procedures and tools for these fluids can enter engineering-led contracts earlier in the project cycle, and early references are likely to carry weight as national networks scale up.
Digital automation is a second opportunity because it raises quality while lowering the cost of field work. Automated pig-speed control, pig tracking by pressure sensing, free-swimming leak detection, autonomous pumping units, and remote data delivery reduce crew size and exposure and improve inspection data. Service providers can sell these capabilities as subscription or performance-based offerings, supported by analytics that prioritize repairs. Utilities and midstream firms that lack in-house expertise are receptive to packaged programs, and technology developed for oil and gas can be adapted to water, gas distribution, and chemical networks, broadening the addressable customer base.
⮞In September 2026, Expro launched Velonix, a pipeline pig control system that uses a non-intrusive clamp-on sonar meter to measure pig velocity and a digitally controlled skid to adjust flow automatically. Designed for low-flow, high-flow, and no-flow lines, it aims to reduce re-runs, improve inspection data quality, and cut manual intervention during pigging campaigns.
Recent Developments:
-
October 2024: Pigs Unlimited International acquired the assets of the manufacturing division of Pipeline Pigging Products, effective October 1, 2024, adding trained staff and customers. The Tomball, Texas company operates a 100,000-square-foot cleaning pig plant and plans to pair its products with Flowmore Services' pipe cleaning.
-
October 2025: IKM Operations, part of IKM Group, won an integrity management services contract from Aker BP covering engineering services and inspections on offshore installations, with a five-year term and an estimated value above NOK 1 billion. IKM Inspection will supply inspection work, while IKM Testing will provide drone technology.
-
September 2026: NDT Global launched QUADRA, an inline inspection system that combines ultra-high-resolution axial magnetic flux leakage with circumferential MFL and complementary data in a single run. The modular platform builds on the Trinity technology and targets corrosion, narrow axial features, seam-related anomalies, and hard spots, with a showcase at IPCE 2026 in Calgary.
-
December 2025: EnerMech was awarded a pre-commissioning scope by Bechtel for Woodside's Pluto LNG Train 2 in Karratha, Western Australia, covering chemical cleaning of the acid gas removal unit and the heated water system. The scope includes supervision, personnel, chemicals, test instruments, equipment, and licensed waste handling.
Pipeline & Process Services Market Key Players are:
-
T.D. Williamson, Inc. (TDW)
-
ROSEN Group
-
Baker Hughes Company (Pipeline & Process Services, Quest Integrity)
-
Halliburton Company
-
EnerMech Ltd.
-
IKM Group AS (IKM Testing)
-
STATS Group
-
NDT Global
-
Expro Group Holdings N.V.
-
Oceaneering International, Inc.
-
Hydratight (Enerpac Tool Group)
-
Trans Asia Group (Trans-Asia Pipeline Services)
-
Enduro Pipeline Services, Inc.
-
Altus Intervention
-
BlueFin Services (Gate Energy)
-
TEAM, Inc.
-
Techfem S.p.A.
-
Weatherford International plc
-
MISTRAS Group, Inc.
-
Intertek Group plc
Pipeline & Process Services Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.98 Billion |
| Market Size by 2035 | USD 6.92 Billion |
| CAGR | 5.68% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Asset Type: Dominant – Pipeline (69.42% share in 2025); Fastest-Growing – Process (CAGR 6.47%) • By Operation: Dominant – Maintenance (36.42% share in 2025); Fastest-Growing – Decommissioning (CAGR 7.34%) • By Service Type: Dominant – Pipeline Inspection (22.86% share in 2025); Fastest-Growing – Leak Detection (CAGR 8.12%) • By End-User: Dominant – Oil and Gas (61.27% share in 2025); Fastest-Growing – Water and Wastewater (CAGR 7.43%) • By Location: Dominant – Onshore (68.93% share in 2025); Fastest-Growing – Offshore (CAGR 6.74%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | T.D. Williamson, Inc. (TDW), ROSEN Group, Baker Hughes Company (Pipeline & Process Services, Quest Integrity), Halliburton Company, EnerMech Ltd., IKM Group AS (IKM Testing), STATS Group, NDT Global, Expro Group Holdings N.V., Oceaneering International, Inc., Hydratight (Enerpac Tool Group), Trans Asia Group (Trans-Asia Pipeline Services), Enduro Pipeline Services, Inc., Altus Intervention, BlueFin Services (Gate Energy), TEAM, Inc., Techfem S.p.A., Weatherford International plc, MISTRAS Group, Inc., Intertek Group plc |

Frequently Asked Questions
Key players include T.D. Williamson, Inc., ROSEN Group, Baker Hughes Company, Halliburton Company, and EnerMech Ltd., among others.
Hydrogen and carbon dioxide pipeline readiness, together with digital automation of pigging, leak detection, and inspection services, represent the primary opportunities.
Growth is primarily driven by ageing pipeline infrastructure that requires recurring cleaning, inspection, and repair, combined with new gas, LNG, and offshore capacity that needs pre-commissioning and commissioning services.
By Asset Type, Pipeline dominated the market with approximately 69.42% share in 2025, reflecting the recurring cleaning, inspection, and repair needs of long transmission and distribution networks.
North America dominated the market with approximately 41.86% share in 2025, driven by an extensive pipeline network, shale gathering systems, and a dense base of service providers in Houston, Tulsa, and Calgary.
