
Retinal Imaging Devices Market Report Scope & Overview:
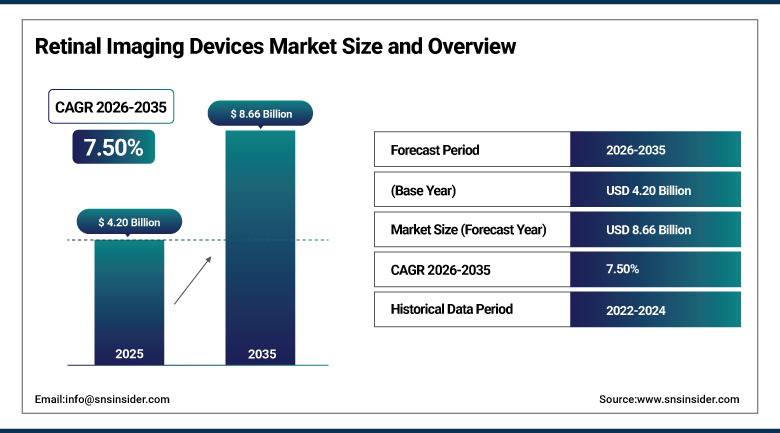
The Retinal Imaging Devices Market was valued at USD 4.20 Billion in 2025 and is expected to reach USD 8.66 Billion by 2035, growing at a CAGR of 7.50% from 2026-2035.
The retinal imaging devices market growth can be attributed to the increased prevalence of conditions such as diabetic retinopathy, age-related macular degeneration, and glaucoma and the increase in eye screening programs across the world. Improvements in optics, high resolution imaging, and computational algorithms will improve diagnostic precision, improve efficiency, and enable early detection of diseases. More hospitals are opting for the use of multimodal machines that use fundus photography, optical coherence tomography (OCT), and OCT angiography, thus making work easier since there is no need for the separate devices. Growth of the geriatric population, availability of preventative eye care in emerging economies, and increasing demand for remote retinal diagnosis will drive the opportunities in the market.
⮞In May 2026, Revenio Group completed its acquisition of Visionix, combining complementary ophthalmic diagnostic portfolios spanning fundus imaging, OCT, and other eye-care technologies. The transaction strengthened Revenio’s ability to offer integrated diagnostic solutions across optometry and ophthalmology.
To Get more information Retinal Imaging Devices Market - Request Free Sample Report
Retinal Imaging Devices Market Trends
-
Multimodal platforms combining fundus photography, OCT, and OCT angiography into a single connected system are increasingly displacing single-modality devices.
-
AI-powered autonomous screening systems capable of detecting diabetic retinopathy without physician interpretation are expanding into primary care and community health settings.
-
Home-based and portable OCT devices are extending retinal disease monitoring beyond the clinic for patients managing chronic conditions such as wet AMD.
-
Handheld, non-mydriatic fundus cameras are gaining traction in point-of-care and rural screening programs that lack access to full benchtop imaging suites.
-
Ultra-widefield and swept-source OCT platforms are gaining share as clinicians seek broader peripheral retinal visualization in a single scan.
-
Consolidation among established ophthalmic diagnostic imaging vendors is accelerating as companies pursue broader, integrated eye care portfolios.
U.S. Retinal Imaging Devices Market Outlook
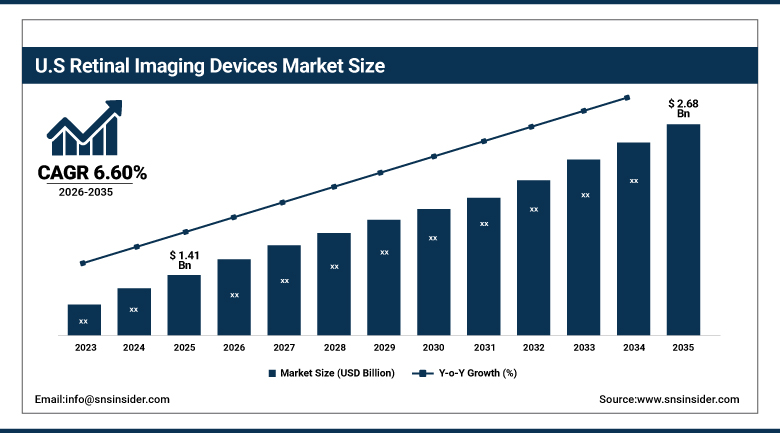
The U.S. Retinal Imaging Devices Market was valued at USD 1.41 Billion in 2025 and is expected to reach USD 2.68 Billion by 2035, growing at a CAGR of 6.60% from 2026-2035.
The U.S. Retinal Imaging Devices Market growth continues to be reinforced by the country's high prevalence of diabetic retinopathy and age-related macular degeneration, well-established Medicare and private payer reimbursement for retinal imaging as a covered diagnostic procedure, and a dense network of retina specialty practices and academic ophthalmology centers. Screening programs embedded within primary care settings are increasingly incorporating autonomous AI-based fundus image analysis, while device manufacturers with major commercial operations in the United States maintain close clinical feedback loops with leading retina practices that accelerate iterative product improvements and support rapid adoption of newly cleared technologies.
⮞In July 2025, Notal Vision reported pivotal study findings supporting the diagnostic equivalence of its SCANLY Home OCT system and conventional in-office OCT imaging for monitoring neovascular age-related macular degeneration, reinforcing the potential for physician-supervised retinal monitoring outside specialist clinics.
Retinal Imaging Devices Market Segment Analysis
-
By Device Type, the Optical Coherence Tomography (OCT) Systems segment dominated the Retinal Imaging Devices Market with approximately 38.60% share in 2025, while the OCT Angiography (OCTA) Systems segment is the fastest growing with a CAGR of approximately 9.85%.
-
By Application, the Diabetic Retinopathy segment dominated the Retinal Imaging Devices Market with approximately 41.20% share in 2025, while the Age-related Macular Degeneration segment is the fastest growing with a CAGR of approximately 9.30%.
-
By End User, the Hospitals segment dominated the Retinal Imaging Devices Market with approximately 47.80% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of approximately 9.60%.
-
By Connectivity, the Standalone Systems segment dominated the Retinal Imaging Devices Market with approximately 61.30% share in 2025, while the Cloud-Connected Systems segment is the fastest growing with a CAGR of approximately 11.40%.
By Device Type, OCT Systems Dominates and OCT Angiography Systems Grows Fastest
OCT systems remain the market leader because they provide cross-sectional, high-resolution visualization of retinal layers that fundus photography alone cannot capture, making them indispensable for diagnosing and monitoring diabetic macular edema, AMD, and glaucoma. Retina specialty practices and academic centers standardize on OCT as the core diagnostic instrument in their imaging suites, and continued advances in swept-source scanning speed and image resolution reinforce this segment's leading position across both hospital and clinic settings.
OCT angiography systems are expanding at the fastest pace as clinicians increasingly value dye-free visualization of retinal and choroidal vasculature that eliminates the need for invasive fluorescein injection in many routine cases. This segment benefits from growing evidence supporting OCTA's utility in detecting early vascular changes associated with diabetic retinopathy and neovascular AMD, and vendors integrating OCTA as a software or hardware upgrade to existing OCT platforms are accelerating adoption across their installed base.
⮞In September 2026, ZEISS introduced ALTA DUO 300, a compact multimodal platform combining automated OCT, OCT angiography, and fundus imaging. Designed for streamlined retinal assessment, the system illustrates continued investment in integrated imaging platforms for ophthalmology practices.
By Application, Diabetic Retinopathy Dominates and Age-related Macular Degeneration Grows Fastest
Diabetic retinopathy is the biggest application by virtue of highlighting the huge prevalence of diabetes across the globe and the importance of getting regular retina examinations to prevent the loss of vision. The health care industry as well as insurers have made yearly or biannual retinal scanning mandatory for diabetic patients as part of their standard care protocols in the interest of promoting regular retinal screenings.
Age-related macular degeneration is the fastest growing segment owing to the increase in the number of aging people globally and due to developments in the treatment of this condition. This is due to the advent of the home-based optical coherence tomography technology that makes it easier to monitor the development of the disease among patients suffering from chronic neovascular age-related macular degeneration.
⮞In February 2025, Notal Vision announced pivotal study findings demonstrating the performance of artificial intelligence in interpreting home OCT scans for patients with neovascular age-related macular degeneration, supporting further development of remote retinal fluid monitoring.
By End User, Hospitals Dominate and Ambulatory Surgical Centers Grow Fastest
Hospitals account for the largest share of demand given their high patient volumes, broader case-mix complexity spanning multiple retinal and systemic conditions, and need to equip multiple ophthalmology suites simultaneously with comprehensive imaging instrumentation. Large hospital systems typically standardize on a unified imaging platform across departments to streamline staff training, data management, and integration with electronic health record systems.
Ambulatory surgical centers are growing fastest as retinal procedure volumes continue shifting toward outpatient settings that emphasize efficient patient throughput and same-day surgical scheduling. This segment focuses on compact, fast-acquisition imaging systems that integrate directly with surgical planning workflows, and it benefits from the broader trend of outpatient retinal and vitreoretinal procedure expansion.
⮞In September 2026, Topcon Healthcare unveiled the Maestro3 series, combining OCT, OCT angiography, and fundus imaging within an automated diagnostic workflow. Its integrated imaging and analytics capabilities reflect growing demand for efficient retinal assessment across high-throughput clinical settings.
By Connectivity, Standalone Systems Dominate and Cloud-Connected Systems Grow Fastest
Standalone systems are still popular, providing dependable and self-sufficient imaging solutions that do not depend on the existing network infrastructure. Standalone devices are still the most commonly used solutions by hospitals and clinics using already developed methods of managing their data management process due to many years of clinical research and simple integration with local picture archiving systems.
Cloud-connected systems are expanding at the fastest pace as screening programs increasingly rely on remote image grading, AI-based automated analysis, and centralized data aggregation across multiple screening sites. This segment benefits from the rapid growth of autonomous AI screening services and home-based monitoring platforms that depend on continuous data transmission between patients, monitoring centers, and treating physicians, positioning connected systems as the fastest-growing category in an increasingly decentralized screening landscape.
⮞In August 2026, ZEISS received U.S. FDA 510(k) clearance for CLINIC 360, a cloud-based ophthalmic data management solution integrating diagnostic imaging and clinical records. The platform supports cross-location data access and analytics for connected eye-care workflows.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
23.90% |
|
Asia Pacific |
China |
33.40% |
|
Middle East & Africa |
GCC Countries |
44.90% |
|
Latin America |
Brazil |
47.30% |
North America Retinal Imaging Devices Market Insights
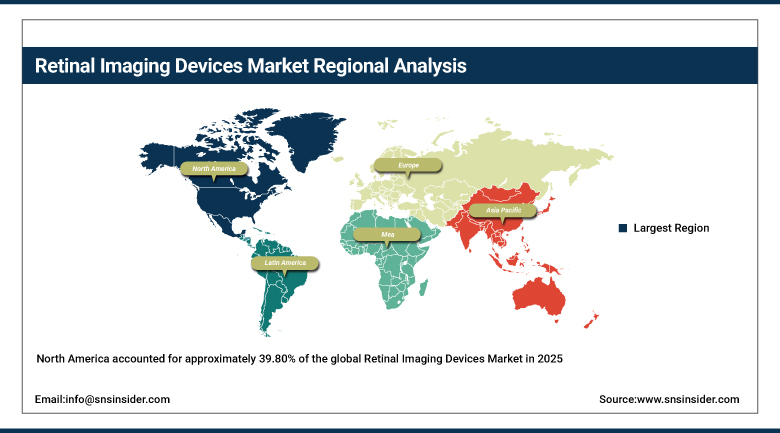
North America accounted for approximately 39.80% of the global Retinal Imaging Devices Market in 2025, the largest share of any region, supported by high prevalence of diabetic retinopathy and AMD, comprehensive reimbursement for retinal diagnostic imaging, and a concentration of leading device manufacturers with significant commercial operations domestically. The United States drives the substantial majority of regional demand, reflecting its dense network of retina specialty practices, academic ophthalmology programs, and expanding primary-care-based AI screening initiatives.
Canada contributes a smaller but steadily growing share of regional revenue, aided by provincial investment in diabetic retinopathy screening programs and gradual replacement of older fundus-only camera systems with combined OCT and OCTA platforms across public hospital eye departments. Distribution partnerships and software upgrade paths for existing installed devices continue to shape regional competitive dynamics as vendors work to extend equipment life while capturing incremental revenue.
⮞In July 2025, Optomed USA launched the Lumo handheld fundus camera for retinal imaging across primary care and community settings. The device offers non-mydriatic image capture, wireless DICOM connectivity, and programmable workflows, supporting broader access to retinal screening.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Retinal Imaging Devices Market Insights
Europe is the second-largest regional market, with the biggest contribution coming from Germany, the UK, and France. The demand is shaped by centralized procurement through the health system of each country, compliance with the EU Medical Device Regulation, and existing diabetic eye screening programs in each country integrating retinal imaging into public health system.
Germany is shaping regional uptake with a robust mix of private and government-run ophthalmology networks and a pioneering approach towards multimodal OCT and OCTA systems. The UK continues to standardize retinal imaging with its National Health Service Diabetic Eye Screening Program in terms of annual imaging as part of national diabetes pathway programs. The development of already existing OCT systems, including new FDA approved OCTA models and simultaneous fluorescein-ICG angiography modules, allows the companies to increase capabilities of the equipment that has been already sold without having to replace it.
⮞In July 2026, Topcon announced European MDR CE marking for its ultra-widefield retinal slit scanner, enabling its introduction in the European market. The system expands retinal visualization capabilities and adds another option for ophthalmic clinics evaluating advanced imaging equipment.
Asia Pacific Retinal Imaging Devices Market Insights
Asia Pacific is the fastest-growing regional market, projected to expand at a CAGR of approximately 9.75% between 2026 and 2035, driven by a rapidly aging population, rising diabetes prevalence, and growing government investment in vision screening infrastructure across China, Japan, and India. China represents the largest national market within the region, supported by rapid hospital construction and a growing base of domestic retinal imaging device manufacturers.
Japan continues to represent a mature, technology-forward market characterized by early adoption of AI-assisted screening platforms, while India and the broader Southeast Asian market are contributing an increasing share of regional growth as private eye care chains and government-backed diabetic retinopathy screening programs expand access to retinal imaging beyond metropolitan hospitals into rural and semi-urban health centers.
⮞In December 2025, India's Armed Forces Medical Services, AIIMS, and Ministry of Health launched an AI-driven diabetic retinopathy screening initiative using handheld fundus cameras and MadhuNetrAI. Its seven-location pilot aims to expand community screening and specialist referral access.
MEA & Latin America Retinal Imaging Devices Market Insights
The Middle East & Africa region is driven by the GCC countries, which feature state-sponsored construction of hospitals and investment in specialty eye care in Saudi Arabia and the UAE and which will increase the uptake of retinal imaging technology in the new surgico-diagnostic centers opened in this area. South Africa leads among African countries as the major contributor owing to its comparatively developed private network of ophthalmologists, although the regional adoption level is restricted by lack of access to specialized eye care infrastructure.
Latin America is led by Brazil, the major revenue generator in this region due to the highly developed public and private networks of ophthalmologists and the increasing number of cases of diabetic retinopathy diagnosis performed via public health programs and private insurances. The second major country in this region is Mexico, which benefits from increased investment in the private healthcare system. Growth is rapidly accelerating elsewhere in the region due to national health ministry’s focus on diabetic eye disease diagnosis.
⮞In September 2026, Saudi Arabia's Food and Drug Authority granted marketing authorization to SAARIA, locally developed AI software for analyzing retinal fundus images and supporting diabetic retinopathy screening. The authorization demonstrates growing regional adoption of AI-assisted retinal diagnostic workflows.
Market Dynamics
Growth Drivers: Rising Retinal Disease Prevalence and Expanding Screening Programs
Growth in the Retinal Imaging Devices Market is fundamentally supported by the rising global prevalence of diabetic retinopathy, age-related macular degeneration, and glaucoma, conditions that require regular retinal imaging for early detection and ongoing disease management. Expanding population-level screening programs, particularly for diabetic retinopathy, are embedding retinal imaging into routine primary care and endocrinology referral pathways well beyond its traditional confinement to specialist ophthalmology settings.
Rising geriatric populations requiring more frequent monitoring for AMD and other age-related retinal conditions, combined with growing adoption of AI-based autonomous screening that reduces dependence on specialist image interpretation, is reinforcing sustained procurement of imaging equipment. Continued advances in optical hardware and computational imaging, including swept-source OCT and OCT angiography, are further expanding the addressable base for higher-precision diagnostic platforms.
⮞In December 2025, the American Diabetes Association published its 2026 Standards of Care, recognizing retinal photography with remote interpretation or FDA-authorized AI algorithms as appropriate diabetic retinopathy screening strategies when supported by timely specialist referral pathways.
Restraints: High Equipment Costs and Reimbursement Variability
The initial cost associated with purchasing high-end OCT and OCTA machines is still a major barrier for small-scale clinics and screening facilities within the healthcare sector that has tight financial limitations. The additional costs for continuous software subscriptions, cloud services, and updates of modules also increase the overall cost of ownership for these systems, which discourages practices from upgrading the equipment and leads to using outdated fundus-only cameras.
There is no unified policy for reimbursement for modern imaging technology and autonomous AI screening services that makes it hard for practices to consider investing in new technologies. The complexity of regulations in various national medical device environments and the necessity to prove the value of new AI algorithms through existing procedures make it difficult to replace old equipment.
Opportunities: AI-Powered Screening and Home-Based Monitoring
The expansion of AI-powered autonomous screening systems capable of detecting diabetic retinopathy and other retinal conditions without specialist interpretation represents a significant opportunity, as health systems seek to extend screening access into primary care and community settings that lack on-site ophthalmologists. Manufacturers that successfully combine imaging hardware with validated AI analytics are well positioned to capture a larger share of population-level screening initiatives.
Home-based and portable retinal imaging equipment is providing increased scope to conduct remote monitoring of diseases such as wet age-related macular degeneration, which does not require regular visits to the clinic but will allow clinical supervision at the same time. As the capacity of diabetic retinopathy testing and ophthalmic equipment spending is increasing in Asia-Pacific, Middle East, and Latin America regions, there exists a good opportunity for device makers to increase their geographical footprint.
⮞In October 2026, Topcon Healthcare announced the global launch of Oku Digital Health, built on its cloud-connected diagnostic network. The platform uses retinal imaging data and AI-enabled infrastructure to support disease insights and clinical research, demonstrating opportunities beyond conventional eye examinations.
Recent Developments:
-
In October 2025, Optos introduced Silverstone RGB, combining 200-degree single-capture true-color retinal imaging with swept-source OCT technology. The launch expanded its multimodal imaging portfolio for detailed examination of retinal structures.
-
In September 2026, NIDEK launched the RSD-1 Duo OCT/fundus camera, AFC-1 non-mydriatic camera, and EyeLink data management platform, combining automated image acquisition with connected diagnostic workflows and optional OCT angiography capabilities.
-
In October 2025, ZEISS showcased OCT angiography capabilities through CIRRUS AngioPlex and announced U.S. regulatory clearance and European approval for indocyanine green angiography on CLARUS 700, supporting additional retinal vascular imaging applications.
-
In January 2025, AI Optics announced FDA 510(k) clearance for its Sentinel Camera, a portable, non-mydriatic retinal imaging device designed to facilitate image capture in primary care, optometry, and other settings outside specialist ophthalmology clinics.
Retinal Imaging Devices Market Key Players
-
Heidelberg Engineering GmbH
-
Canon Inc.
-
Optos plc (Nikon Corporation)
-
Revenio Group Oyj (iCare, CenterVue)
-
Visionix (Optovue)
-
Optomed Plc
-
Eyenuk, Inc.
-
Notal Vision, Ltd.
-
AI Optics, Inc.
-
AEYE Health, Inc.
-
Kowa Company, Ltd.
-
Santec Corporation
-
Clarity Medical Systems, Inc.
-
Forus Health Pvt. Ltd.
-
Escalon Medical Corp.
-
Adaptica S.r.l.
-
IRIDEX Corporation
Retinal Imaging Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.20 Billion |
| Market Size by 2035 | USD 8.66 Billion |
| CAGR | CAGR of 7.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Device Type (Fundus Cameras, Optical Coherence Tomography (OCT) Systems, OCT Angiography (OCTA) Systems, Fluorescein Angiography Devices, Scanning Laser Ophthalmoscopes, Ultra-widefield/Widefield Imaging Systems) • By Application (Diabetic Retinopathy, Age-related Macular Degeneration, Glaucoma, Retinal Detachment, Other Applications) • By End User (Hospitals, Ophthalmic Clinics, Ambulatory Surgical Centers, Other End Users) • By Connectivity (Standalone Systems, Networked Systems, Cloud-Connected Systems) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Carl Zeiss Meditec AG, Topcon Corporation (Topcon Healthcare), NIDEK CO., LTD., Heidelberg Engineering GmbH, Canon Inc., Optos plc (Nikon Corporation), Revenio Group Oyj (iCare, CenterVue), Visionix (Optovue), Optomed Plc, Eyenuk, Inc., Notal Vision, Ltd., AI Optics, Inc., AEYE Health, Inc., Kowa Company, Ltd., Santec Corporation, Clarity Medical Systems, Inc., Forus Health Pvt. Ltd., Escalon Medical Corp., Adaptica S.r.l., IRIDEX Corporation. |

Frequently Asked Questions
Leading companies include Carl Zeiss Meditec, Topcon Healthcare, NIDEK, Heidelberg Engineering, Canon, Optos, Revenio Group (iCare, CenterVue, and Visionix), Optomed, Eyenuk, and Notal Vision, among others.
Key opportunities include AI-based screening, portable and home retinal monitoring, and expansion across Asia Pacific, the Middle East, and Latin America as diabetic retinopathy programs expand.
Growth is primarily driven by the rising global prevalence of diabetic retinopathy, age-related macular degeneration, and glaucoma, combined with expanding population-level screening programs that embed retinal imaging into routine primary care.
By Device Type, Optical Coherence Tomography (OCT) Systems dominates the market with approximately 38.60% share in 2025, supported by its ability to provide detailed cross-sectional visualization of retinal layers.
North America dominates the market with approximately 39.80% share in 2025, supported by high prevalence of retinal disease, established reimbursement pathways, and a concentration of leading device manufacturers.
