
Therapeutic Bed Market Report Scope & Overview:
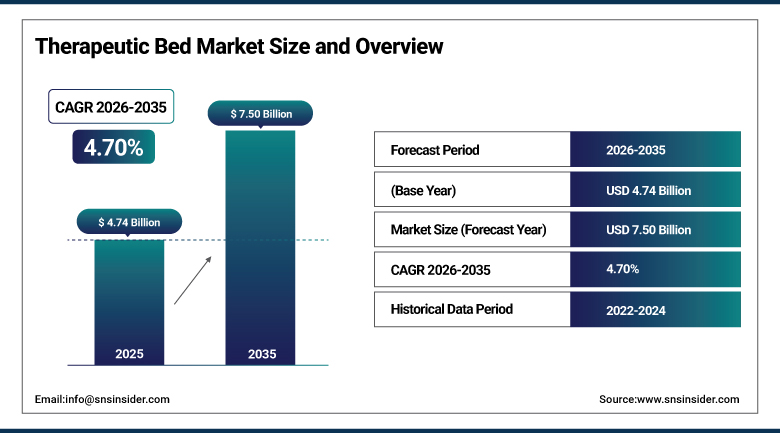
The Therapeutic Bed Market was valued at USD 4.74 Billion in 2025 and is expected to reach USD 7.50 Billion by 2035, growing at a CAGR of 4.70% from 2026-2035.
The Therapeutic Bed Market covers hospital, intensive care, long-term care and home beds designed to support patient treatment, mobility, pressure injury prevention and caregiver safety. Products include adjustable electric beds, ICU beds with integrated monitoring, bariatric beds, low air loss and pressure-relieving surfaces, and specialty beds for birthing and pediatrics. Growth is supported by population aging, rising chronic disease and surgical volumes, hospital construction and the shift toward home care, while capital budget limits, long replacement cycles and price competition shape purchasing.
⮞In February 2025, Stryker launched the ProCeed hospital bed, a medical-surgical platform with a low bed height and a fifth-wheel steering aid. The launch shows how leading suppliers are focusing on caregiver ergonomics and fall prevention in routine hospital care.
To Get more information Therapeutic Bed Market - Request Free Sample Report
Therapeutic Bed Market Segment Analysis
- By Product Type, clinical and ICU beds segment dominated the Therapeutic Bed Market in 2025 with 58.40% share; bariatric beds segment is the fastest-growing segment, with an estimated CAGR of 7.20% during 2026–2035.
- By Application, acute care segment dominated the Therapeutic Bed Market in 2025 with 46.20% share; long-term care segment is the fastest-growing segment, with an estimated CAGR of 6.40% during 2026–2035.
- By Technology, fully electric segment dominated the Therapeutic Bed Market in 2025 with an estimated 52.30% share, and is also the fastest-growing segment, with an estimated CAGR of 6.50% during 2026–2035.
- By End User, hospitals and clinics segment dominated the Therapeutic Bed Market in 2025 with 61.70% share; home healthcare segment is the fastest-growing segment, with an estimated CAGR of 7.40% during 2026–2035.
U.S. Therapeutic Bed Market Outlook
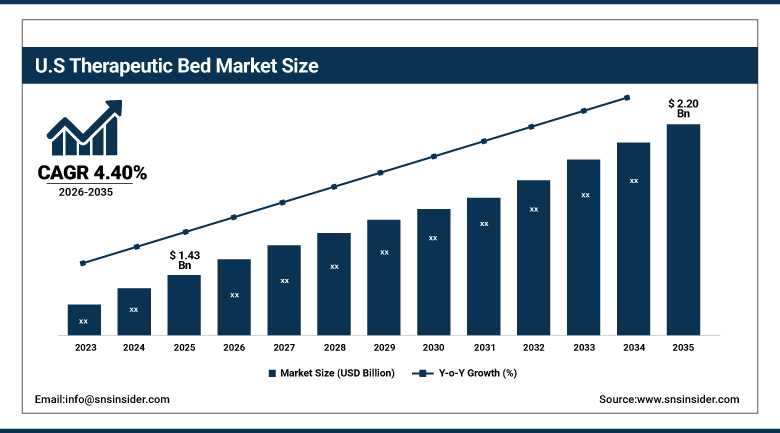
The U.S. Therapeutic Bed Market was valued at USD 1.43 Billion in 2025 and is expected to reach USD 2.20 Billion by 2035, growing at a CAGR of 4.40% from 2026-2035.
The U.S. Therapeutic Bed Market is supported by a large hospital and long-term care sector, high rates of obesity and chronic disease, an aging population, active replacement of older beds with smart models, and reimbursement for home hospital beds under Medicare. Safety programs targeting patient falls and pressure injuries encourage hospitals to upgrade equipment. Growth is moderated by capital budget constraints and by consolidation among suppliers and group purchasing organizations.
⮞In November 2024, MIGA Holdings completed its acquisition of Invacare's North American business. The transaction transferred a major U.S. provider of home and long-term care beds to new ownership, with implications for competition in the home medical equipment channel.
Therapeutic Bed Market Segment Analysis
- By Product Type, clinical and ICU beds segment dominated the Therapeutic Bed Market in 2025 with 58.40% share; bariatric beds segment is the fastest-growing segment, with an estimated CAGR of 7.20% during 2026–2035.
- By Application, acute care segment dominated the Therapeutic Bed Market in 2025 with 46.20% share; long-term care segment is the fastest-growing segment, with an estimated CAGR of 6.40% during 2026–2035.
- By Technology, fully electric segment dominated the Therapeutic Bed Market in 2025 with an estimated 52.30% share, and is also the fastest-growing segment, with an estimated CAGR of 6.50% during 2026–2035.
- By End User, hospitals and clinics segment dominated the Therapeutic Bed Market in 2025 with 61.70% share; home healthcare segment is the fastest-growing segment, with an estimated CAGR of 7.40% during 2026–2035.
By Product Type, Clinical and ICU Beds Dominate Therapeutic Bed Market; Bariatric Beds to Register Fastest Growth.
Clinical and ICU beds dominate the Therapeutic Bed Market because every hospital bed requires an adjustable, safe platform, and critical care units need advanced beds with integrated scales, monitoring and pressure redistribution. These beds represent the largest unit volume and the highest replacement spending, as hospitals refresh fleets on cycles of several years. Leading suppliers such as Stryker, Baxter's Hillrom, Arjo, LINET and Getinge compete on safety features and connectivity. Service contracts, parts supply and staff training further tie hospitals to their chosen suppliers and sustain aftermarket revenue.
Bariatric beds are projected to register the fastest growth as obesity rates rise and hospitals need equipment rated for higher weight capacity, with wider frames and reinforced mechanics. Specialty and pressure-relieving beds, including low air loss and alternating pressure surfaces, are also growing because pressure injuries are costly and are increasingly penalized by payers. Household beds and accessories serve home care users and add recurring revenue through mattresses, rails and parts. Specialty surfaces are often rented to hospitals, which supports recurring revenue for manufacturers with rental fleets.
By Application, Acute Care Dominates Therapeutic Bed Market; Long-Term Care to Register Fastest Growth.
Acute care beds dominate the Therapeutic Bed Market because hospitals operate the largest number of beds for general wards, surgical recovery and emergency admissions. Procedures and admissions are rising with aging populations, and new hospital projects in emerging markets add to installations. Acute care buyers prioritize features such as height adjustment, fall prevention, easy cleaning and integration with nurse call and electronic records systems. Short stays and rapid patient turnover also demand beds that can be cleaned and reconfigured quickly, which favors models with smooth surfaces and fewer crevices.
Long-term care beds are projected to register the fastest growth as nursing homes, rehabilitation centers and assisted living facilities expand to meet the needs of older adults. These facilities value durability, ease of use for caregivers and pressure injury prevention, and they often buy through national chains with standardized fleets. Critical care beds remain a high-value segment, supported by intensive care capacity expansion and demand for advanced monitoring features. Staffing shortages in nursing homes also make features that reduce lifting and repositioning effort more valuable to operators.
By Technology, Fully Electric Beds Dominate Therapeutic Bed Market and Are Also the Fastest-Growing Technology.
Fully electric beds dominate the Therapeutic Bed Market because they allow caregivers to adjust height, head and foot sections with a touch of a button, which reduces physical strain and improves patient positioning. Hospitals have largely moved to electric platforms for ergonomic and safety reasons, and the technology is now standard in new construction. Electric beds also support integration of sensors, scales and exit alarms that are central to smart bed offerings. Procurement teams also weigh total cost of ownership, including energy use, maintenance and the availability of spare parts, when comparing electric platforms.
The fully electric beds are also going to experience the highest growth rates as the semi-electric and manually operated beds are replaced in care centers and households, as well as the declining cost of manufacturing making the electric beds affordable in emerging markets. The benefits from connectivity options, battery back-up, and interface make the electric beds more valuable, but the manually operated beds are still being used in less developed organizations. Manufacturers are now designing modulated beds that will permit upgrading of software and sensors without changing the bed frames.
By End User, Hospitals and Clinics Dominate Therapeutic Bed Market; Home Healthcare to Register Fastest Growth.
Hospitals and clinics dominate the Therapeutic Bed Market because they hold the largest installed base of beds and fund regular replacement through capital budgets and group purchasing contracts. They require certified, durable equipment backed by service agreements, and larger systems standardize on a few suppliers to simplify maintenance and staff training. New hospital projects, such as large public facilities announced in India, add further demand for beds. Clinics, rehabilitation centers and ambulatory facilities add further demand for treatment and examination beds.
Home healthcare is projected to register the fastest growth as payers and patients prefer recovery and long-term care at home, and as home hospital programs expand. Adjustable and pressure-relieving beds are supplied through home medical equipment providers, often on rental or reimbursed arrangements. Smaller, quieter and easier-to-assemble designs are being developed for residential settings, and remote monitoring features help caregivers manage patients who live far from clinics. Insurers in several countries now cover home hospital programs, which will gradually raise bed placements in private residences and support the rental market over the next decade.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
85.00 |
|
Europe |
Germany |
27.00 |
|
Asia Pacific |
Japan |
31.00 |
|
Latin America |
Brazil |
48.00 |
|
Middle East & Africa |
Saudi Arabia |
30.00 |
North America Therapeutic Bed Market Insights
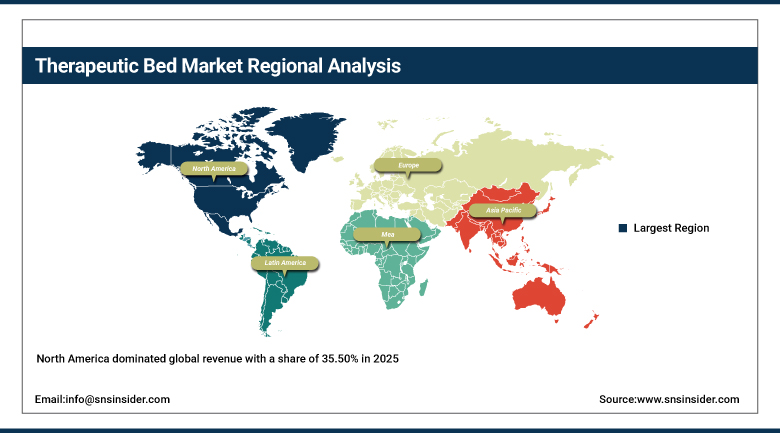
North America dominated global revenue with a share of 35.50% in 2025, supported by high hospital spending, an aging population, strong reimbursement for home beds and the presence of Stryker, Baxter, Invacare, Medline, Joerns Healthcare, Drive DeVilbiss and GF Health Products. The United States accounts for about 85.00% of regional demand, with Canada adding volume. Canada contributes through provincial hospital programs and a large long-term care sector, and Mexico adds demand from private hospital chains serving medical tourism.
Hospital quality programs targeting falls and pressure injuries encourage upgrades, and smart beds are gaining adoption. In January 2025, Stryker released an upgrade to its ProCuity bed series with fall prevention and real-time monitoring, and Hillrom launched an ICU bed with movement-recognition AI in September 2024. Capital budget limits and supplier consolidation moderate growth. Group purchasing organizations and integrated health systems negotiate fleet-wide contracts, and suppliers differentiate through connected features, service quality and financing options for health systems preparing to replace beds across many sites.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Therapeutic Bed Market Insights
Germany, the United Kingdom, France and Italy lead demand, supported by long-standing hospital systems and a rapidly aging population. The region is home to leading manufacturers such as Arjo, LINET Group, Stiegelmeyer, Getinge, Malvestio and Lojer, which supply both local hospitals and export markets. Nordic countries are known for early adoption of ergonomic and care-home innovations, and Eastern European countries are modernizing hospitals with support from regional funds, adding to unit demand.
Public procurement through tenders, strict medical device regulation and focus on ergonomics shape the market. In March 2024, Arjo introduced pressure injury prevention bed technology for European markets, targeting high-risk immobile patients. Long-term care for older adults is a central policy issue in many countries, supporting steady demand for beds in nursing homes and home care programs. Sustainability criteria are increasingly written into hospital tenders, and manufacturers respond with beds designed for repair, refurbishment and recycling, which can extend product life and appeal to public buyers.
Asia Pacific Therapeutic Bed Market Insights
Asia Pacific will be the leading region in terms of growth, expanding at a CAGR of 6.30% between 2026 and 2035. While Japan, home country of Paramount Bed, has an established market supported by the world's aging population, both China and India have growing markets owing to construction of new hospitals and increased demand for cost-effective electric beds. Demand comes from South Korea and Australia due to modern hospital facilities and aged care reforms, as well as Southeast Asia countries such as Indonesia, Thailand, and Vietnam due to construction of new hospitals.
Paramount Bed's new manufacturing plant in India achieved IGBC Gold rating in September 2025 as a result of investment in the manufacturing in local markets. Construction of large public hospitals, such as 1,000-bed hospital by RMLIMS in India in September 2024, increases demand. Cost-sensitive markets favor manual and semi-electric models, but the adoption of electric beds in tertiary hospitals is increasing. Low-cost electric beds by local manufactures in China and India are being exported to neighboring markets, thus creating competition for global brands and encouraging localization of production.
MEA & Latin America Therapeutic Bed Market Insights
In Latin America, Brazil leads on the strength of its large public and private hospital networks, followed by Mexico, Argentina and Colombia. Regional demand grows at about 4.90% annually, supported by hospital modernization and expanding private care. Public tenders and currency volatility influence purchases, and many beds are supplied through distributors. Chile, Colombia and Peru add demand through hospital upgrades and growing private insurance, while distributors provide financing and service to help hospitals with limited capital budgets obtain modern equipment.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates and South Africa lead through investment in new hospitals and healthcare infrastructure programs. Growth of about 5.30% annually is supported by expanding health insurance and medical city projects, though budget constraints and import dependence limit adoption of advanced beds in many African markets. Egypt, Turkey and Nigeria also build capacity as health authorities invest in new facilities, and local partnerships help international suppliers meet tender requirements, provide service and train hospital technicians across the region.
Market Dynamics
Growth Drivers: Aging Populations, Chronic Disease and Hospital Investment
Population aging is the main driver of the Therapeutic Bed Market. Older adults have higher rates of hospitalization, chronic conditions, mobility limits and pressure injury risk, increasing demand for hospital, long-term care and home beds. Rising prevalence of obesity and diabetes adds demand for bariatric and pressure-relieving models, while growth in surgical procedures supports acute care bed requirements. Growing awareness of the cost of falls to hospitals, which can reach tens of thousands of dollars per incident, strengthens the business case for smart beds. Rising rates of stroke and orthopedic surgery among older adults also increase the need for rehabilitation beds with positioning features.
Healthcare infrastructure investment in emerging markets and replacement of aging fleets in developed countries add further volume. Quality and safety programs that penalize patient falls and hospital-acquired pressure injuries encourage hospitals to buy smart beds with sensors and alarms, supporting higher average selling prices. Expanded public funding for long-term care in several countries adds a further source of demand for durable, easy-to-use beds. Public health campaigns on fall prevention and home safety are increasing awareness among families and caregivers.
Restraints: Capital Budget Limits, Long Replacement Cycles and Price Competition
Therapeutic beds are capital equipment with long useful lives, so hospitals can defer replacement when budgets are tight. Smart beds cost significantly more than basic models, and purchasing decisions often involve lengthy approval processes and group purchasing negotiations. Hospital operating margins in many countries are thin, so equipment budgets are among the first items to be postponed during financial stress, and replacement can be stretched beyond a decade. Variation in reimbursement rules across countries complicates product planning for global suppliers.
Price competition from regional manufacturers, especially in Asia, pressures margins on standard models, and supply chain disruptions raise input costs for steel, electronics and components. Regulatory compliance for medical electrical equipment also adds development cost. Tariffs, shipping delays and volatile steel prices can also increase manufacturing costs and complicate pricing commitments in long tender contracts. Imports of low-cost beds from Asia also pressure local pricing in several markets.
Opportunities: Smart Beds, Home Care and Emerging Markets
Smart beds integrating sensor capabilities, connectivity and analytics allow hospitals to minimize patient falls, track patients and increase staff productivity. Moreover, such developments give rise to a potential source of software and service revenues. The manufacturers also develop antimicrobial bed materials and modular designs extending the lifetime of beds. Bed integration with electronic health records and nurse call systems allows them to be incorporated into wider digital patient safety solutions, thus providing additional stickiness. The lease and rental arrangements decrease initial barriers for smaller facilities and attract new customers.
Home care and emerging markets provide volume growth prospects. Programs of rental and reimbursement of home beds provide better access, whereas hospital construction in Asia-Pacific, the Middle East and Africa generates demand for locally made beds. Manufacturers capable of establishing regional production and service network will benefit from these trends. Collaboration with home medical equipment suppliers and insurers accelerates placements, whereas after-sales services and bed refurbishment programs generate additional revenue sources minimizing dependence on new units.
Recent Developments:
- In September 2025, Paramount Bed's new Indian production facility received IGBC Gold certification. The facility supports local manufacturing of beds for the growing Indian healthcare market.
- In September 2024, Hillrom launched an ICU bed with AI that recognizes patient movement to reduce falls. The launch advances smart bed capability in critical care.
- In March 2024, Arjo introduced pressure injury prevention bed technology for European healthcare markets. The technology targets high-risk immobile patients.
- In February 2024, Lemi launched the ThermoSoft-V treatment bed, which combines vibroacoustic and heat therapy. The product extends the therapeutic bed category into physical therapy applications.
Therapeutic Bed Market Key Players are
- Stryker Corporation
- Baxter International Inc. (Hillrom)
- Arjo AB
- LINET Group SE
- Getinge AB
- Paramount Bed Holdings Co., Ltd.
- Invacare Corporation
- GF Health Products, Inc.
- Joerns Healthcare
- Medline Industries, LP
- Medical Depot, Inc. (Drive DeVilbiss Healthcare)
- Stiegelmeyer GmbH & Co. KG
- Amico Group of Companies
- Centrobed Ltd
- Hoffman NOA Medical Industries, LLC
- Span-America Medical Systems
- Malvestio S.p.A.
- Lojer Oy
- Savion Industries
- Gendron, Inc.
Therapeutic Bed Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.74 Billion |
| Market Size by 2035 | USD 7.50 Billion |
| CAGR | CAGR of 4.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Clinical and ICU Beds, Bariatric Beds, Specialty and Pressure-Relieving Beds, Household Beds, and Accessories) • By Application (Acute Care, Critical Care, and Long-Term Care) • By Technology (Fully Electric, Semi-Electric, and Manual) • By End User (Hospitals and Clinics, Home Healthcare, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Stryker Corporation; Baxter International Inc. (Hillrom); Arjo AB; LINET Group SE; Getinge AB; Paramount Bed Holdings Co., Ltd.; Invacare Corporation; GF Health Products, Inc.; Joerns Healthcare; Medline Industries, LP; Medical Depot, Inc. (Drive DeVilbiss Healthcare); Stiegelmeyer GmbH & Co. KG; Amico Group of Companies; Centrobed Ltd; Hoffman NOA Medical Industries, LLC; Span-America Medical Systems; Malvestio S.p.A.; Lojer Oy; Savion Industries; Gendron, Inc. |

Frequently Asked Questions
Key players include Stryker Corporation, Baxter International Inc. (Hillrom), Arjo AB, LINET Group SE, Getinge AB, Paramount Bed Holdings Co., Ltd., Invacare Corporation and Medline Industries, LP.
Key opportunities include smart beds with sensors and analytics, home care placements, and hospital construction in Asia Pacific and other emerging regions.
The major growth factor is population aging, which increases hospitalization, chronic disease and pressure injury risk and therefore demand for therapeutic beds.
By Product Type, the Clinical and ICU Beds segment dominated the market in 2025 with a 58.40% share, supported by hospital fleet replacement and critical care capacity.
North America dominated the market with a share of 35.50% in 2025, driven by hospital spending, an aging population and reimbursement for home beds.
