
5G in Defense Market Report Scope & Overview:
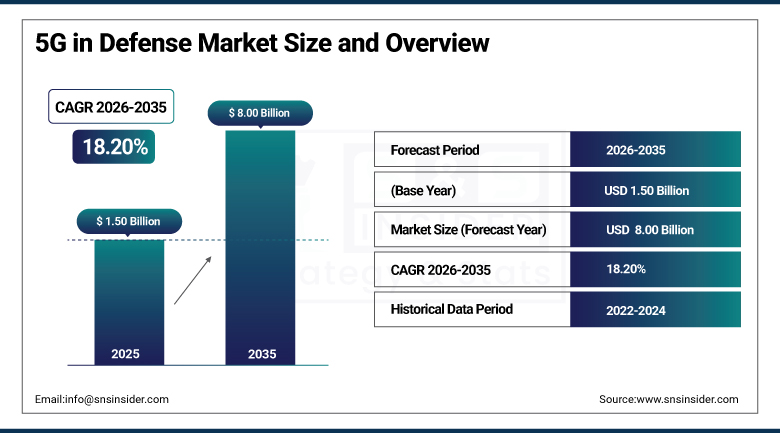
The 5G in Defense Market was valued at USD 1.50 Billion in 2025 and is expected to reach USD 8.00 Billion by 2035, growing at a CAGR of 18.20% from 2026-2035.
The 5G in Defense Market growth is being driven primarily by militaries around the world shifting toward digital, connected, and data-driven warfare systems that depend on high-bandwidth, low-latency wireless networks to link sensors, vehicles, and command centers in near real time. Growing needs for battlefield communication, connected sensors, unmanned ground and aerial systems, and fast data transmission continue to push defense agencies toward private 5G networks purpose-built for military installations rather than relying on commercial carrier infrastructure. Rising defense modernization initiatives across major military powers, combined with growing private-sector investment in 5G network technology, continue to widen the range of applications, from base-area connectivity to battlefield edge computing, where 5G is displacing legacy tactical communication systems.
The U.S. Department of Defense released a new private 5G deployment strategy in October 2024, signed by acting DoD Chief Information Officer Leslie Beavers, calling for accelerated deployment of DoD-only 5G networks across roughly 800 military bases and operating locations worldwide.
To Get more information On 5G in Defense Market - Request Free Sample Report
5G in Defense Market Trends:
-
Rising deployment of private 5G networks across military installations replacing commercial carrier dependency.
-
Growing adoption of open radio access network technology enabling multi-vendor military wireless infrastructure.
-
Expanding use of 5G-enabled autonomous and unmanned systems across land, naval, and airborne military platforms.
-
Increasing government investment in network functions virtualization improving military network responsiveness and flexibility.
-
Growing homeland security agency adoption of 5G technology supporting border surveillance and critical infrastructure protection.
-
Rising development of open-source software architecture reducing military dependency on a small number of commercial vendors.
U.S. 5G in Defense Market Outlook:
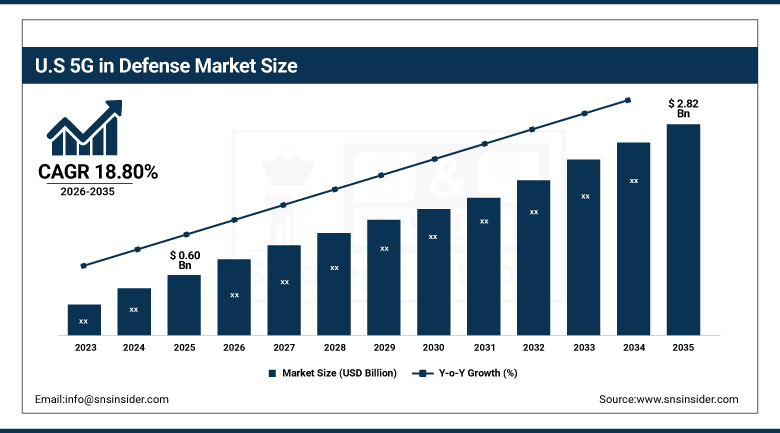
The U.S. 5G in Defense Market was valued at USD 0.60 Billion in 2025 and is expected to reach USD 2.82 Billion by 2035, growing at a CAGR of 18.80% from 2026-2035.
The U.S. 5G in Defense Market growth continues to be reinforced by sustained Department of Defense investment in private wireless networks across its roughly 800 domestic and overseas military installations, supported by the Pentagon's Joint All-Domain Command and Control initiative aimed at connecting sensors across every military service into a single unified network. Continued congressional funding tied to national defense authorization legislation, combined with the DoD's FutureG office actively testing next-generation wireless capabilities, continues to reinforce sustained domestic demand across base connectivity, tactical communication, and edge computing applications.
Hughes Network Systems received a $6.5 million contract in November 2024 to develop an Open Radio Access Network prototype at Fort Bliss, Texas, installing 5G O-RAN equipment that will operate a temporary evaluation network before eventually transitioning to the company's commercial network supporting both Pentagon and surrounding commercial customers.
5G in Defense Market Segment Analysis:
-
By Communication Infrastructure, the Small Cell segment dominated the 5G in Defense Market with approximately 62.40% share in 2025, while the Macro Cell segment is the fastest growing with a CAGR of approximately 19.80%.
-
By Core Network Technology, the SDN segment dominated the 5G in Defense Market with approximately 35.00% share in 2025, while the Mobile Edge Computing segment is the fastest growing with a CAGR of approximately 24.80%.
-
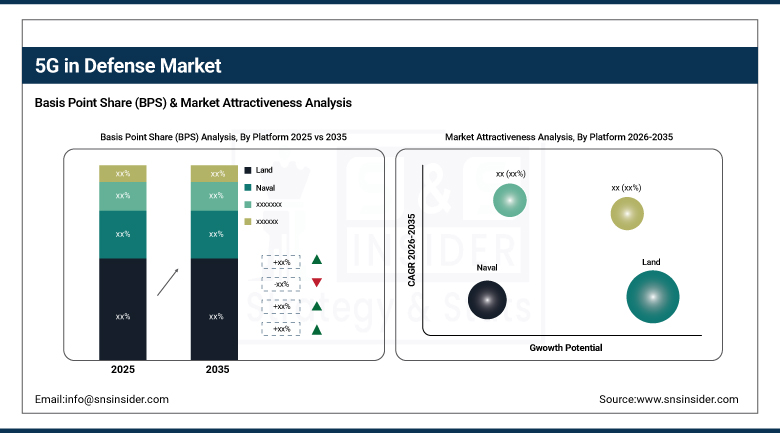
By Platform, the Land segment dominated the 5G in Defense Market with approximately 48.60% share in 2025, while the Airborne segment is the fastest growing with a CAGR of approximately 22.50%.
-
By End Use, the Military segment dominated the 5G in Defense Market with approximately 78.40% share in 2025, while the Homeland Security Agencies segment is the fastest growing with a CAGR of approximately 24.50%.
By Communication Infrastructure, Small Cell Dominates the 5G in Defense Market and Macro Cell Grows Fastest
Small Cell Infrastructure will continue to dominate the communication infrastructure segment through deployment in military bases, command centers, and training sites in order to create 5G coverage that is small in size, energy-efficient, and capable of high capacity in tactical situations where large macro towers cannot be used. Private 5G and edge computing use cases in military contexts will continue to fuel consistent demand for this segment. The companies that are able to establish themselves in this market segment through investments in early adoption of macro cells infrastructure validated for defense purposes will benefit from rising demand for border and perimeter surveillance.
Macro Cells Infrastructure is the fastest-growing segment due to the increasing requirement for area-wide coverage between remote sites, training sites, and border areas where small cell density would not be sufficient for creating enough coverage. The growing requirement for connected sensor networks in large geographic territories fuels its above average growth rate.
By Core Network Technology, SDN Dominates the 5G in Defense Market and Mobile Edge Computing Grows Fastest
Software-defined networking remains the leading core network technology sub-segment due to its value in making military network systems more adaptive and responsive through centralized and programmable control systems rather than hardwired and fixed routing between distributed sites. Vendors offering edge computing hardware customized for battlefield use are well-positioned to earn higher margins as the demand for computing processes independent of data center connections increases from the military side.
The mobile edge computing sub-segment is expected to see the fastest growth rate among core network technology sub-segments, owing to the increasing need for the processing of battlefield analytics and autonomous operations near to where the data is being collected rather than sending it back to far-off data centers.
By Platform, Land Dominates the 5G in Defense Market and Airborne Grows Fastest Growing
Land-based platforms remain dominant in the platform market due to increased deployment of 5G networks in military bases, vehicles, control centers, surveillance systems, and unmanned ground systems that require secure battlefield communication. With further development in technology and network connectivity through 5G, airborne platforms, such as drones and unmanned aerial vehicles, will increase efficient and accurate communication in contested electromagnetic environment.
Airborne platforms stand out as the fastest growing platform due to communication range and controlled autonomous operation of vehicles. Network connectivity among various vehicles, planes, and ships will continue to influence military communication technology trends in the future.
By End Use, Military Dominates the 5G in Defense Market and Homeland Security Agencies Grows Fastest
Military application has continued to dominate the end use industry due to the nature of defense organizations being the main institutional buyers of the 5G infrastructure of the private companies and due to the massive amount of facilities, vehicles, and manpower which need communication connections within each branch of the army. Border Security and Critical Infrastructure Protection agencies have been looking at 5G communications and surveillance systems as complementary security measure.
Homeland security agencies have been the fastest growing end use industry as the domestic security agencies have increasingly opted for the 5G technology beyond their military applications.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
92.61% |
|
Europe |
Germany |
24.60% |
|
Asia Pacific |
China |
39.80% |
|
Latin America |
Brazil |
27.20% |
|
Middle East & Africa |
Israel |
31.40% |
North America 5G in Defense Market Insights
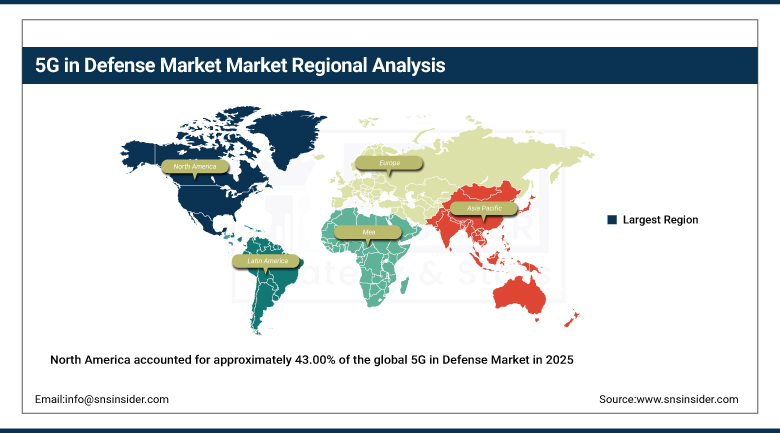
North America accounted for approximately 43.00% of the global 5G in Defense Market in 2025, making it the largest regional market, led primarily by the United States, which alone contributed over 92.61% of regional share. Strong U.S. defense modernization initiatives and early 5G integration programs across roughly 800 military bases continue to reinforce this leading position. Continued congressional appropriations supporting Joint All-Domain Command and Control initiatives further reinforce North America's leading position, as the Pentagon works to connect every military service into a single unified network.
Canada contributes additional regional demand through its participation in North American defense procurement and joint military modernization initiatives. Continued Department of Defense investment in private 5G networks and FutureG testing programs further reinforces North America's leading position.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific 5G in Defense Market Insights
The Asia Pacific segment is expected to grow at the highest CAGR in the 5G in Defense Market from 2026-2035, driven by growing defense modernization projects in China, India, Japan, and South Korea. Increasing military digital transformation and advancements in border surveillance systems are fueling growth in the region, which comprises of the largest defense spenders. Growing government investment in research funding in the region is further fast-tracking the deployment process for 5G defense systems domestically.
China plays a vital role in the Asia Pacific market, owing to huge investments in military 5G infrastructure. India and South Korea make up for other demand drivers within the region due to increased 5G ecosystem development and rising budgets for defense modernization.
Europe 5G in Defense Market Insights
Europe is another substantial regional market for 5G in defense, owing to the strong defense modernization programs and digital infrastructure development in NATO-member countries in response to increased security challenges within the region. Germany plays an important role in regional demand, owing to its existing defense industry capabilities and high level of integration with NATO. The standardization process related to the interoperability of 5G defense infrastructure in NATO countries is slowly making it easier to share technology between countries and developing the European market.
Another country driving regional demand is the UK and France due to increasing investments in 5G defense infrastructure and the interoperability standardization process in NATO.
MEA & Latin America 5G in Defense Market Insights
The Middle East and Africa region reflects growing strategic importance, with Israel accounting for the largest regional contribution through its established defense technology ecosystem and deep experience integrating advanced communication systems across contested border regions. Gulf Cooperation Council markets contribute additional regional demand through growing investment in critical infrastructure protection and military communication modernization tied to broader security programs.
Latin America remains a smaller contributor to global demand, with Brazil accounting for the majority of regional interest on the strength of its growing domestic defense industrial base. Gradual expansion of regional defense budgets continues to support steady market development.
Market Dynamics:
Growth Drivers: Digital Warfare Systems and Network Modernization
Militaries worldwide shifting toward digital, connected, and data-driven warfare systems represent the principal driver of market growth, as defense agencies increasingly depend on high-bandwidth, low-latency wireless networks to link sensors, vehicles, and command centers in near real time. Rising private-sector investment in 5G network technology further reinforces this underlying demand trend, as commercial telecommunications advances increasingly find dual-use application across military communication systems.
Rising defense modernization initiatives across major military powers provide an additional significant source of growth, as governments continue funding private 5G network deployment to replace legacy tactical communication systems. Growing private-sector investment in 5G technology further reinforces this underlying demand trend.
Restraints: Security Concerns and Integration Complexity
Security issues with regards to the vulnerabilities of the wireless network infrastructure are one such barrier, considering that security agencies need to weigh the benefits of 5G technology against the inherent cyber-security threats associated with wireless technology infrastructure. Making the 5G infrastructure compatible with the decades-old infrastructure of military tactical radio and satellite systems will require considerable efforts on the part of engineering.
Complexity of integrating 5G technology with the existing military communication systems is another barrier since compatibility with new 5G infrastructure and decades-old tactical radio and satellite systems will take considerable efforts from the engineering perspective.
Opportunities: Open RAN Architecture and Edge Computing Expansion
Continued development of open radio access network architecture presents a substantial growth opportunity, as the Pentagon's push toward multi-vendor, open-source 5G infrastructure reduces dependency on a small number of proprietary suppliers and opens the market to a broader competitive base. Suppliers developing dedicated engineering capability specifically for homeland security applications are positioned to capture meaningful contract volume as domestic security agencies increasingly adopt military-grade communication technology.
Mobile edge computing expansion represents a further opportunity, as suppliers developing low-latency processing capability suited to battlefield analytics and autonomous operations are positioned to capture meaningful new demand as military digital transformation continues accelerating.
Recent Developments:
-
In September 2026, Orange acquired Dome technology from Obvios, strengthening its private 5G portfolio for defense and critical infrastructure. The cloud-native platform enables secure, sovereign private networks for military bases, tactical deployments, drones, autonomous systems, and surveillance applications.
-
In June 2026, Nokia Defense and KNDS announced a collaboration to provide 5G connectivity for soldiers and unmanned systems. The companies integrated Nokia’s Banshee Deployable Solution with the KNDS VBCI armored infantry fighting vehicle to extend high-bandwidth connectivity beyond the vehicle.
-
In May 2026, Nokia Federal Solutions and Lockheed Martin launched a modular 5G solution for U.S. and allied defense forces. The system integrates Nokia’s carrier-grade 5G into the U.S. Department of War’s CMOSS open-architecture framework for secure communications across military vehicles and platforms.
-
In July 2026, AT&T and Ericsson demonstrated 5G-based drone detection using network sensing technology. The trial used Ericsson Massive MIMO radios and AI-enabled signal processing to detect, locate, and track multiple drones, demonstrating a potential defense and security application for existing 5G infrastructure.
5G in Defense Market Key Players:
-
Huawei Technologies Co., Ltd.
-
L3Harris Technologies, Inc.
-
Nokia Corporation
-
Ericsson AB
-
Samsung Electronics Co., Ltd.
-
AT&T Inc.
-
Verizon Communications Inc.
-
Lockheed Martin Corporation
-
Northrop Grumman Corporation
-
General Dynamics Corporation
-
RTX Corporation
-
BAE Systems plc
-
Booz Allen Hamilton Inc.
-
Thales Group
-
Airbus SE
-
Qualcomm Incorporated
-
Cisco Systems, Inc.
-
Mavenir Systems, Inc.
-
Federated Wireless, Inc.
-
Hughes Network Systems, LLC
5G in Defense Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.50 Billion |
| Market Size by 2035 | USD 8.00 Billion |
| CAGR | CAGR of 18.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Communication Infrastructure (Small Cell, Macro Cell) • by Core Network Technology (SDN, NFV, Mobile Edge Computing) • by Platform (Land, Naval, Airborne) • by Chipset Type (ASIC, Millimeter Wave, RFIC) • by End Use (Military, Homeland Security Agencies) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Huawei Technologies Co., Ltd., L3Harris Technologies, Inc., Nokia Corporation, Ericsson AB, Samsung Electronics Co., Ltd., AT&T Inc., Verizon Communications Inc., Lockheed Martin Corporation, Northrop Grumman Corporation, General Dynamics Corporation, RTX Corporation, BAE Systems plc, Booz Allen Hamilton Inc., Thales Group, Airbus SE, Qualcomm Incorporated, Cisco Systems, Inc., Mavenir Systems, Inc., Federated Wireless, Inc., Hughes Network Systems, LLC |

Frequently Asked Questions
Key players include Huawei Technologies Co., Ltd., L3Harris Technologies, Inc., Nokia Corporation, Ericsson AB, and Lockheed Martin Corporation, among other leading defense and telecommunications companies.
Continued development of open radio access network architecture and mobile edge computing expansion represent the primary opportunities.
Growth is primarily driven by militaries worldwide shifting toward digital, connected, and data-driven warfare systems combined with rising defense modernization initiatives.
By Communication Infrastructure, Small Cell dominated the market with approximately 62.40% share in 2025, driven by deployment across military bases and command centers.
North America dominated the market with approximately 43.00% share in 2025, led primarily by the United States, which contributed over 92.61% of regional share.
