
5G In Healthcare Market Report Scope & Overview:
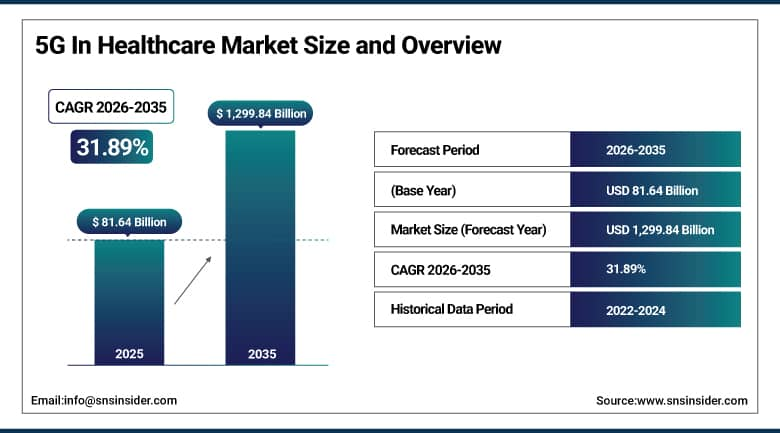
The 5G In Healthcare Market was valued at USD 81.64 Billion in 2025 and is expected to reach USD 1,299.84 Billion by 2035, growing at a CAGR of 31.89% from 2026-2035.
The 5G In Healthcare Market is expanding as hospitals, clinics and emergency services use fast, low-latency wireless networks to connect devices, clinicians and patients. Remote patient monitoring, connected medical devices, telemedicine, ambulance links and robot-assisted procedures all benefit from higher bandwidth and reliable response times. Hospitals are testing private 5G networks and network slicing to give critical applications guaranteed capacity. Hardware leads spending today because sensors, routers, gateways and 5G-enabled devices form the base of every deployment. Services are growing quickly as providers need design, integration and managed network support. North America leads adoption, while Asia Pacific is expected to grow fastest as telecom operators and hospitals launch large pilots.
⮞In February 2025, Boldyn Networks and Nokia launched what they describe as Europe's first private 5G standalone network in a working hospital, at Oulu University Hospital in Finland. The network shows how hospitals are starting to run dedicated wireless infrastructure for clinical use.
To Get More Information On 5G In Healthcare Market - Request Free Sample Report
5G In Healthcare Market Trends
-
Deployment of private 5G standalone networks and neutral-host systems inside hospitals
-
Use of network slicing to reserve capacity for telesurgery, ambulance links and imaging
-
Growth of 5G-enabled wearables, mobile computers and remote monitoring gateways
-
Cross-border and long-distance remote surgery trials supported by low-latency links
-
Public funding and telecom partnerships for smart hospital projects in Europe and Asia
U.S. 5G In Healthcare Market Outlook
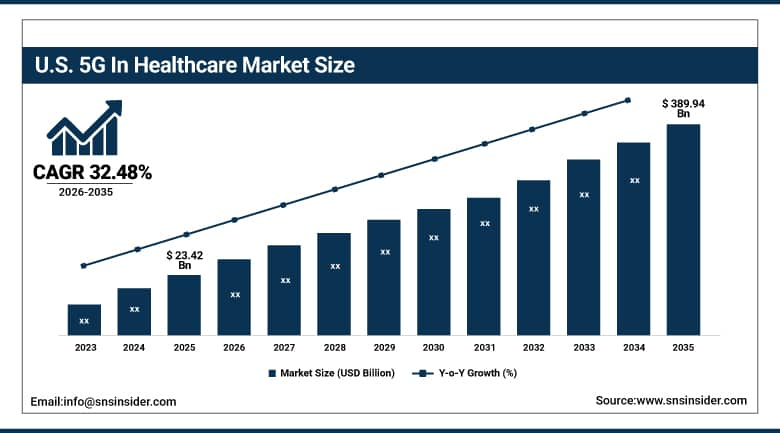
The U.S. 5G In Healthcare Market was valued at USD 23.42 Billion in 2025 and is expected to reach USD 389.94 Billion by 2035, growing at a CAGR of 32.48% from 2026-2035.
The U.S. 5G In Healthcare Market is the largest national market for connected care, supported by large health systems, strong telecom operators and active private network programs. Hospitals are replacing aging in-building antenna systems with combined neutral-host and private 5G networks that serve patients, staff and medical devices. Academic medical centers and children's hospitals are testing 5G for imaging transfer, asset tracking and wearable sensors. Telehealth programs and rural connectivity funding add demand beyond hospital campuses. Shared spectrum rules allow health systems to build their own networks, and carriers offer managed services for those that prefer to buy connectivity. Demand is expected to rise as hospitals link more devices and clinical workflows to wireless networks.
⮞For instance, in October 2025 Verizon announced that AdventHealth and Tampa General Hospital use its combined neutral-host and private 5G networks. Tampa General replaced an outdated distributed antenna system and has a private 5G core ready for a new tower.
5G In Healthcare Market Segment Analysis
-
By Component, the Hardware segment dominated the 5G In Healthcare Market with approximately 62.11% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 35.16%.
-
By Application, the Remote Patient Monitoring segment dominated the 5G In Healthcare Market with approximately 64.66% share in 2025, while the Connected Medical Devices segment is the fastest growing with a CAGR of approximately 38.16%.
-
By Communication Type, the Enhanced Mobile Broadband segment dominated the 5G In Healthcare Market with approximately 51.85% share in 2025, while the Ultra-Reliable Low-Latency Communication segment is the fastest growing with a CAGR of approximately 34.27%.
-
By End User, the Healthcare Providers segment dominated the 5G In Healthcare Market with approximately 49.83% share in 2025, while the Payers segment is the fastest growing with a CAGR of approximately 34.97%.
By Component, Hardware Dominates the 5G In Healthcare Market and Services Grows Fastest
Hardware leads because every 5G healthcare deployment needs physical equipment, including radio units, small cells, core network appliances, routers, gateways, sensors, wearables and 5G-enabled clinical computers. Hospitals buy these items during network build-outs and device refresh cycles, and medical equipment makers are adding 5G modems to bedside monitors, imaging carts and ambulance devices. Large capital projects, such as new hospital campuses and smart hospital programs, place bulk orders for radios and edge hardware. Few services can be delivered without this physical layer, which keeps hardware as the largest spending category. Hospitals also tend to buy radios from the same supplier that provides the core network, which keeps equipment purchases tied to long-term vendor relationships.
Services are growing fastest because most hospitals lack the staff to plan, install and run a wireless network. Operators and integrators provide radio design, spectrum advice, security setup, device onboarding and round-the-clock management, often under multi-year contracts. Network slicing and private network models turn connectivity into a managed service with guaranteed performance. As the number of connected devices rises, providers also buy training, monitoring and application integration, which lifts service revenue faster than equipment sales. Operators also report that managed packages bundle devices, coverage and support under one contract, which simplifies purchasing for hospital information teams.
⮞In January 2026, Ericsson, Bouygues Telecom Business and Bordeaux University Hospital announced the 5MART HO5PITAL project. A 5G standalone network with slicing will cover 18 hospital buildings from the second half of 2026.
By Application, Remote Patient Monitoring Dominates the 5G In Healthcare Market and Connected Medical Devices Grows Fastest
Remote patient monitoring leads because it is the most widely used way to turn wireless connectivity into daily care. Wearable sensors, patch monitors and home devices send vital signs to clinicians in near real time, and hospitals use them to follow chronic patients and recently discharged patients. Higher bandwidth and many simultaneous connections let large patient groups be monitored at once, which supports hospital-at-home programs. Providers also see clear savings from fewer readmissions and shorter stays, which makes this application the easiest to fund. Wearable makers are also launching products with built-in cellular links that work without a phone, which improves monitoring in older or less technical patients.
Connected medical devices are growing fastest as infusion pumps, ventilators, imaging systems, surgical robots and ambulance equipment gain 5G connections. Wireless links remove cables, let devices move freely and allow remote experts to view data and control equipment. Low latency supports real-time imaging transfer and remote operation, while edge computing processes large data files near the device. Manufacturers are building 5G into new product lines, and hospitals are replacing older Wi-Fi-dependent devices to gain better reliability and security. Hospitals also use these devices to extend monitoring into the home, which raises the number of units in service per patient program.
⮞In April 2025, MicroPort MedBot reported that its Toumai surgical robot performed five simultaneous telesurgeries over 5G from Ruijin Hospital in Shanghai, with patients up to about 3,000 km away. The trial shows the reach of connected surgical devices.
By Communication Type, Enhanced Mobile Broadband Dominates the 5G In Healthcare Market and Ultra-Reliable Low-Latency Communication Grows Fastest
Enhanced mobile broadband leads because most current healthcare uses need high data rates more than ultra-short response times. Video consultations, high-resolution imaging files, electronic record access, augmented reality guidance and live ambulance video all rely on high throughput. Operators first launched this service type, and it is widely available on public networks, which allows hospitals to start without building private infrastructure. Broadband coverage inside hospitals also supports staff mobile devices, which further raises its share of use. Hospitals in several countries now test these networks first in emergency and surgical areas where fast data matters most.
Ultra-reliable low-latency communication is growing fastest because it enables the most demanding and high-value uses, including remote surgery, robot control and critical alerts. Response times of a few milliseconds and very high reliability let specialists operate or guide procedures from distant locations. Standalone 5G networks and network slicing make these guarantees possible, and hospitals are running trials that move such services into routine care. Wider availability of standalone core networks will expand this segment as regulators approve more remote procedures. Operators are also working with regulators to agree standards for remote procedures, which will help move trials into regular clinical use over the forecast period.
⮞In May 2026, a surgeon at Tongji Hospital in Wuhan operated remotely on a patient in Hyderabad, India, about 3,000 km away, with 5G carrying instructions in under 200 milliseconds. The case shows the potential of low-latency links.
By End User, Healthcare Providers Dominates the 5G In Healthcare Market and Payers Grows Fastest
Healthcare providers lead because hospitals, clinics, ambulance services and research centers own the facilities and devices that need connectivity. They invest in private networks, device connections, telemedicine systems and remote monitoring programs, and they hold the capital budgets for wireless upgrades. Large health systems are also building smart hospital programs that link imaging, location tracking, staff communication and patient devices. As clinical teams see benefits in speed and reliability, they extend wireless coverage from emergency departments to operating rooms and wards. Research institutes and emergency services add further demand for dependable mobile links.
Payers are growing fastest because insurers and health plans are funding remote monitoring, virtual care and home-based programs that depend on mobile connectivity. These programs aim to lower hospital costs by detecting problems early and keeping patients at home. Payers are partnering with device makers and operators to supply connected devices to members with chronic conditions, and they use the resulting data for risk scoring and care management. Policy support for telehealth coverage adds further momentum. Employers and public health programs are also funding connected devices for staff and citizens, which widens the customer base.
⮞By March 2026, the National University Health System in Singapore had carried out 180 mixed reality assisted surgeries on its 5G network, with operating times reduced by 10% to 30%. The results show measurable clinical value for hospital users.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
78.63 |
|
Europe |
Germany |
25.86 |
|
Asia Pacific |
China |
42.15 |
|
Latin America |
Brazil |
47.81 |
|
Middle East & Africa |
Saudi Arabia |
28.37 |
North America 5G In Healthcare Market Insights
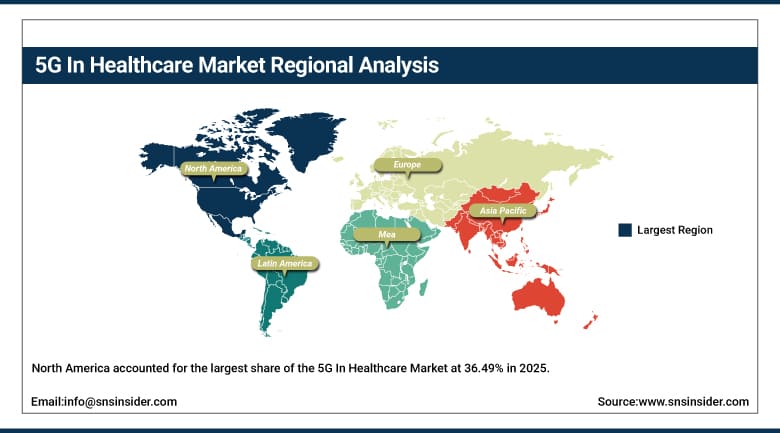
North America accounted for the largest share of the 5G In Healthcare Market at 36.49% in 2025, led by the United States and supported by Canada. Large health systems, strong telecom operators and active spending on digital health create a favorable base. Shared spectrum options allow hospitals to build private networks, and carriers offer neutral-host and managed services that cover whole campuses. Academic medical centers and children's hospitals are early users, testing 5G for imaging transfer, asset tracking and wearable sensors.
Telehealth programs and rural connectivity funding extend demand beyond hospital campuses. Federal policy on rural health care connectivity is under review, and regulators are asking what capacity, latency and security providers need. Canada is investing in virtual care for remote communities, and Mexico is a growing market for private hospital groups. Cybersecurity, privacy rules and the cost of upgrading older buildings remain important factors in purchasing decisions. Many health systems are also pairing 5G with Wi-Fi to cover different device types at lower cost.
⮞In August 2026, the U.S. Federal Communications Commission adopted a proposal on promoting telehealth in rural America. The proposal asks what capacity, latency and security health care providers need from their connections.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific 5G In Healthcare Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 36.23% during 2026-2035. China leads in 5G network coverage and telesurgery trials, while Japan, South Korea, India, Singapore and Australia run smart hospital and remote care programs. Telecom operators and equipment makers work closely with leading hospitals to test new uses, and public funding supports large pilots. Leading medical universities in China and Japan are also publishing trial results that help build clinician confidence in remote procedures. Strong government backing for digital health in several countries also gives hospitals confidence to commit to long projects.
India is expanding 5G-enabled ambulances and clinics to reach rural populations, and Singapore is combining 5G with mixed reality and hospital-at-home services. Large patient populations, a shortage of specialists outside major cities and strong manufacturing of medical devices all support growth. Uneven network coverage in rural areas and different regulatory rules across countries remain obstacles to wider rollout of advanced services. Telecom operators are offering bundled connectivity and device packages to hospitals, which lowers the effort needed to start new programs.
⮞In October 2025, RED Health and Medanta Indore launched a 5G-enabled advanced life support ambulance in India. The vehicle sends patient vital signs to the emergency room with under 2 seconds of latency.
Europe 5G In Healthcare Market Insights
Europe is a leading region for private 5G standalone projects in hospitals, led by Germany, France, Finland, Sweden, the United Kingdom and Greece. European Union funding programs support smart hospital pilots, and national operators work with equipment vendors and universities. Hospitals test 5G for ambulance video, drone delivery of defibrillators, indoor equipment tracking and robot-assisted care. Cities such as Bordeaux, Oulu, Stockholm and Athens now host dedicated hospital networks that serve as reference sites for other providers, which helps spread best practice across the region and speeds up purchasing decisions.
Regulation on data protection and medical device approval shapes how new services are introduced. Public procurement and cross-border funding encourage standards-based networks, and collaboration between operators and hospitals is common. Fragmented health systems, differing national rules and slow approval processes are challenges, but long-term programs running to 2027 and beyond are giving suppliers visibility on demand. Health ministries are also publishing digital health strategies that name connectivity as a priority, which gives suppliers confidence to invest in local teams. Several countries are also drafting guidance for remote procedures.
⮞In October 2026, the 5GMHI project run by Telia and Region Stockholm was reported to be testing drone defibrillator delivery, ambulance video and indoor equipment tracking at Södersjukhuset on 5G standalone.
MEA & Latin America 5G In Healthcare Market Insights
In Latin America, Brazil and Mexico lead interest in 5G for healthcare, supported by operator spectrum auctions and private hospital groups. Most activity is at the pilot stage, and spending is limited by network coverage outside major cities and by funding. Regulators are opening spectrum for private networks, which creates room for hospital and industrial use. Telecom operators are also partnering with hospital groups on trials, which gives vendors reference sites and builds interest among other providers in the region.
In October 2026, Chile's telecoms regulator Subtel extended the 2,300 MHz band to 2,360 MHz, adding 60 MHz for private and industrial 5G networks. The step supports future private network use in sectors such as health.
In the Middle East and Africa, the United Arab Emirates, Saudi Arabia and Qatar lead demand through national digital health programs and demonstrations of remote surgery, ambulance links and smart hospital designs. Gulf operators work with equipment vendors to showcase network slicing for medical use, while much of Africa depends on mobile networks with limited 5G coverage. Affordability and device availability slow broad adoption, but new hospital projects are creating opportunities. Medical tourism hubs in the Gulf also draw investment in advanced connected operating rooms and ambulance fleets.
⮞In October 2025, e& demonstrated a surgical robot running over a private network slice reserved for the procedure, together with an AI ambulance setup, at GITEX in Dubai.
Market Dynamics
Growth Drivers: Low-Latency Networks, Remote Care Programs and Smart Hospital Funding Drive Growth in the 5G In Healthcare Market
Network performance is the core driver. 5G offers high speed, many simultaneous connections and low latency that earlier networks could not provide for clinical use, and standalone networks with slicing reserve capacity for critical applications. Hospitals gain reliable coverage for staff devices, imaging transfer, location tracking and connected equipment. Remote consultations and ambulance video help specialists support patients far from major centers, which extends care to rural and underserved areas. Telecom vendors are also bundling healthcare solutions with network equipment, which lowers the effort hospitals need to start a project and speeds up the rollout of pilots.
Funding and policy are adding momentum. Governments and regional bodies finance smart hospital projects, rural connectivity and digital health programs, and telecom operators invest in healthcare as a vertical with high-value customers. Growth of chronic disease and ageing populations increases demand for remote monitoring, while device makers add 5G modems to new equipment. Shortages of specialists also push health systems to adopt remote and robot-assisted procedures. Clinical evidence from remote surgery and monitoring trials also builds confidence among regulators and hospital leaders.
⮞In November 2025, the Bordeaux university hospital smart-hospital project won a Connecting Europe Facility call. The award shows how public funding supports 5G healthcare deployments.
Restraints: Deployment Cost, Coverage Gaps and Security Concerns Restrain Growth in the 5G In Healthcare Market
Deployment costs limit adoption, especially for small and public hospitals. Radio units, core networks, edge computing and integration work require capital that competes with clinical equipment, and the return on investment is hard to prove for early projects. Building walls, shielding in imaging rooms and the need to cover large campuses make indoor design complex. Many hospitals also depend on existing Wi-Fi systems that work well enough for current needs. Hospitals also compare 5G with fiber and Wi-Fi upgrades that cost less, which can delay commitment to wireless projects until benefits are clearer.
Security, regulation and skills add further barriers. Connected medical devices raise cybersecurity and privacy risks, and rules on patient data differ across countries. Remote procedures face questions on liability, licensing and approval, and clinicians need training to trust wireless links. Uneven 5G coverage in rural areas also limits the very services that could benefit most, and adoption is still early in many regions. Fragmented standards across device makers also complicate integration and extend project timelines for many providers. Hospitals also need clear reimbursement rules before they invest in network-dependent services.
⮞In December 2025, a survey of 50 hospitals across seven Asia-Pacific markets found that only 25% were implementing 5G. The result shows how far adoption still has to travel.
Opportunities: Private Networks, Remote Surgery and 5G-Enabled Devices Create Opportunities in the 5G In Healthcare Market
Private networks and network slicing open recurring service opportunities for operators, integrators and equipment makers. Hospitals that want guaranteed performance for imaging, robots and critical alerts can buy dedicated capacity, and managed models spread cost over several years. Neutral-host systems that serve patients, staff and devices on one infrastructure create value for hospitals that must replace older antenna systems. Hospitals that adopt private networks can also reuse the infrastructure for staff communication, building management and research programs, which increases the return on each deployment. Operators also see healthcare as a way to move beyond consumer connectivity into higher-value enterprise services, which encourages investment in dedicated teams.
Remote surgery, ambulance connectivity and 5G-enabled devices create higher-value uses. Specialist expertise can be shared across regions, ambulance crews can send video and vital signs ahead of arrival, and device makers can sell connected products with subscription services. Hospital-at-home programs and rural clinics add further demand for wireless gateways, wearables and virtual care platforms that rely on dependable mobile networks. Telecom firms can also package devices and connectivity for payers, which opens a new route to patients at home and builds recurring subscription income for providers.
⮞In January 2024, Proximus began a private 5G pilot at AZ Groeninge Hospital in Kortrijk, Belgium. Planned uses include robotic surgery, biosensor monitoring and augmented reality imaging.
Recent Developments:
-
In March 2025, Zebra Technologies announced that its HC25 and HC55 healthcare mobile computers now feature 5G connectivity. The devices are designed for clinical staff in hospitals.
-
In March 2025, Kajeet showed its Healthcare 5G managed service at HIMSS25. The service offers private 5G and neutral-host in-building coverage for hospitals, built on Cisco's private 5G platform.
-
In March 2025, Airtel Business announced 5G-powered Smart Clinics with Fortis Healthcare. The clinics cover real-time consultations, connected point-of-care diagnostics and live health tracking.
-
In July 2026, COSMOTE TELEKOM announced a private 5G standalone network at Aretaieio University Hospital in Athens. The network covers operating rooms, the education center, and radiology and radiotherapy departments.
5G In Healthcare Market Key Players
-
Telefonaktiebolaget LM Ericsson
-
Nokia Corporation
-
Huawei Technologies Co., Ltd.
-
ZTE Corporation
-
Cisco Systems, Inc.
-
Celona, Inc.
-
Zebra Technologies Corporation
-
MicroPort MedBot (Group) Co., Ltd.
-
Boldyn Networks
-
Verizon Communications Inc.
-
AT&T Inc.
-
T-Mobile US, Inc.
-
Telia Company AB
-
Bouygues Telecom
-
Proximus NXT
-
COSMOTE TELEKOM (OTE Group)
-
Singapore Telecommunications Limited (Singtel)
-
Bharti Airtel Limited (Airtel Business)
-
NTT DATA
-
Kajeet
5G In Healthcare Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 81.64 Billion |
| Market Size by 2035 | USD 1,299.84 Billion |
| CAGR | CAGR of 31.89% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Hardware, Services, and Software) • By Application (Remote Patient Monitoring, Connected Medical Devices, Telemedicine and Virtual Consultation, and Others) • By Communication Type (Enhanced Mobile Broadband, Ultra-Reliable Low-Latency Communication, and Massive Machine-Type Communication) • By End User (Healthcare Providers, Payers, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Telefonaktiebolaget LM Ericsson, Nokia Corporation, Huawei Technologies Co., Ltd., ZTE Corporation, Cisco Systems, Inc., Celona, Inc., Zebra Technologies Corporation, MicroPort MedBot (Group) Co., Ltd., Boldyn Networks, Verizon Communications Inc., AT&T Inc., T-Mobile US, Inc., Telia Company AB, Bouygues Telecom, Proximus NXT, COSMOTE TELEKOM (OTE Group), Singapore Telecommunications Limited (Singtel), Bharti Airtel Limited (Airtel Business), NTT DATA, Kajeet |

Frequently Asked Questions
Key players include Ericsson, Nokia, Huawei, ZTE, Cisco, Celona, Zebra Technologies, MicroPort MedBot, Boldyn Networks, Verizon, AT&T, T-Mobile US, Telia, Bouygues Telecom, Proximus NXT, COSMOTE TELEKOM, Singtel, Airtel Business, NTT DATA and Kajeet.
Key opportunities include private 5G and neutral-host networks in hospitals, remote and robot-assisted surgery, 5G-connected ambulances, 5G-enabled medical devices and wearables, and managed services for network operation.
The need for low-latency, high-capacity wireless networks for remote monitoring, connected devices and telemedicine is the main growth factor, supported by public funding for smart hospital projects.
By Component, the Hardware segment dominated the market in 2025 with an estimated 62.11% share, supported by radios, gateways, sensors and 5G-enabled clinical devices.
North America dominated the market with a share of 36.49% in 2025, driven by large health systems, active private network programs and strong telecom operators.
