
Advanced Composites Market Report Scope & Overview:
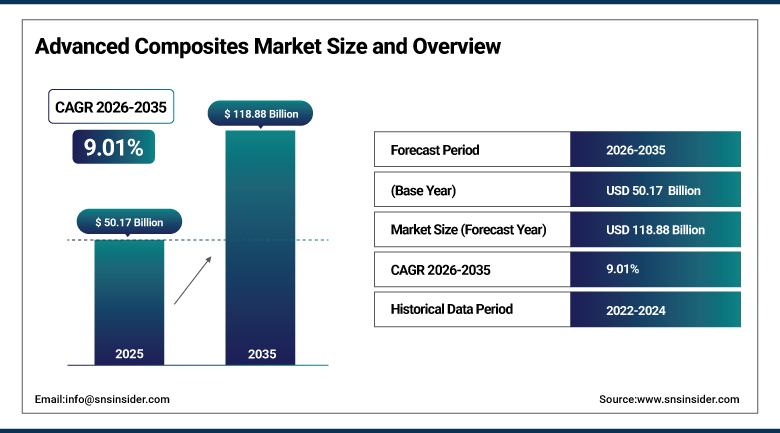
The Advanced Composites Market was valued at USD 50.17 Billion in 2025 and is expected to reach USD 118.88 Billion by 2035, growing at a CAGR of 9.01% from 2026-2035.
The Advanced Composites Market is growing due to rise in the need for lightweight, durable, and strong materials among aerospace, automotive, wind power, and defense industries. There is an increasing use of advanced composites by aerospace players for the reduction of structure weight, efficiency in fuel, and performance improvement. Increase in the production of electric vehicles is adding up to the usage as manufacturers want to increase the distance traveled by the vehicle and boost their efficiency. Moreover, there is an expansion in renewable energy infrastructure which is raising the requirement for composite materials used in wind turbine blades. Technology improvements in carbon fiber, glass fiber, and resin are adding to the advancement in materials and process.
⮞In January 2026, Airbus reported that it delivered 793 commercial aircraft in 2025. Higher aircraft output sustains demand for aerospace-grade carbon fiber and prepreg across the Advanced Composites Market.
To Get more information Advanced Composites Market - Request Free Sample Report
Advanced Composites Market Trends
-
Aerospace build-rate recovery after destocking is lifting prepreg and carbon fiber orders.
-
Chinese carbon fiber scale-up is widening supply for wind blades and industrial uses.
-
Thermoplastic and recyclable matrices are moving into qualified structural parts.
-
Multi-year supply agreements and vertical integration are securing aerospace-grade fiber.
-
Defense drones and hydrogen pressure vessels are opening new volume applications.
U.S. Advanced Composites Market Outlook
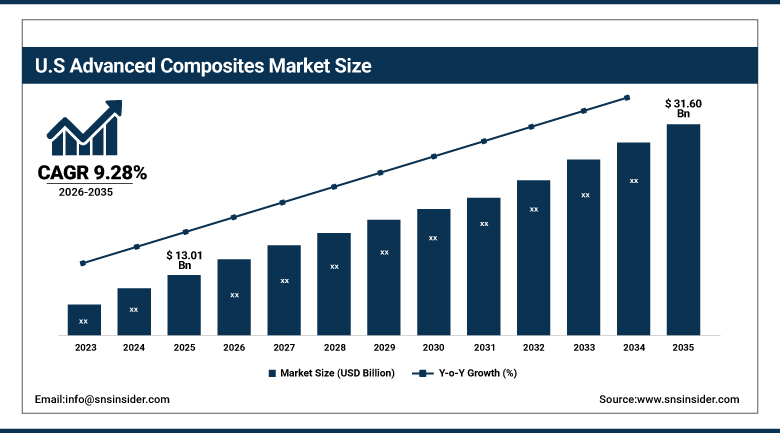
The U.S. Advanced Composites Market was valued at USD 13.01 Billion in 2025 and is expected to reach USD 31.60 Billion by 2035, growing at a CAGR of 9.28% from 2026-2035.
The U.S. Advanced Composites Market is expected to reach USD 14.22 Billion in 2026 and already represents roughly a quarter of global value. Commercial aircraft production, military modernization and wind energy projects underpin demand. Aerospace primes are qualifying automated fiber placement lines and out-of-autoclave prepregs to raise output per shift. Defense buyers are funding low-cost drone airframes built from carbon and glass fiber laminates. Hydrogen storage programs add further volume for pressure vessels. A deep base of aerospace suppliers sustains investment in capacity and workforce skills. Tariff exposure on imported fiber and resin remains a planning variable for buyers and producers alike.
Boeing reported in April 2026 that its 737 program continues to produce at 42 per month and its 787 program continued stabilizing production at eight per month. These rates keep U.S. composite structure suppliers and prepreg producers on a steady demand path.
Advanced Composites Market Segment Analysis
-
By Fiber Type, the Carbon Fiber segment dominated the Advanced Composites Market with approximately 62.63% share in 2025, and is also the fastest growing with a CAGR of approximately 9.62%.
-
By Application, the Aerospace and Defense segment dominated the Advanced Composites Market with approximately 40.25% share in 2025, and is also the fastest growing with a CAGR of approximately 10.31%.
-
By Resin Type, the Thermoset segment dominated the Advanced Composites Market with approximately 67.00% share in 2025, while the Thermoplastic segment is the fastest growing with a CAGR of approximately 10.74%.
By Fiber Type, Carbon Fiber Dominates the Advanced Composites Market and Grows Fastest
The carbon fiber segment dominates the Advanced Composites Market owing to its excellent strength to weight ratio, stiffness, fatigue resistance, and corrosion resistance. Carbon fibers have been extensively used in various industries such as aerospace, defense, automotive, wind energy, and industrial equipment due to their high mechanical performance and durability. Aerospace companies use carbon fibers to cut down structural weight to ensure fuel efficiency, whereas automotive companies use them to increase the performance of vehicles. Increasing demand for lightweight material and advancement in composite manufacturing technology drive the adoption of carbon fibers across industries.
The carbon fiber segment is also expected to register the fastest growth due to increasing focus on light weight structures, energy efficiency, and higher performance. Companies involved in electric vehicle manufacturing are researching on carbon fiber composites to reduce the weight of the vehicles as well as increase the driving range. The segment also sees growth opportunities from aerospace companies that are looking to expand their use in next generation aircrafts. Growth opportunities are also observed in wind energy application especially large turbine blades and structural components.
⮞In December 2025, Mitsubishi Chemical Group announced projects to approximately double carbon fiber production capacity at its Tokai plant in Japan and its Sacramento plant in California, with phased enhancement planned from 2025 to 2027. The expansion adds high-end fiber supply on two continents for the Advanced Composites Market.
By Application, Aerospace and Defense Dominates the Advanced Composites Market and Grows Fastest
The aerospace and defense segment dominates the Advanced Composites Market due to the requirement of materials which offer strength, light weight, durability, and performance under extreme conditions for aircrafts and defense vehicles. The applications of advanced composites include aircraft fuselage, wings, engine, military aircraft, and spacecraft. The reduction in structural weight along with mechanical properties facilitates fuel efficiency and payload capacity. The production growth, modernization of the aircraft fleet, defense procurement, and space exploration initiatives support growth in the advanced composite material market in the aerospace and defense segments.
The aerospace and defense segment is expected to grow rapidly due to an increase in the production of aircraft and introduction of next generation aircraft. The growing demand for fuel efficient aircraft, defense modernization, UAVs and spacecraft encourages the use of lightweight and high performance materials. Carbon fiber composites and advanced resin systems assist in structural efficiency and performance in tough environments. Growth in defense spending and R&D in aerospace industry helps in material innovations.
⮞In April 2026, the Global Wind Energy Council (GWEC) reported that the industry installed a record 165 GW of new wind capacity in 2025. Each new turbine needs large composite blades, which makes wind energy a major volume outlet for glass and carbon fiber laminates.
By Resin Type, Thermoset Dominates the Advanced Composites Market and Thermoplastic Grows Fastest
The thermoset segment dominates the Advanced Composites Market owing to the availability of well-established processing techniques and good mechanical properties of thermoset resins, especially epoxies and polyesters, in a variety of applications. They exhibit good fiber bonding properties, dimensional stability, chemical resistance, and suitability for complicated composite structures. The application in aerospace structures, wind turbine blades, automotive parts, and industrial equipment contributes to the high demand for this product type. Well-established manufacturing facilities, qualification programs, and availability of the material further strengthen its market position. Improvement in the formulation of the material helps manufacturers meet the increasing performance expectations.
The thermoplastic segment is expected to grow rapidly due to the short cycle time, impact resistance, and the possibility of reuse of materials when compared to many traditional thermosets. The material can be reprocessed and reused which leads to improved manufacturing and recycling in some cases. Manufacturers in the transportation industry have shown increasing interest in the thermoplastic composites for producing lighter components in large quantities. There are possibilities of application in aerospace as well where rapid manufacturing and damage tolerance are required.
⮞In July 2026, Teijin announced a thermosetting long carbon fiber reinforced plastic that is heat-repairable and recyclable, with mechanical properties equivalent to conventional CFRPs and development samples planned from 2028. The material targets the end-of-life gap that has constrained thermoset composites.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
68.04 |
|
Asia Pacific |
China |
51.84 |
|
Europe |
Germany |
29.61 |
|
Latin America |
Brazil |
37.92 |
|
Middle East & Africa |
United Arab Emirates |
41.38 |
North America Advanced Composites Market Insights
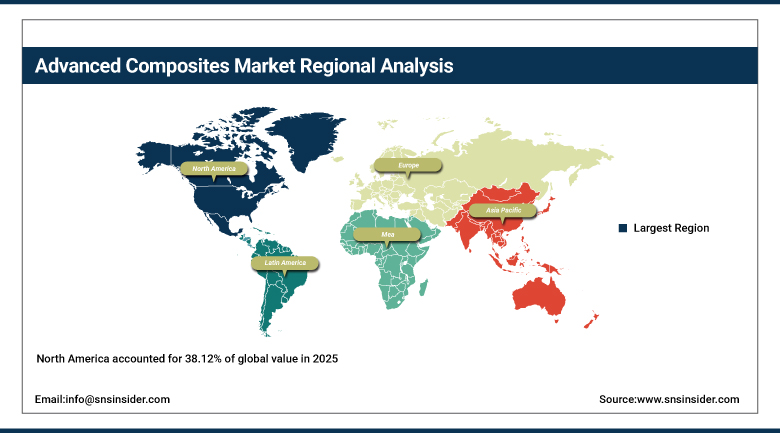
North America accounted for 38.12% of global value in 2025, a lead attributed to its dense base of aircraft integrators, engine makers and defense primes. The United States anchors regional demand through commercial aircraft assembly, military aircraft sustainment and a rising number of drone production programs. Canada contributes through aerospace component manufacturing and wind energy supply chains that draw on glass and carbon fiber. Regional fiber and prepreg plants sit close to customers, which shortens qualification cycles and limits exposure to cross-border tariffs. Research universities and national laboratories further support process development in automated layup and recycling.
Investment is shifting toward automation and resilient supply. Aerospace suppliers are installing automated placement cells and out-of-autoclave curing to meet higher build rates and to reduce energy use. Defense programs reward suppliers with qualified U.S. production, which supports producers of carbon fiber and prepreg. Wind developers still need blade materials even as policy uncertainty slows project timing. Pilot projects for recycling cured composite scrap are also appearing, and they are expected to widen sourcing options for tier one suppliers. Workforce training for composite technicians has become a priority for plants adding capacity across the region.
⮞In August 2026, Toray Advanced Composites joined IGCS International and Lacks Carbon Fiber in a cooperation to support the U.S. Drone Dominance Program, with Toray supplying pre-impregnated carbon and glass fiber reinforced composite materials. The program links prepreg capacity to a fast-growing drone demand base across North America.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Advanced Composites Market Insights
Europe remains a technology center for aerospace composites through commercial aircraft assembly lines, helicopter makers and space programs. Germany leads regional consumption owing to its aircraft, automotive and machinery industries and its research institutes working on automated layup and thermoplastic welding. France, the United Kingdom, Italy and Spain supply fuselage sections, wings and engine parts for major airframe programs, which keeps the regional prepreg and honeycomb base busy. Premium automotive and motorsport brands add steady demand for carbon fiber monocoques and body panels in low-volume series. Aircraft maintenance and repair hubs in the region sustain demand for repair patches and bonded repair materials.
Wind blades form a second pillar because regional factories supply European turbine makers and export to other markets. Strict sustainability rules push developers to qualify recyclable resins and chemical recycling routes for end-of-life blades. Energy-intensive fiber production tends to face higher operating costs in Europe, so regional output concentrates on prepreg, fabric and component conversion. Cooperation between universities and industry on out-of-autoclave processing keeps the region competitive in high-value applications. Offshore wind build-out in the North Sea is expected to sustain demand for long glass and carbon fiber blades through the forecast period.
⮞GE Vernova reported in May 2025 the transfer of its LM Wind Power blade factory in Goleniów, Poland to Vestas. The site, established in 2009 and expanded in 2017, supports production for the V172-7.2 MW turbine and underlines Europe's role in wind blade composites.
Asia Pacific Advanced Composites Market Insights
Asia Pacific is projected to expand at a CAGR of 11.84% during 2026-2035, the fastest rate among all regions. Chinese producers are scaling precursor and fiber output while Japan and South Korea keep supplying aerospace-grade and high-strength grades. China also installs most of the world's new wind capacity, so blade makers there are the largest regional buyers of large-tow carbon fiber and glass fiber. Local supply lowers material cost and encourages broader use in industrial and transport parts such as compressed gas cylinders, rollers and rail components. Expanding manufacturing clusters also shorten delivery times for regional customers.
Commercial aircraft programs in China and India are building local supply chains for composite structures, and this is raising demand for prepreg, honeycomb and tooling. Automakers and hydrogen vessel developers in the region add further pull for carbon fiber. Government industrial policies favor fiber self-sufficiency and reward investment in high-modulus grades. Chinese suppliers are narrowing the quality gap with Japanese rivals, and this is expected to shift more aerospace qualification work toward the region over the forecast period. Sporting goods and consumer electronics manufacturers in Taiwan and Vietnam remain steady buyers of carbon fiber fabric.
⮞Zhongfu Shenying reported in March 2026 that it has PAN-based dry-jet wet-spinning carbon fiber production capacity of 29,000 tons, with another 31,000 tons under construction. The scale-up makes Asia Pacific the center of new carbon fiber supply for the Advanced Composites Market.
MEA & Latin America Advanced Composites Market Insights
Latin America is expanding on the strength of aircraft manufacturing in Brazil and component production in Mexico. Brazil hosts regional jet and executive aircraft assembly and adds onshore wind installations that need blade and tower materials. Mexico supplies aerostructure parts and wind blade manufacturing for North American customers through cross-border supply chains. Local resin and glass fiber supply supports construction, marine and automotive parts although most aerospace-grade fiber and prepreg is imported. Growing maintenance and repair activity for regional airline fleets also creates steady demand for composite repair materials. Infrastructure programs in Brazil and Mexico are widening use of glass fiber reinforced pipes and panels.
Middle East and Africa is a smaller base that is growing through aerospace localization and large infrastructure and energy projects. The United Arab Emirates leads with aerostructure manufacturing, aircraft maintenance activity and sovereign investment in advanced materials. Saudi Arabia and South Africa add demand from wind projects, defense procurement and industrial piping. Gulf governments are funding local manufacturing capacity, and this is expected to lift regional imports of fiber and prepreg over the forecast period. Corrosion-resistant composite pipes and tanks for oil, gas and water systems offer an additional application outside aerospace.
⮞In January 2026, Embraer reported that it delivered 78 commercial jets and 155 executive jets in 2025. Production at this scale keeps Latin America a steady buyer of composite airframe components.
Market Dynamics
Growth Drivers: Rising aircraft build rates and wind blade installations are expanding demand for advanced composites
Airframers are restoring production rates after supply disruptions and each additional aircraft carries large composite wing and fuselage content. Narrow-body ramps pull prepreg and fiber through tier one structure suppliers while wide-body programs require carbon fiber barrels and spars. Parallel programs for engines, nacelles and interiors broaden volume. Defense procurement adds orders for fighter, rotorcraft and uncrewed aircraft structures. Airlines value fuel savings from lighter airframes under tight emissions objectives, which supports continued composite specification on new designs and on re-engined versions of existing models. Order backlogs extending across the decade support steady material call-offs for composite suppliers.
Wind energy provides an equally large pull. Longer blades require carbon fiber spar caps and glass fiber shells, and policy support for renewables is lifting orders across Asia and Europe. Lightweighting rules in transport and rising demand for hydrogen storage vessels extend the base further. Suppliers respond by signing multi-year agreements that lock in fiber and resin volumes. This gives producers the visibility needed to invest in new lines and automated processes, and it allows fabricators to plan staffing and tooling years ahead of delivery schedules.
⮞In August 2026, Syensqo signed a multi-year supply agreement with a leading European commercial aircraft manufacturer covering prepregs, RTM resins, adhesives and primers. Long-term contracts of this type give composite material suppliers stable volumes in the Advanced Composites Market.
Restraints: High material and processing costs and uneven supply conditions are limiting wider adoption of advanced composites
High production costs keep advanced composites out of many cost-sensitive uses. PAN precursor, energy-intensive oxidation and carbonization, autoclave curing and skilled labor all add expense, and finished parts often cost several times more than aluminum or steel equivalents. Qualification of a new material or process can take years of testing and certification, which delays revenue for suppliers. Brittleness, limited repairability and weak recycling infrastructure further restrict use in high-volume sectors such as automotive, where metals still offer cheaper and faster production. Recycling of cured parts remains costly and much scrap is still landfilled or burned, which raises waste handling expense.
Supply conditions have also been uneven. Inventory adjustments at major aerospace programs reduced orders for fiber and prepreg for several quarters. Tariff uncertainty has delayed decisions on installing or relocating wind blade lines. Consolidation and restructuring among fiber, glass and blade producers have changed the supplier base, leaving some buyers with fewer qualified sources. These swings make capacity planning difficult and encourage buyers to hold safety stocks, which in turn magnifies demand volatility and complicates long-term investment decisions for smaller fabricators. Shortages of skilled layup technicians further slow capacity ramp-ups in several regions.
⮞Hexcel reported in October 2025 that its sales decrease was a result of inventory destocking, primarily on the A350 program but also on the 787 program. The episode shows how build-rate adjustments at airframers ripple through the Advanced Composites Market.
Opportunities: Thermoplastic, recyclable and hydrogen storage applications are opening new revenue pools for composite suppliers
Thermoplastic and recyclable composites offer producers a route to higher-volume programs. Weldable tapes and liquid thermoplastic resins reduce fastener counts and cycle times while enabling reuse of scrap and end-of-life parts. Aircraft makers, wind turbine operators and automakers are all seeking recycling pathways, which favors suppliers that can document recovery processes. Early movers in qualified recyclable systems can secure preferred supplier status for future platforms. Chemical and mechanical recycling technologies also create a secondary market for recovered carbon fiber in injection molding compounds and consumer goods. Thermoplastic parts also support high-rate molding for automotive and consumer electronics frames.
Hydrogen pressure vessels are another expanding outlet. Type IV and type V tanks need large amounts of carbon fiber and are being developed for trucks, buses, rail and aviation. Ceramic matrix composites in engines and hot structures offer further growth where Asia Pacific aerospace programs are scaling. Added fiber capacity and defense drone programs create parallel demand. Together these applications let suppliers diversify beyond cyclical airframe orders and build resilient revenue streams, while the push toward bio-based resins and precursors adds a sustainability-led product line. Aviation hydrogen programs would need cryogenic and high-pressure tank structures that favor composite designs.
⮞In February 2026, Arkema reported work with Air Liquide and Covess under the Roadthrypp program on type V hydrogen vessels that combine UDX carbon tapes with bio-based PA11 and PPA matrices. The project shows how thermoplastic composites can reach hydrogen storage, a growing application in the Advanced Composites Market.
Recent Developments
-
August 2025, Aksa Carbon began operating under sole ownership after Aksa Akrilik bought Dow's 50% stake in the former DowAksa venture for USD 125 million and renamed the business. The change gives the carbon fiber producer full control over investment and capacity decisions.
-
July 2026, TPI Composites emerged from Chapter 11 as an independent manufacturer of composite wind blades with factories in the U.S. and Mexico. The exit restores financial footing for a major blade supplier and reassures wind turbine customers about blade supply.
-
January 2026, Gurit reported a long-term contract described as its first major agreement based on the supply of core kits using OptiCore technology. The deal shows blade makers adopting integrated core kit solutions for wind blade production.
-
April 2026, Owens Corning announced completion of the sale of its glass reinforcements business to Praana Group after announcing the transaction in February 2026. The divestiture moves a major glass fiber reinforcement portfolio to a dedicated owner and refocuses Owens Corning on roofing, insulation and doors.
Advanced Composites Companies are:
-
Toray Industries
-
Hexcel
-
Teijin
-
Mitsubishi Chemical Group
-
Gurit
-
Park Aerospace
-
Arkema
-
HS Hyosung Advanced Materials
-
Zhongfu Shenying
-
Albany International
-
Axiom Materials
-
Hexagon Agility
-
TPI Composites
Advanced Composites Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 50.17 Billion |
| Market Size by 2035 | USD 118.88 Billion |
| CAGR | CAGR of 9.01% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Fiber Type (Carbon Fiber, Glass Fiber, and Aramid Fiber) • By Application (Aerospace and Defense, Automotive, Wind Energy, Construction, Sporting Goods, and Others) • By Resin Type (Thermoset and Thermoplastic) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Toray Industries, Hexcel, Teijin, Mitsubishi Chemical Group, Syensqo, Gurit, Park Aerospace, Arkema, HS Hyosung Advanced Materials, Zhongfu Shenying, Aksa Carbon, Albany International, Axiom Materials, Hexagon Agility, TPI Composites |

Frequently Asked Questions
Key players in the Advanced Composites Market include Toray Industries, Hexcel, Teijin, Mitsubishi Chemical Group and Syensqo among others.
Key opportunities include thermoplastic and recyclable composites, hydrogen pressure vessels, defense drone airframes and added carbon fiber capacity in Asia Pacific. These areas let suppliers diversify beyond cyclical airframe orders.
The major growth factor is rising demand for lightweight, high-strength materials in aircraft and wind turbine blades as airframers restore build rates and developers install larger rotors.
The Carbon Fiber segment dominated the Advanced Composites Market with approximately 62.63% share in 2025 owing to its stiffness-to-weight advantage in primary aircraft structures and wind blade spar caps.
North America dominated the Advanced Composites Market with a 38.12% share in 2025 owing to its concentration of aircraft integrators, engine makers and defense programs in the United States and Canada.
