
Barrier Systems Market Report Scope & Overview:
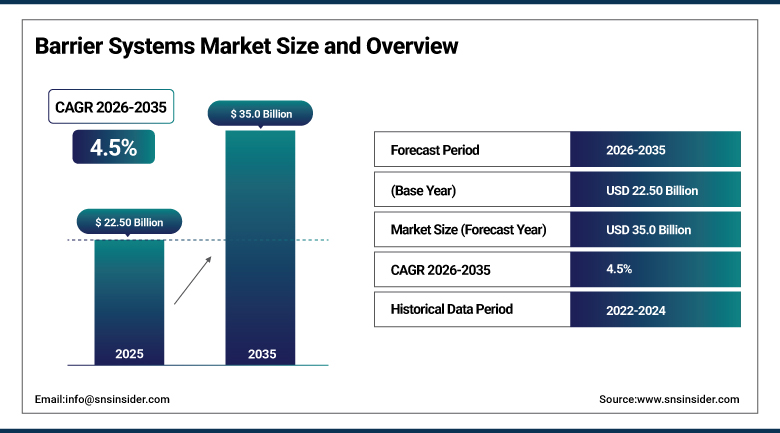
The Barrier Systems Market was valued at USD 22.50 Billion in 2025 and is expected to reach USD 35.0 Billion by 2035, growing at a CAGR of 4.5% from 2026–2035.
The Barrier Systems Market is experiencing steady growth due to higher investments in road infrastructure, highways, and transportation safety on a global scale. The rising worries about road accidents are increasing the need for crash barriers, guardrails, bollards, and more. There are higher standards for road safety by governments that are improving old infrastructure, thereby helping in the expansion of this market. There are several benefits offered by airports and railways due to which there is an increased scope for barrier systems. The rising trend of urbanization and vehicle ownership has also led to improvements in traffic and pedestrian management systems.
Hill & Smith Infrastructure launched its Incursion Defender barrier in response to a genuinely alarming statistic: England's roads recorded 23,981 vehicle incursions into live roadworks since 2017, including 2,833 in 2025 alone, according to National Highways' own Incursion Working Group.
To Get more information Barrier Systems Market - Request Free Sample Report
Barrier Systems Market Trends
-
Rising investments in road, highway, and transportation infrastructure driving demand for barrier systems to improve traffic safety and roadside protection
-
Growing adoption of crash-tested and high-performance barriers to reduce vehicle impact severity and protect motorists, pedestrians, and infrastructure assets
-
Increasing use of smart and connected barrier systems integrated with sensors, monitoring, and automated control technologies for real-time traffic management
-
Expanding construction and redevelopment of bridges, tunnels, airports, and commercial facilities supporting installation of advanced vehicle and pedestrian barrier solutions
-
Continuous advancements in lightweight materials, modular designs, and energy-absorbing technologies improving barrier durability, installation efficiency, and overall safety performance
U.S. Barrier Systems Market Outlook
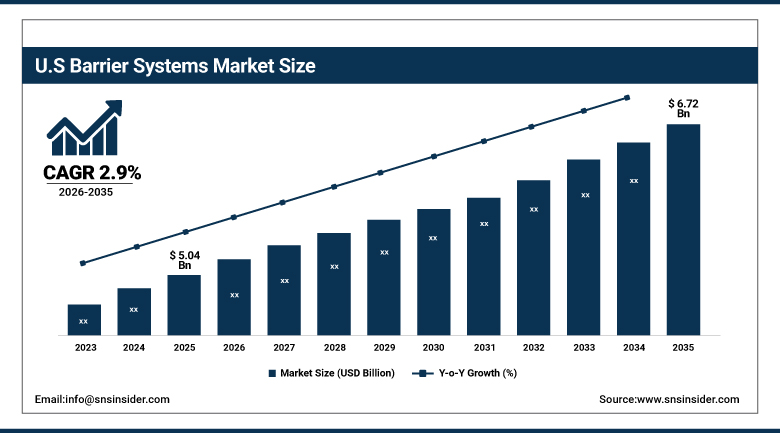
The U.S. Barrier Systems Market was valued at approximately USD 5.04 Billion in 2025 and is expected to reach approximately USD 6.72 Billion by 2035, growing at a CAGR of approximately 2.9%.
Demand in the United States is anchored by ongoing federal and state highway safety programs, alongside steady government and commercial investment in perimeter security following heightened attention to hostile vehicle attacks in public spaces. State departments of transportation represent a substantial and recurring buyer base, given how much routine highway maintenance and expansion work requires crash barriers, guardrails, and temporary work-zone protection. A handful of vertically integrated manufacturers with deep domestic manufacturing and installation networks continue to hold the strongest relationships with state and federal infrastructure buyers.
Hill & Smith Holdings, the UK-listed maker of crash barriers and road safety hardware, has expanded its U.S. manufacturing footprint through a string of acquisitions, including its roughly USD 30 million purchase of Whitlow Electric Service Company, a Georgia-based structural steel and electrical infrastructure specialist.
The company's Columbus, Ohio-headquartered U.S. subsidiary, formed in 2008, has grown from a single MASH-tested portable barrier product into a broad domestic road safety portfolio, illustrating how much of the American barrier systems market has consolidated around a handful of vertically integrated manufacturers rather than staying fragmented across small regional suppliers.
Barrier Systems Market Segment Analysis
-
By Device Type, the Crash Barrier Systems segment dominated the Barrier Systems Market with approximately 35.6% share in 2025, while the Bollards segment is the fastest growing with a CAGR of approximately 9.6%.
-
By Operation Type, the Passive Barriers segment dominated the Barrier Systems Market with approximately 64.0% share in 2025, while the Active Barriers segment is the fastest growing with a CAGR of approximately 7.4%.
-
By Material, the Metal segment dominated the Barrier Systems Market with approximately 42.7% share in 2025, while the Plastic segment is the fastest growing with a CAGR of approximately 6.8%.
-
By Application, the Roadways segment dominated the Barrier Systems Market with approximately 53.6% share in 2025, while the Airports segment is the fastest growing with a CAGR of approximately 6.4%.
By Device Type, crash barrier systems dominate, bollards grow fastest
Crash barrier systems held the largest share of the device-type segment in 2025, covering the guardrails, median barriers, and impact attenuators that make up the backbone of highway safety infrastructure worldwide. Their widespread mandated use on highways, bridges, and other high-speed roadways keeps this the largest device category by a wide margin over any other single product type.
Bollards are growing fastest as urban security concerns, pedestrian safety initiatives, and demand for anti-ram protection in commercial and public spaces continue expanding well beyond bollards' traditional role as a simple parking deterrent. Modern fixed and retractable bollard designs now offer genuine anti-ram protection alongside improved aesthetics, making them an increasingly popular choice for cities and commercial property owners balancing security with public space design.
By Operation Type, passive barriers dominate, active barriers grow fastest
Passive barriers accounted for the largest share of the operation-type segment in 2025, covering fixed installations like guardrails, fences, and static bollards that don't require power or a control system to perform their protective function. Their simplicity, lower cost, and minimal maintenance requirements keep passive barriers the default choice across the majority of roadway and perimeter applications.
Active barriers are growing fastest as automated bollards, boom barriers, and road blockers requiring energy and command input continue gaining share in applications demanding conditional access control. Integration with AI-driven surveillance and smart infrastructure systems is accelerating this shift, letting operators grant or deny access dynamically rather than relying on a fixed physical barrier that treats every vehicle the same way.
By Material, metal dominates, plastic grows fastest
Metal held the largest share of the material segment in 2025, valued for its superior strength, durability, and impact resistance relative to plastic, concrete, or wood alternatives. Its long service life and ability to withstand harsh environmental conditions make metal the preferred material for high-security zones, roadways, and industrial applications where failure simply isn't an acceptable outcome.
Plastic is growing fastest as demand rises for lightweight, portable, and cost-effective barrier solutions suited to temporary work zones and applications where frequent relocation matters more than maximum impact resistance. That portability advantage is proving particularly valuable for construction sites and event spaces that need barriers deployed and removed repeatedly over a project's lifecycle.
By Application, roadways dominates, airports grows fastest
Roadways accounted for the largest application share in 2025, reflecting the sheer scale of global highway networks and the mandated safety infrastructure requirements that apply across nearly every stretch of high-speed road. Ongoing highway expansion and modernization projects in both developed and emerging markets continue reinforcing this application's dominant position.
Airports are the fastest-growing application as aviation security investment continues expanding globally, driven by heightened attention to perimeter protection and vehicle access control at both passenger terminals and secure airside areas. Growing air travel volumes and continued airport expansion projects worldwide are adding further momentum to this above-average growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Europe |
Germany |
26.0% |
|
North America |
United States |
80.0% |
|
Asia Pacific |
China |
37.0% |
|
Latin America |
Brazil |
36.0% |
|
Middle East & Africa |
Saudi Arabia |
33.0% |
North America Barrier Systems Market Insights
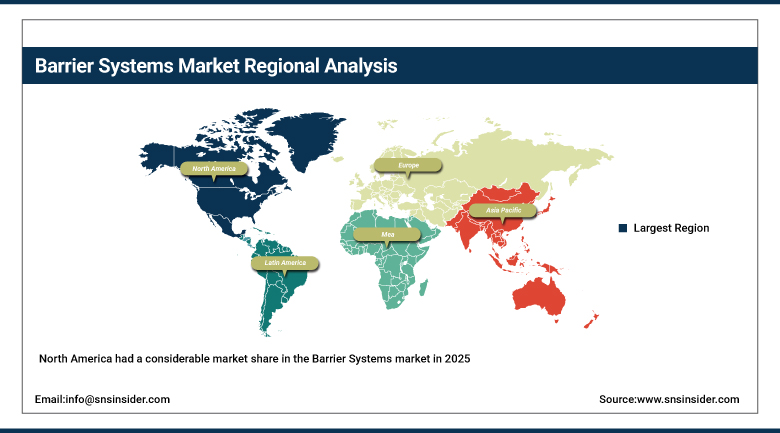
North America had a considerable market share in the Barrier Systems market in 2025, due to having a well-developed infrastructure system, safety regulations, and investments made in developing highways. The demand for barrier systems used in securing vehicles, perimeters, and managing traffic is on the rise. This, along with the need for replacing the old infrastructure and implementation of high-end crash barriers, bollards, gates, and automation solutions is contributing to the market's growth until 2035.
The demand from Canada comes from its own highway safety and infrastructure projects, whereas Mexico's market is continuously growing with increasing investment in road infrastructure. The manufacturer relationships between the countries in the region bind most of the demand within North America.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Barrier Systems Market Insights
In 2025, Europe held the largest market share in the Barrier Systems Market, capturing about 34%, aided by strict road safety standards, sophisticated infrastructure, and high number of vehicles on roads. The construction of highways, railways, and airports remains a key driver in the barrier systems market. Urbanization and rising security concerns in commercial, residential, and public buildings remain key drivers of market adoption. Europe is expected to hold the leading position till 2035 owing to modernization efforts and implementation of barrier systems that are technologically advanced.
Germany, France, and the United Kingdom have significant contribution to the European market for barrier systems due to their extensive highways and strict vehicle restraint system standards. Highway modernization projects, along with new corridor upgrade projects in the United Kingdom, will ensure continued growth in the barrier systems market.
Asia Pacific Barrier Systems Market Insights
Asia-Pacific Barrier Systems Market is expected to be the fastest-growing market on account of rapid urbanization, development in transportation infrastructure and rising highway construction. The rising number of vehicles and the need for improved road safety are expected to drive the adoption of barrier systems like crash barriers, bollards, gates, etc. The regions are increasingly investing in transportation security and infrastructure development. Furthermore, the growing development of airports and railways along with smart city projects will offer immense scope for the adoption of automated barrier systems until 2035.
The vast highway construction plans of China make the region have high base demand, while India is witnessing significant investment in national highways and vehicle restraint systems. Japan and South Korea are more matured markets with existing standards in road safety.
MEA & Latin America Barrier Systems Market Insights
The Middle East and Africa represent a smaller but strategically significant barrier systems market, with Saudi Arabia driving demand through substantial infrastructure and security investment tied to the country's broader economic diversification strategy. Growing government and commercial investment in perimeter security across the region continues supporting steady demand growth.
Latin America is a growing market, led by Brazil, where highway expansion, urbanization, and increasing security investments are driving demand for roadway and commercial barrier systems. Mexico and Colombia also contribute to regional growth through infrastructure development, public safety initiatives, and increasing investments in transportation security solutions.
Market Dynamics
Growth Drivers: Infrastructure investment and road safety regulation fueling adoption
Large-scale infrastructure development and modernization of aging road networks are one of the clearest forces behind rising barrier systems demand, as governments worldwide fund highway expansion, bridge construction, and public transportation projects that all require compliant safety hardware. That sustained infrastructure investment gives the barrier systems market a demand base that holds up reliably even through broader economic cycles.
Stringent road safety regulation and rising traffic accident awareness add a second major driver, as government initiatives, including the WHO's Decade of Action for Road Safety, push stricter mandates for crash barrier installation on highways, bridges, and sharp turns. Growing vehicle density in expanding urban centers continues reinforcing this regulatory pressure across both developed and emerging markets.
Restraints: Fluctuating raw material costs and installation complexity limiting adoption speed
Fluctuating steel, aluminum, and other raw material costs remain a genuine restraint for manufacturers, since metal continues to dominate the material mix and price swings in these commodity markets directly affect production costs and, ultimately, project budgets for buyers. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when installation demand remains steady.
Installation complexity adds a further restraint, particularly for permanent crash barrier and vehicle restraint systems that require precise engineering to meet crash-testing standards and specific roadway conditions. That technical complexity can extend project timelines and increase costs, especially for large-scale highway corridor upgrades that must maintain traffic flow throughout construction.
Opportunities: Smart barrier integration and hostile vehicle mitigation expansion opening new growth avenues
Smart, sensor-integrated barrier technology offers manufacturers a genuine path to capturing premium pricing from government and commercial customers seeking real-time incident detection and automated response capability beyond a barrier's purely physical function. Companies that build genuine smart infrastructure integration expertise are positioned to capture disproportionate growth as AI-driven security adoption continues expanding.
Expanding hostile vehicle mitigation demand beyond traditional government and critical-infrastructure applications into commercial real estate and public event spaces represents a second significant opportunity. Manufacturers that build strong relationships with commercial property developers and event venue operators are positioned to capture a growing share of this expanding, security-driven application category.
Recent Developments:
-
June 2025: Hill & Smith consolidated four UK vehicle restraint system subsidiaries, Asset VRS, Varley & Gulliver, Hardstaff Barriers, and Hill & Smith Barrier, into a single business group to streamline service delivery across the UK road safety barrier market.
-
April 2026: National Highways awarded a major contract for upgraded vehicle restraint and crash barrier systems across the M25 corridor, part of a broader push to modernize UK motorway safety infrastructure.
-
2025: Multiple major barrier manufacturers, including Lindsay Corporation and Trinity Highway Products, continued integrating sensor-based smart monitoring technology into crash barrier and bollard systems to enable real-time incident detection.
-
2025: Manufacturers across the industry continued developing modular, quick-deploy barrier designs aimed at reducing worker exposure to live traffic during installation and removal at temporary work zones.
Barrier Systems Market Key Players
-
Tata Steel Limited
-
Trinity Industries, Inc.
-
Lindsay Corporation
-
Hill & Smith Holdings PLC
-
Valmont Industries, Inc.
-
Bekaert
-
A-SAFE
-
Betafence
-
Barrier1 Systems, LLC
-
Nucor Corporation
-
Valtir, LLC
-
Delta Scientific Corporation
-
Maccaferri
-
Rite-Hite
-
BOPLAN
-
Fabenco by Tractel
-
DELTA BLOC International GmbH
-
Avon Barrier Corporation Ltd.
-
Transpo Industries, Inc.
-
Arbus Limited
Barrier Systems Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 22.50 Billion |
| Market Size by 2035 | USD 35.0 Billion |
| CAGR | CAGR of 4.5% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Device Type (Fences, Bollards, Gates, Crash Barrier Systems, Drop Arms & Boom Barriers, Others) • By Operation Type (Active Barriers, Passive Barriers) • By Material (Metal, Plastic, Concrete, Wood, Others) • By Application (Roadways, Airports, Railways, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tata Steel Limited, Trinity Industries, Inc., Lindsay Corporation, Hill & Smith Holdings PLC, Valmont Industries, Inc., Bekaert, A-SAFE, Betafence, Barrier1 Systems, LLC, Nucor Corporation, Valtir, LLC, Delta Scientific Corporation, Maccaferri, Rite-Hite, BOPLAN, Fabenco by Tractel, DELTA BLOC International GmbH, Avon Barrier Corporation Ltd., Transpo Industries, Inc., Arbus Limited |
Frequently Asked Questions
Key players include Tata Steel Limited, Trinity Industries, Inc., Lindsay Corporation, Hill & Smith Holdings PLC, and Valmont Industries, Inc., among others.
Key opportunities include smart barrier integration, hostile vehicle mitigation, AI-driven monitoring, modular deployment, airport security, and resilient roadway infrastructure.
Large-scale infrastructure development and modernization of aging road networks combined with stringent road safety regulation and rising traffic accident awareness.
Crash Barrier Systems dominated with approximately 35.6% share in 2025, while Bollards is the fastest growing segment with a CAGR of approximately 9.6%.
Europe dominated the Barrier Systems Market in 2025.
