
Carbonyl Iron Powder Market Report Scope & Overview:
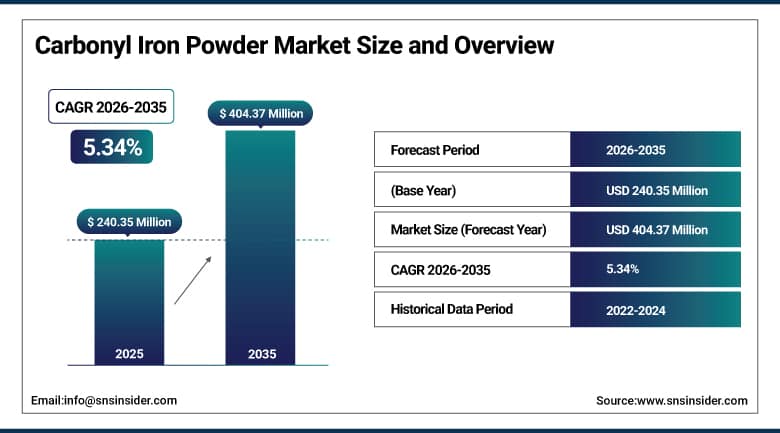
The Carbonyl Iron Powder Market size was valued at USD 240.35 Million in 2025 and is expected to reach USD 253.18 Million in 2026, rising to USD 404.37 Million by 2035, at a CAGR of 5.34% during 2026–2035. Carbonyl iron powder is a fine, spherical and highly pure iron powder made by decomposing iron pentacarbonyl. It is used in high-frequency inductors, metal injection molding, radar absorbing materials, diamond tools, magnetorheological fluids and nutritional supplements. Demand is rising with electronics miniaturization and vehicle electrification. Growth is strongest where electronics and vehicle makers need finer, purer powder.
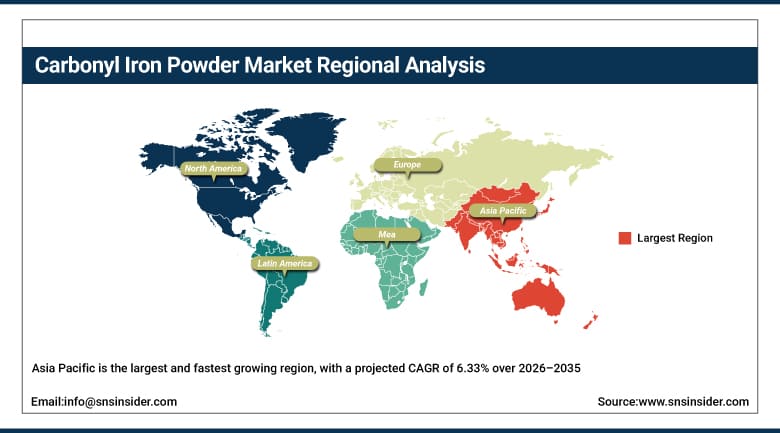
Asia Pacific accounted for the largest share of the market, at 43.82% in 2025, because the region hosts the largest electronics, magnetic component and powder metallurgy industries and a growing group of local producers. China leads consumption and output, with Japan, South Korea and India adding demand from inductors, vehicles and tools. Europe and North America follow, supported by established producers, automotive suppliers and defense programs that specify high-purity grades. Middle East and Africa and Latin America are smaller markets served mainly by imports, although vehicle assembly, tool making and electronics assembly are widening local demand for fine iron powders.
To Get More Information On Carbonyl Iron Powder Market - Request Free Sample Report
Key Report Takeaways:
-
By type, reduced carbonyl iron powder held a 64.38% share in 2025, while atomized carbonyl iron powder is the fastest growing.
-
By purity grade, high-purity powder held a 51.84% share in 2025, while ultra-high-purity powder is the fastest growing.
-
By application, powder metallurgy held a 38.46% share in 2025, while electronic components are the fastest growing.
-
By end-use industry, automotive held a 31.47% share in 2025, while healthcare and pharmaceuticals are the fastest growing.
-
By region, Asia Pacific held a 43.82% share in 2025, and it is also the fastest growing.
Market Trends and Insights:
Power electronics designers are asking for smaller inductors that carry more current at higher switching frequencies. Carbonyl iron powder with fine, round particles and a thin insulating coating keeps core losses low, so suppliers are narrowing particle size distributions and offering coated grades for molded chokes. Server boards, vehicle converters and fast chargers are the main sources of this demand.
Producers are also adding capacity and improving process economics. New lines in China use lower-cost synthesis and decomposition routes, and plants are being sited near electronics and automotive customers. Quality control is moving toward tighter chemistry, oxygen and carbon limits, while suppliers outside China focus on certified high-purity grades for defense, medical and food uses.
Drivers Impact Analysis:
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Miniaturized inductors for servers and electronics |
+2.86% |
Asia Pacific and North America |
Long term (4 years or more) |
|
Vehicle electrification and magnetorheological dampers |
+2.07% |
Asia Pacific, Europe and North America |
Medium term (2 to 4 years) |
|
Growth in metal injection molding and powder metallurgy |
+1.18% |
Global |
Medium term (2 to 4 years) |
|
Radar absorbing and defense applications |
+0.74% |
North America, Europe and Asia Pacific |
Short term (2 years or less) |
|
Nutritional and pharmaceutical use of high-purity grades |
+0.45% |
Global |
Short term (2 years or less) |
Miniaturized Inductors for Servers and Electronics
Carbonyl iron powder is the preferred raw material for molded power inductors because its spherical particles allow high density and low loss at high frequency. Artificial intelligence servers, graphics processors and fast chargers need compact chokes that handle large currents, and board designers keep reducing the space reserved for passive parts. Component makers in Japan, South Korea, Taiwan and China are qualifying finer and more uniform grades, which turns electronics into the most dynamic source of volume for the powder.
Vehicle Electrification and Magnetorheological Dampers
Electric and hybrid vehicles use more inductors, filters and shielding parts than combustion models, and premium suspensions use magnetorheological fluid containing carbonyl iron. In May 2026, the International Energy Agency reported that more than 20 million electric cars were sold in 2025 and expected about 23 million in 2026. As adoption grows, each additional model adds converters, on-board chargers and sensors that draw on fine iron powder, and more automakers are fitting adaptive dampers to mid-range models. Dampers built around the fluid also need steady, well-graded powder.
Growth in Metal Injection Molding and Powder Metallurgy
Metal injection molding turns fine powder into small, complex parts for phones, wearables, medical tools, firearms components and automotive sensors. Carbonyl iron powder gives high sintered density, smooth surfaces and fine detail that coarser iron powders cannot match. Makers of hinges, gears, locks and surgical parts are moving from machining to molding to cut waste, and this shift lifts orders for fine, consistent powder, especially in Asia where molding capacity continues to expand. Medical device and electronics makers add further volume as component sizes shrink and tolerances tighten.
Radar Absorbing and Defense Applications
Carbonyl iron powder absorbs microwave energy and is mixed into coatings, foams and sheets that reduce radar reflection on aircraft, ships and ground systems. Defense ministries in North America, Europe and Asia are upgrading fleets and sensors, and stealth coatings need dependable supply of high-purity, tightly specified powder. Qualification is strict and contracts are long, so suppliers that pass military and aerospace approvals secure stable demand for many years. Fleet modernization and the repair of older coatings also create repeat demand across the service life of each platform.
Nutritional and Pharmaceutical Use of High-Purity Grades
Food and pharmaceutical grades of carbonyl iron are used as an iron source in fortified foods, cereals and supplements because they are well tolerated and have high bioavailability. Governments and health agencies run fortification and supplementation programs to address iron deficiency, particularly among women and children. Manufacturers value the pure, uniform powder for dosing accuracy, and growing consumer interest in iron supplements broadens the customer base for certified grades. Chewable tablets, enriched cereals and infant formula use small quantities of iron powder, and quality certification supports premium pricing for approved suppliers.
Restraints Impact Analysis:
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Hazardous feedstock and strict safety permitting |
-0.82% |
Global, strongest in Europe and North America |
Long term (4 years or more) |
|
High cost and energy intensity versus other iron powders |
-0.54% |
Global |
Medium term (2 to 4 years) |
|
Concentrated supply and trade barriers |
-0.39% |
Europe and North America |
Medium term (2 to 4 years) |
|
Long customer qualification cycles |
-0.21% |
Global |
Short term (2 years or less) |
Hazardous Feedstock and Strict Safety Permitting
Carbonyl iron powder is made from iron pentacarbonyl, a toxic and flammable liquid that requires specialized containment, monitoring and emergency systems. New plants face long reviews of air emissions, chemical handling and worker safety, and insurers and local authorities scrutinize each project. These requirements raise capital cost and delay start-up, and they discourage new entrants in regions with stringent chemical regulation, which keeps supply growth slower than demand in several cases. Insurance, transport and storage of the intermediate add further cost and complexity for producers and customers.
High Cost and Energy Intensity Versus Other Iron Powders
The carbonylation and decomposition route needs high pressure, controlled temperature and careful gas handling, and yields are limited by feedstock quality. As a result, carbonyl iron powder costs much more per tonne than water-atomized, reduced or electrolytic iron powder. Buyers in cost-driven applications such as structural powder metallurgy parts and standard magnetic cores therefore substitute cheaper powders where performance allows, which holds back volume outside premium uses. Energy price swings and the cost of recycling process gas affect margins, and producers must run plants at high utilization to keep unit cost competitive.
Concentrated Supply and Trade Barriers
Only a small group of companies operates large carbonyl iron plants, and several of them are located in a few countries. Buyers in Europe and North America depend on a limited number of suppliers, and tariffs, export licensing, dual-use controls and shipping rules for hazardous intermediates can interrupt deliveries. Customers respond by qualifying second sources and building safety stocks, which raises working capital and slows adoption of new suppliers. Political tensions can also affect access to Russian and Chinese output, and buyers outside those countries have few alternative large plants.
Long Customer Qualification Cycles
Inductor makers, automotive suppliers and defense contractors test powders for particle size, oxygen content, coating quality and consistency before approving a new source, and the process can last many months. Any change in plant, process or raw material may require retesting. These cycles slow the entry of new producers and new grades, and they delay the benefit of capacity additions even when demand is rising. Smaller suppliers bear the heaviest burden because testing is costly, and customers often prefer incumbents that already hold approvals, which limits the pace at which competition grows.
Carbonyl Iron Powder Market Segment Analysis:
By Type, Reduced Carbonyl Iron Powder Dominates Carbonyl Iron Powder Market; Atomized Carbonyl Iron Powder to Register Fastest Growth.
Reduced carbonyl iron powder holds 64.38% of the market in 2025 because it is the standard output of the decomposition process and the grade most widely approved by customers. Its spherical, onion-like particles give good compressibility and high-frequency performance, and producers can scale output on established lines. Inductor makers, metal injection molders and tool makers already specify it in qualified designs, so switching is slow. Long approval histories at large automotive and electronics customers further reinforce this position.
Atomized carbonyl iron powder is projected to grow at a CAGR of 5.90% during 2026–2035 as designers look for particles with controlled shape, lower oxygen and cleaner surfaces. Atomizing routes allow finer size control and alloying, which suits molded inductors, additive manufacturing and specialty magnetic parts. New lines in Asia and Europe are expanding availability for customers. Atomized grades also give lower cost options for some parts, which widens the range of customers able to use fine iron powder.
By Purity Grade, High-Purity Powder Dominates Carbonyl Iron Powder Market; Ultra-High-Purity Powder to Register Fastest Growth.
High-purity powder leads with a 51.84% share in 2025 because most inductor, molding and defense applications need iron content above 99 percent with low carbon and nitrogen. The grade balances performance and price, and suppliers can reach it consistently with standard decomposition and annealing steps. It meets the specifications used by most electronics, automotive and aerospace customers, which supports strong repeat orders. Customers can source it from several producers, which keeps pricing competitive and reduces supply risk for buyers.
Ultra-high-purity powder is anticipated to expand at a CAGR of 5.97% from 2026 to 2035. Advanced inductors for servers, medical devices and semiconductor equipment require extremely low contamination and stable magnetic behavior. Pharmaceutical customers also prefer the cleanest grades. Producers are investing in better filtration, inert handling and testing to qualify these products. Suppliers able to document contamination limits batch by batch gain a clear advantage in qualification, and customers accept higher prices for the added assurance they receive.
By Application, Powder Metallurgy Dominates Carbonyl Iron Powder Market; Electronic Components to Register Fastest Growth.
Powder metallurgy accounts for 38.46% of demand in 2025, covering metal injection molding, sintered parts and magnetic components made by pressing and sintering. Fine carbonyl iron powder gives high density, smooth finishes and accurate shapes for small parts made in large volumes. Automotive, consumer device and industrial suppliers use these processes widely, and established production lines supply steady repeat purchases. Cost pressure also favors the process because molded parts need little finishing and waste very little metal during production runs.
Electronic components are forecast to grow at a CAGR of 6.41% over 2026–2035, led by molded power inductors, electromagnetic shielding and wireless charging parts. Computing power, faster switching and smaller boards increase the number and performance of inductors in each device. Component makers in Asia are scaling lines, and powder suppliers are adding fine, coated grades for them. Demand from 5G equipment and wireless charging pads adds volume, since these designs need shielding and magnetic layers with low loss.
By End-Use Industry, Automotive Dominates Carbonyl Iron Powder Market; Healthcare and Pharmaceuticals to Register Fastest Growth.
Automotive holds 31.47% of the market in 2025 because vehicles use carbonyl iron powder in sintered and molded parts, inductors, sensors, ignition and fuel system components and magnetorheological dampers. Large production volumes and strict quality systems favor suppliers with proven consistency. Electrified models raise the powder content per vehicle, and global platforms spread approved suppliers across many plants. Qualified parts stay in production for the life of a vehicle platform, which keeps demand steady over many model years.
Healthcare and pharmaceuticals are expected to grow at a CAGR of 6.12% during 2026–2035. Iron supplements, fortified foods, medical device parts and imaging-related materials use certified pure grades. Programs to reduce iron deficiency, aging populations and expanding supplement markets raise consumption, while manufacturers invest in documentation and testing needed for regulated products. Healthcare buyers also request documentation on origin, heavy metal limits and batch traceability, which favors suppliers with certified quality systems and encourages long-term supply contracts with approved producers.
Geography Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
58.94% |
|
Europe |
Germany |
31.42% |
|
North America |
United States |
78.46% |
|
Middle East & Africa |
Saudi Arabia |
27.38% |
|
Latin America |
Brazil |
51.67% |
Asia Pacific Carbonyl Iron Powder Market
Asia Pacific is the largest and fastest growing region, with a projected CAGR of 6.33% over 2026–2035, and it accounted for 43.82% of the market in 2025. China leads the region, with a large group of producers, the biggest electronics and magnetic component industry and fast-growing metal injection molding capacity. Local suppliers offer competitive prices and are adding lines to serve both home and export customers. Government support for advanced materials, semiconductors and electronics value chains further reinforces this lead in the region.
Japan and South Korea supply advanced inductors, sensors and batteries and buy high-grade powder for them. India is building electronics assembly and automotive supply chains, while Taiwan and Southeast Asia host component and device manufacturing. Expanding vehicle output and computing hardware are expected to keep regional growth ahead of the global rate. Australia and New Zealand contribute through medical, mining and tool applications, and regional trade agreements ease cross-border sales of powders and finished components between neighboring producers. Vietnam and Malaysia are adding component plants too.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Carbonyl Iron Powder Market
Europe held 25.17% of the market in 2025. Germany leads the region, supported by an established chemical producer, a strong automotive supply base and demanding standards for powder quality. Automakers and tier suppliers use carbonyl iron powder in sensors, magnetic parts and molded components, and regional customers value secure supply and consistent specifications. The region also hosts research institutes and powder metallurgy associations that develop new grades, test methods and standards, which help keep technical leadership with established European suppliers in many applications.
France, Italy, the United Kingdom and the Nordic countries add demand from aerospace, medical devices and tool manufacturing. Strict chemical safety rules limit new plants but protect the position of established suppliers. Regional buyers also pay close attention to documented purity, traceability and environmental performance when choosing powder. Sustainability goals push producers to cut emissions in power use and gas handling, and recycling of metal powders from molding scrap is gaining attention among automotive and electronics suppliers across the region and its supply chains.
North America Carbonyl Iron Powder Market
North America accounted for 21.93% of the market in 2025, led by the United States. The U.S. market was valued at USD 41.36 Million in 2025 and is expected to register a CAGR of 5.92% during 2026–2035. Defense programs, aerospace suppliers, electronics makers and a local carbonyl iron producer sustain demand for high-purity grades, and customers value shorter supply routes. Suppliers in the region also benefit from close contact with customers in aerospace and electronics, which helps them develop custom grades and fast delivery schedules.
Canada and Mexico add demand through automotive supply chains, metal injection molding and electronics assembly. Reshoring of component manufacturing, data center build-out and investment in defense electronics support new orders. Buyers in the region qualify several sources to reduce supply risk, which helps both local and imported suppliers. Medical device makers, tool producers and a large dietary supplement industry add further demand, while funding for semiconductor and power electronics plants supports orders for fine iron powder in the coming years across the region.
Middle East & Africa Carbonyl Iron Powder Market
Middle East & Africa held 5.44% of the market in 2025. Demand is small and is met largely through imports, with Saudi Arabia, the United Arab Emirates, Israel and Turkey among the more active buyers. Industrial diversification programs, defense procurement and new electronics and tool manufacturing support regional consumption of fine iron powders. Governments are encouraging local assembly of electronics, vehicles and defense equipment, which should raise requirements for fine powders and specialty magnetic materials over the next decade and beyond.
Diamond tool makers, pharmaceutical producers and metal parts workshops form the main customer base, and distributors supply small lots of standard and high-purity grades. South Africa and Egypt add demand through mining tools and construction products. Limited local production and long shipping times keep buyers reliant on international suppliers. Pharmaceutical plants in the Gulf and North Africa are steadily expanding, and the use of iron supplements in public health programs adds a small but growing source of demand for pure grades.
Latin America Carbonyl Iron Powder Market
Latin America accounted for 3.64% of the market in 2025, with Brazil as the leading country. Automotive plants, appliance makers and a growing electronics assembly sector buy fine iron powders, mostly through importers and distributors. Mexico is the second major market, supported by vehicle assembly, auto parts and electronics plants serving North America. Local assemblers of vehicles, motorcycles and household appliances use sintered parts in large numbers, and regional trade agreements help move powders and components between producing countries in the region.
Argentina, Chile and Colombia add small volumes from tool making, mining equipment and pharmaceutical production. Currency swings, import duties and long delivery times limit wider use, so buyers keep modest stocks and favor distributors with local warehouses. Growth in automotive and electronics production is expected to broaden demand gradually. Pharmaceutical and food companies in the region purchase certified iron sources for fortified products, and public nutrition programs add steady demand for approved supplier grades. Suppliers are adding local sales and technical support.
Competitive Landscape:
The Carbonyl Iron Powder Market is moderately concentrated. A small number of specialized producers in Germany, China, the United States and Russia operate large carbonyl plants, and regional companies serve local customers with standard grades. Competition rests on particle size control, purity, coating technology, consistent quality and secure supply, and new entrants face high safety and capital barriers.
Companies pursue capacity additions, lower-cost process technology, coated and ultra-fine grade launches and long-term supply agreements with component makers.
Carbonyl Iron Powder Market Industry Leaders:
1. BASF: German chemical group and a leading global producer of carbonyl iron powder and iron pentacarbonyl.
2. Jiangxi Yuean Advanced Materials: Chinese producer of carbonyl iron powder and soft magnetic powders for inductors and molding.
3. American Carbonyl: U.S. producer of carbonyl iron micropowders and iron pentacarbonyl in Huntsville, Alabama.
4. Sintez-CIP: Russian carbonyl iron powder producer owned by Severstal.
5. American Elements: U.S. supplier of carbonyl iron powder in standard and coated grades.
Companies Covered in this Report:
-
BASF
-
Jiangxi Yuean Advanced Materials
-
American Carbonyl
-
Sintez-CIP
-
American Elements
-
Höganäs
Recent Industry Developments:
-
April 2025: Höganäs announced an investment in biochar to replace part of the fossil coal used in its iron powder production by the end of 2026.
-
February 2026: Dauch Corporation completed its acquisition of Dowlais Group, which includes GKN Powder Metallurgy.
-
April 2026: Jiangxi Yuean reported that its 6,000-tonne carbonyl iron powder project had entered operation and that phase one of its Ningxia soft magnetic powder project had started trial production.
Scope and Research Methodology
This study estimates the Carbonyl Iron Powder Market for 2025 as the base year and forecasts it through 2035. The scope covers carbonyl iron powder produced by thermal decomposition of iron pentacarbonyl, including reduced and atomized types and standard, high-purity and ultra-high-purity grades, sold for powder metallurgy, electronic components, radar absorption, diamond tools, food and pharmaceutical uses and other applications. Values are reported in USD at the producer selling price. Standard iron powders made by other routes are outside the scope. Intermediate iron pentacarbonyl sold between companies is not counted separately, and recycled or reclaimed powders are excluded from the market value.
Secondary research included company annual reports, investor presentations and filings, chemical and trade databases, regulator and customs publications, trade association statistics, product documentation, patents, and peer-reviewed and industry publications. Primary research consisted of structured interviews and surveys with executives, product and business heads, procurement managers and technical specialists across the value chain. These inputs were used to validate capacity, grade mix, pricing and adoption rates in each application. Plant data, grade specifications and shipment records supported the review of capacity utilization and product mix. Responses were compared across regions and company types so that results were not driven by one group of respondents.
Market size was built from the bottom up using producer capacity, shipment and price data, and was cross-checked from the top down against inductor, metal injection molding, vehicle and defense indicators. Triangulation across these views fixed the base year value. Forecasts consider electronics demand, vehicle electrification, safety regulation, process technology and macroeconomic conditions, and segment and regional shares were assigned from consumption patterns. An analyst quality review checked consistency before release. Price assumptions were tested under alternative scenarios for energy cost, feedstock handling rules and exchange rates, and application demand was modeled from device, vehicle and component output. Currency effects were treated at constant rates.
Carbonyl Iron Powder Market Report Scope:
|
Report Attributes |
Details |
|---|---|
|
Market Size in 2025 |
USD 240.35 Million |
|
Market Size by 2035 |
USD 404.37 Million |
|
CAGR |
CAGR of 5.34% From 2026 to 2035 |
|
Base Year |
2025 |
|
Forecast Period |
2026-2035 |
|
Historical Data |
2022-2024 |
|
Report Scope & Coverage |
Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
|
Key Segments |
• By Type (Reduced and Atomized) |
|
Regional Analysis/Coverage |
North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
|
Company Profiles |
Jiangxi Yuean Advanced Materials, American Carbonyl, Sintez-CIP, American Elements, Höganäs |

Frequently Asked Questions
Asia Pacific is also expected to grow fastest, at a CAGR of 6.33% during 2026–2035.
The Carbonyl Iron Powder Market was valued at USD 240.35 Million in 2025 and is expected to reach USD 404.37 Million by 2035.
The market is projected to grow at a CAGR of 5.34% during 2026–2035.
Reduced powder, high-purity grades, powder metallurgy and automotive end use lead their segments.
Atomized powder, ultra-high-purity grades, electronic components and healthcare are the fastest growing.
BASF, Jiangxi Yuean, American Carbonyl, Sintez-CIP and American Elements are among the major players.
Hazardous feedstock, high production cost, concentrated supply and long qualification cycles restrain faster expansion.
Asia Pacific leads, with a 43.82% share in 2025, supported by large electronics and powder metallurgy industries.
