
Field Communication Devices Market Report Scope & Overview:
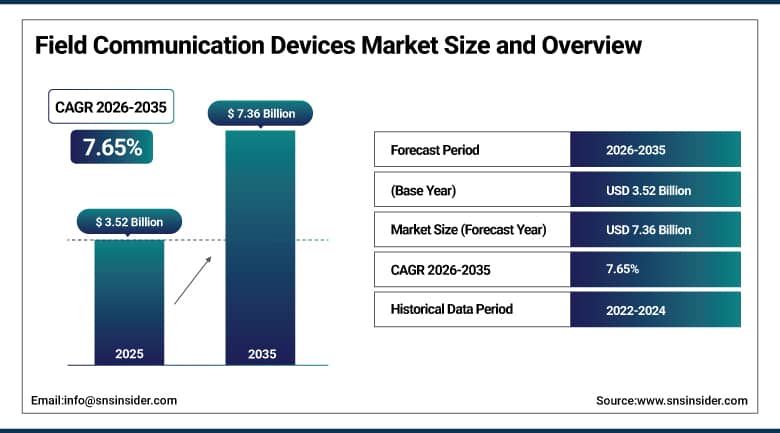
The Field Communication Devices Market was valued at USD 3.52 Billion in 2025 and is expected to reach USD 7.36 Billion by 2035, growing at a CAGR of 7.65% from 2026-2035.
Field communication devices constitute an essential category within industrial automation, encompassing handheld communicators, configuration tools, and wireless gateways used to configure, calibrate, and diagnose field instrumentation across process manufacturing facilities. Rising industrial automation investment, expanding smart grid and energy infrastructure upgrades, and growing adoption of Industrial Internet of Things architectures continue to broaden the facility base requiring these tools. Oil and gas operators, chemical manufacturers, and an expanding base of water and wastewater utilities rely on field communication devices to maintain reliable instrument performance, reduce unplanned downtime, and support predictive maintenance programs. Sustained growth is being shaped by continued migration toward wireless communication protocols, rising integration between field devices and centralized asset management software, and expanding deployment across harsh, hazardous-area industrial environments, reinforcing this market's position as a durable, technology-led segment of the wider industrial instrumentation industry. Growing emphasis on cybersecurity for industrial control systems further reinforces vendor investment in secure, authenticated communication protocols across both wired and wireless device categories.
In 2025, Emerson extended its range of AMS Trex Device Communicator, which now included wireless HART capabilities and cloud-enabled diagnostics that allowed for sharing data within handheld field communication devices being utilized by maintenance personnel in the process industries. Emerson commented that the continued investment was in response to high customer demand for fast and reliable instrument configuration in hazardous conditions.
To Get More Information On Field Communication Devices Market - Request Free Sample Report
Field Communication Devices Market Trends
-
Growing migration from wired to wireless communication protocols across new instrumentation installations.
-
Rising integration between field devices and centralized predictive maintenance and asset management software.
-
Expanding deployment of HART-compatible devices supporting backward compatibility with installed instrument bases.
-
Increasing adoption of Modbus-based communication supporting cost-effective, open-architecture installations.
-
Rising demand for ruggedized, intrinsically safe devices certified for hazardous industrial area deployment.
-
Growing smart grid and energy infrastructure modernization driving power generation sector device demand.
U.S. Field Communication Devices Market Overview
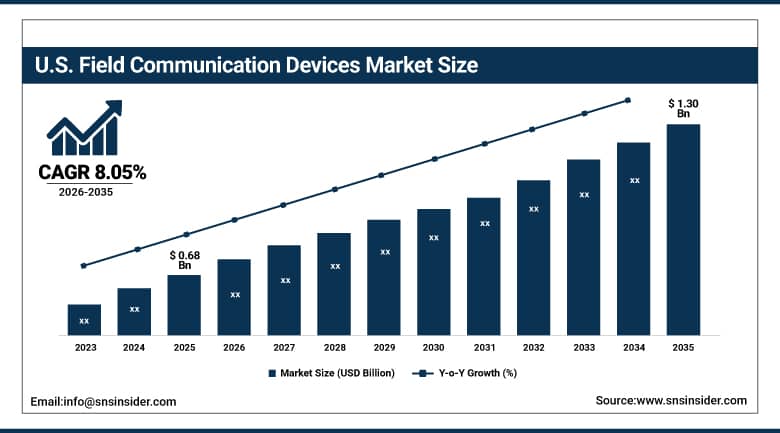
The U.S. Field Communication Devices Market was valued at USD 0.68 Billion in 2025 and is expected to reach USD 1.30 Billion by 2035, growing at a CAGR of 8.05% from 2026-2035.
U.S. demand continues to be underpinned by sustained oil and gas, chemical, and power generation facility investment requiring reliable field instrumentation configuration and diagnostic capability across the country's process industry base. Leading manufacturers continue expanding their wireless and cloud-connected device portfolios, addressing rising customer demand for remote diagnostics and predictive maintenance integration, while continued investment in intrinsically safe device certification keeps strengthening competitive positioning. Growing smart grid modernization investment further supports market expansion across the U.S. as utilities increasingly specify advanced field communication capability across transmission and distribution infrastructure nationwide.
In 2025, Honeywell continued expanding its field device configuration and diagnostic software portfolio, integrating wireless connectivity directly into its process automation instrumentation lineup serving oil, gas, and chemical processing customers. The company stated the continued investment addresses growing customer demand for simplified, remote instrument commissioning across distributed industrial sites.
Field Communication Devices Market Segment Analysis
-
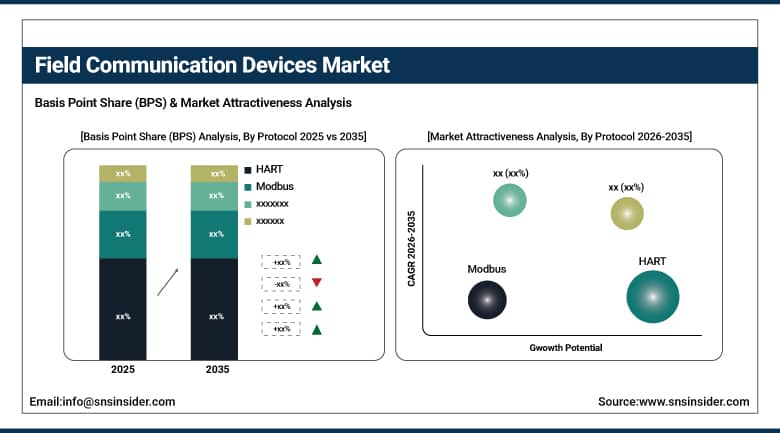
By Protocol, the HART segment dominated the market with a 40.32% share in 2025, while the Modbus segment is the fastest growing with a CAGR of 7.50% during 2026-2035.
-
By Product, the Wired Communication Devices segment dominated the market with a 60.35% share in 2025, while the Wireless Communication Devices segment is the fastest growing with a CAGR of 9.30% during 2026-2035.
-
By Application, the Oil & Gas segment dominated the market with a 32.60% share in 2025, while the Water & Wastewater segment is the fastest growing with a CAGR of 8.40% during 2026-2035.
-
By End-User, the Process Industries segment dominated the market with a 68.90% share in 2025, while the Discrete Industries segment is the fastest growing with a CAGR of 7.90% during 2026-2035.
By Protocol, HART Dominates the Field Communication Devices Market and Modbus Grows Fastest
HART-oriented devices continue to lead the protocol segment, as these devices remain compatible with the massive installed base of field instrumentation deployed across process industries over recent decades while providing dependable performance in routine process monitoring applications. This backward compatibility advantage continues to anchor HART as the default protocol specification across brownfield installations and ongoing maintenance programs at facilities that adopted the standard during its decades of market leadership.
Modbus is experiencing the highest rate of growth amongst all protocol types thanks to its open-source and license-free framework that keeps on proving its value to companies that are looking for affordable solutions that do not require any kind of licensing. Because of the minimal licensing requirements and widespread vendor support of Modbus protocol for water treatment systems, building management, and renewable energy facilities, its market share of device usage is growing.
By Product, Wired Dominates the Field Communication Devices Market and Wireless Grows Fastest
Wired communication devices continue to command the largest product share, a position built on their proven reliability, established performance standards, and widespread application across industrial and power generation facilities where consistent, interference-free signal transmission remains critical. Facility operators favour this product category precisely because it delivers dependable, well-understood performance across the broadest range of hazardous and harsh-environment industrial applications, sustaining recurring replacement and upgrade demand across established process facility installations worldwide.
Wireless communication devices are emerging as the fastest-growing product category, reflecting rising demand for flexible, lower-installation-cost connectivity across retrofit projects and remote monitoring points where running physical cabling proves impractical or prohibitively expensive. As industrial wireless protocols continue maturing in reliability and security, facilities increasingly specify wireless devices for new monitoring points and expanding Industrial Internet of Things initiatives, allowing this category to close the gap with wired alternatives in overall market demand.
By Application, Oil & Gas Dominates the Field Communication Devices Market and Water & Wastewater Grows Fastest
Oil & Gas is the biggest end-user application for field communication equipment due to the massive and geographically widespread instrumentation deployed within the industry, covering upstream oil & gas extraction, midstream oil & gas transportation via pipelines, and downstream oil & gas refining activities, all of which demand regular calibration and diagnostics in order to function safely and effectively. This magnitude and importance will keep oil & gas the dominant application segment going forward.
Water and wastewater applications are expanding at the fastest pace among application categories, driven by rising global infrastructure investment addressing ageing municipal treatment facilities and growing regulatory emphasis on water quality monitoring. As utilities worldwide continue modernizing treatment plant instrumentation to meet tightening environmental compliance standards, this application category continues to close the gap with more established industrial segments in overall device demand.
By End-User, Process Industries Dominates the Field Communication Devices Market and Discrete Industries Grows Fastest
Process industries account for the substantial majority of overall device demand, given the continuous, instrumentation-intensive nature of oil and gas, chemical, and power generation operations that require constant monitoring and periodic recalibration of pressure, temperature, flow, and level instrumentation across sprawling facility footprints. This foundational instrumentation density continues to sustain process industries as the dominant end-user category across the broader market.
Discrete industries are expanding at the fastest pace among end-user categories, reflecting growing automation investment across manufacturing sectors including automotive and electronics production, where increasing adoption of smart factory initiatives continues to expand the addressable base of instrumentation requiring field communication and diagnostic support. As discrete manufacturers increasingly adopt continuous-process-style instrumentation monitoring practices, this end-user category continues to close the gap with process industries in overall market demand.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
Asia Pacific |
China |
41.27% |
|
North America |
United States |
77.62% |
|
Europe |
Germany |
33.84% |
|
Latin America |
Brazil |
46.19% |
|
Middle East & Africa |
United Arab Emirates |
28.53% |
Asia Pacific Field Communication Devices Market Insights
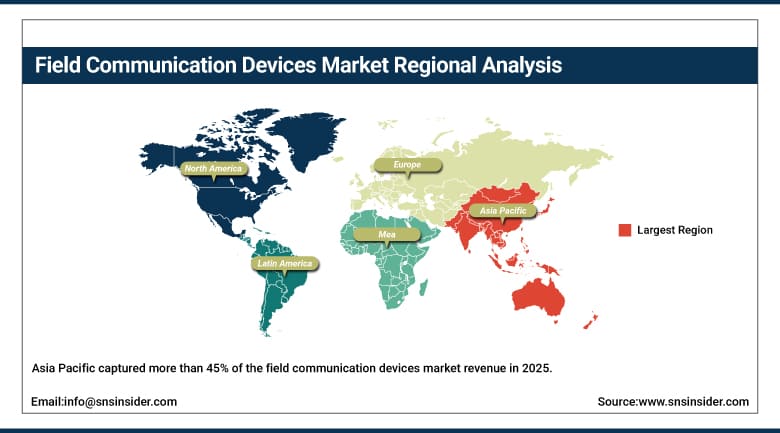
Asia Pacific captured more than 45% of the field communication devices market revenue in 2025 as the dominant market due to the large base of process manufacturing industries in the region as well as huge investments in industrial automation in China, India, and the rest of manufacturing centers of Southeast Asia. China is the key player in the region owing to the rapid growth in capacity of local chemical, oil & gas, and power plants.
India's expanding industrial manufacturing base and growing water infrastructure investment continue adding meaningful regional growth as domestic facilities extend field communication capability into previously underserved process applications. Japan and South Korea contribute further depth through established, technically advanced manufacturing sectors, positioning the wider region to sustain the largest revenue base of any global market through the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Field Communication Devices Market Insights
Registering a projected CAGR of 8.60% during 2026-2035, North America is expected to be the fastest-growing region, supported by substantial smart grid modernization investment and sustained oil and gas sector capital spending across the United States and Canada. The United States shapes regional demand through its concentration of leading field communication device manufacturers and extensive energy infrastructure requiring continuous instrumentation support.
Canada contributes additional regional demand through its participation in North American energy and manufacturing supply chains. Continued investment in wireless and cloud-connected device technology is expected to support North America's accelerating growth trajectory through the forecast period, even as the region's overall revenue base remains smaller than Asia Pacific's established manufacturing-driven market.
Europe Field Communication Devices Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established field instrumentation manufacturers and continued advancement in wireless and intrinsically safe device technology developed for chemical and pharmaceutical applications. Germany's substantial industrial manufacturing base anchors regional demand, supported by a well-developed regulatory framework favouring early adoption of next-generation instrumentation technology.
The United Kingdom, France, and other major European markets contribute consistent demand as regional process industries continue extending advanced field communication technology into routine maintenance practice, supporting steady regional market development across chemical, pharmaceutical, and energy sector applications.
MEA & Latin America Field Communication Devices Market Insights
Latin America's market is anchored by Brazil, where a sizeable domestic oil and gas and chemical processing sector sustains steady device demand across both upstream and downstream operations. Mexico contributes further incremental growth as industrial manufacturing activity continues expanding across the broader region.
The MEA region remains significant from a strategic perspective, while demand is centered in GCC countries like the UAE, where heavy investments in oil and gas infrastructure continue to fuel the need for dependable field instrument communication solutions. South Africa remains the mainstay of demand on the continent due to the relatively advanced infrastructure in its industrial manufacturing base.
Market Dynamics
Growth Drivers: Industrial Automation and Smart Grid Modernization
Industrial automation emerges as a key factor driving growth due to continued investments being made in instrumentation that needs reliable configurability, calibration, and diagnostics by process manufacturing sites globally. Such trends are augmented by the growth in energy infrastructure development and smart grid upgrades as utilities in various key regions continue their efforts to upgrade transmission and distribution instrumentation towards more reliable and digitally connected power systems.
The emergence of Industrial Internet of Things and smart manufacturing solutions serves as another key demand factor due to increased deployments of field devices with asset management and predictive maintenance systems. Increased use of wireless communications protocols in harsh environments becomes another key factor driving market growth due to reduced cost requirements for expanding networks of monitoring points.
Restraints: High Replacement Costs and Protocol Fragmentation
High costs associated with replacements and upgrades have been a real limitation on market growth since the transition of existing wired instruments into wireless or multi-protocol instruments requires heavy expenditure of funds that can be hard to justify for budgetary constraints. These costs are an even greater burden on smaller facilities and operators in developing countries because the total cost of modernization exceeds their budget.
Protocol fragmentation across differing communication standards presents a further restraint, as facilities operating mixed HART, PROFIBUS, Modbus, and Foundation Fieldbus installations continue to face interoperability challenges when integrating devices from multiple vendors and generations. This complexity requires manufacturers to sustain substantial ongoing multi-protocol compatibility investment that can meaningfully complicate product development and support across differing customer installation environments.
Opportunities: Wireless Protocol Advancement and Predictive Maintenance Integration
Continued advancement of wireless communication protocols offers a substantial opportunity, as manufacturers developing more secure, reliable wireless field devices stand to capture meaningful new demand from facilities seeking lower-cost connectivity for expanding monitoring networks. The continued integration of field devices with predictive maintenance and cloud-based asset management platforms presents a further avenue for growth, as facilities increasingly value real-time diagnostic data supporting proactive maintenance scheduling over conventional reactive repair approaches.
Recent Developments:
-
2025: Pepperl+Fuchs continued expanding its intrinsically safe field communication device portfolio, supporting hazardous-area instrumentation applications across oil, gas, and chemical processing customers.
-
2025: Moxa continued developing industrial wireless gateway and communication device solutions, supporting Industrial Internet of Things connectivity across process and discrete manufacturing facilities.
-
2025: Advantech continued expanding its industrial communication device portfolio, addressing rising demand for edge connectivity solutions across smart manufacturing deployments.
-
2025: WAGO Kontakttechnik continued developing field-level communication and automation device solutions, supporting process industry customers transitioning toward integrated digital instrumentation platforms.
Field Communication Devices Market Key Players
-
Emerson Electric Co.
-
Honeywell International Inc.
-
Pepperl+Fuchs SE
-
Moxa Inc.
-
Advantech Co., Ltd.
-
Belden Inc.
-
Banner Engineering Corp.
-
National Instruments Corporation
-
Hitachi, Ltd.
-
WAGO Kontakttechnik GmbH & Co. KG
-
ABB Ltd.
-
Siemens AG
-
Schneider Electric SE
-
Yokogawa Electric Corporation
-
Endress+Hauser Group
-
Rockwell Automation, Inc.
-
Phoenix Contact GmbH & Co. KG
-
Krohne Group
-
Vega Grieshaber KG
-
MTL Instruments (Honeywell)
Field Communication Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.3 Billion |
| Market Size by 2035 | USD 16.7 Billion |
| CAGR | CAGR of 14.77% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (RFID, GPS, Sensors) • By Product (Smart Collar, Smart Camera, Smart Harness and Vest, Others) • By Animal Type (Dogs, Cats, Other Animals) • By Application (Identification & Tracking, Behavior Monitoring & Control, Facilitation, Safety & Security, Medical Diagnosis & Treatment) • By Sales Channel (Online, Offline) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Avid Identification Systems, Inc., Datamars, Felcana, FitBark Inc., Garmin Ltd., GoPro Inc., LATSEN (Pawfit), Link My Pet, Loc8tor Ltd., Mars, Incorporated (Whistle Labs Inc.), PETFON, PetPace, PetTech.co.uk Ltd., Tractive GmbH, Indiegogo Inc., PawTrax Limited, Dairymaster USA Inc., Afimilk Ltd., IceRobotics Ltd., Dogtra, DogTelligent Inc., Otto Petcare Systems, Pod Trackers. |

Frequently Asked Questions
Key players include Emerson Electric, Honeywell International, Pepperl+Fuchs, Moxa, Advantech, Belden, Banner Engineering, National Instruments, Hitachi, and WAGO Kontakttechnik, among others.
Continued advancement of wireless communication protocols and the continued integration of field devices with predictive maintenance platforms represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by increasing industrial automation, combined with expanding energy infrastructure and smart grid upgradation projects.
By Protocol, HART dominated the market with a 40.32% share in 2025, reflecting its compatibility with the massive installed base of existing field instrumentation.
Asia Pacific accounted for over 45% of global revenue in 2025, supported by the region's extensive process manufacturing base and rapidly expanding industrial automation investment.
