
Global Aerospace & Defense Market Report Scope & Overview:
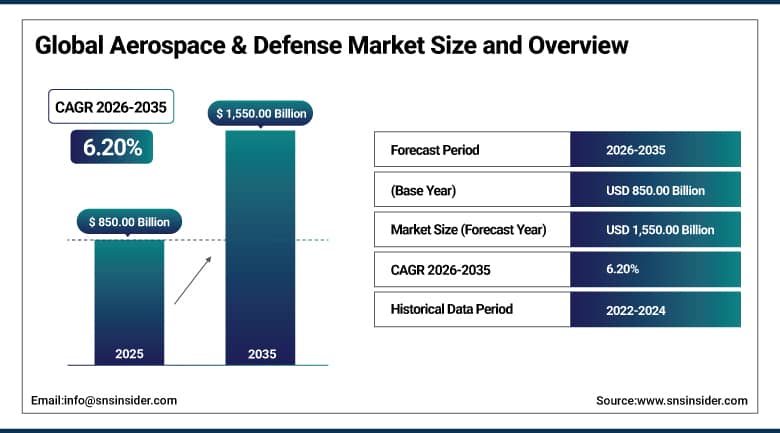
The Global Aerospace & Defense Market was valued at USD 850.00 Billion in 2025 and is expected to reach USD 1,550.00 Billion by 2035, growing at a CAGR of 6.20% from 2026–2035.
Aerospace and defense sits behind almost every major national security decision and every commercial jetliner order placed anywhere in the world, spanning fighter jets, missile systems, satellites, and the passenger aircraft that airlines depend on to keep growing their networks. Very few industries operate on the same timescale: a defense procurement program can run for fifteen to thirty-five years from initial contract to final sustainment activity, and a single fighter aircraft platform can still be in active production more than two decades after its first flight. Geopolitical tension and commercial air travel recovery have both been pushing demand upward simultaneously, a combination that doesn't happen often in this industry's history.
Lockheed Martin delivered 191 F-35 Lightning II fighter jets in 2025, shattering the program's previous annual delivery record of 142 aircraft, while finalizing agreement with the F-35 Joint Program Office in September for up to 296 additional aircraft worth $24 billion, the largest production contract in the program's history. The F-35 alone illustrates the scale this industry operates at: a single aircraft program, still in production more than two decades after its first flight, generating tens of billions of dollars in contract value in a single year and drawing new international buyers, Singapore and the United Kingdom both expanded their F-35 orders in 2025, faster than the program can build jets.
To Get More Information On Global Aerospace & Defense Market - Request Free Sample Report
Global Aerospace & Defense Market Trends
-
Defense modernization spending continues concentrating on advanced technology, with governments in more than 60 countries funding upgrades to fighter aircraft, air-defense systems, and battlefield communication networks simultaneously rather than one platform generation at a time.
-
Autonomous and unmanned systems continue expanding beyond surveillance roles into strike, logistics, and combat support functions, with drone adoption in defense applications rising sharply over the past five years.
-
Commercial aviation fleet renewal is accelerating as airlines prioritize fuel-efficient aircraft to control operating costs, driving sustained order backlogs at both Boeing and Airbus well into the next decade.
-
Space systems investment continues expanding beyond traditional government space agencies, with private operators and commercial launch providers scaling satellite constellation deployment and space-based communication networks.
-
Hypersonic and directed-energy weapons programs are claiming a growing share of defense research and development budgets, reflecting a genuine technology race among the largest defense-spending nations.
U.S. Global Aerospace & Defense Market Outlook
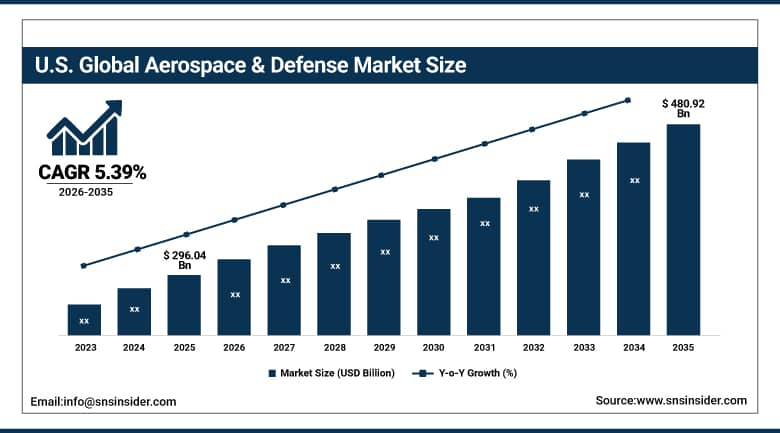
The U.S. Global Aerospace & Defense Market was valued at approximately USD 296.04 Billion in 2025 and is expected to reach approximately USD 480.92 Billion by 2035, growing at a CAGR of approximately 5.39%.
Demand in the United States is anchored by the world's largest concentration of prime defense contractors alongside sustained federal defense budget growth prioritizing fighter aircraft, missile defense, and space systems modernization. A majority of domestic defense spending continues flowing toward advanced technology programs, including stealth aircraft and next-generation missile defense, while commercial airlines simultaneously accelerate fleet renewal to replace aging, less fuel-efficient jets. That dual engine, sustained defense procurement running alongside commercial aviation recovery, gives the U.S. market a demand base that most other countries' aerospace and defense sectors can't match in scale or depth.
Boeing surpassed Airbus in commercial jetliner orders for the first time since 2018, closing 2025 with 1,167 gross orders against Airbus's roughly 1,000, while quarterly commercial aircraft deliveries jumped 180.7% year over year as the company continued recovering from years of production and certification setbacks. Boeing's own long-term forecast projects a $4.7 trillion market opportunity for commercial aviation support and services over the 2025-2044 period, underscoring how much of the U.S. aerospace industry's growth story now depends on sustaining this delivery recovery rather than simply winning new orders.
Global Aerospace & Defense Market Segment Analysis
-
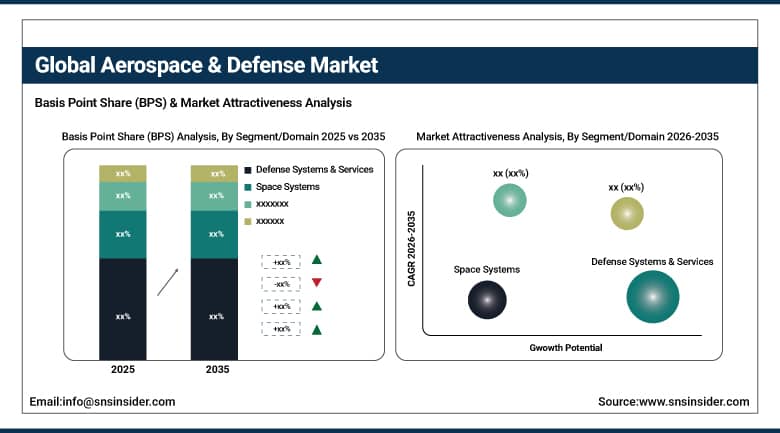
By Segment/Domain, the Defense Systems & Services segment dominated the Global Aerospace & Defense Market with approximately 57.60% share in 2025, while the Space Systems segment is the fastest growing with a CAGR of approximately 9.30%.
-
By Platform, the Commercial Aircraft segment dominated the Global Aerospace & Defense Market with approximately 25.20% share in 2025, while the Unmanned Systems segment is the fastest growing with a CAGR of approximately 12.40%.
-
By Component, the Weapon Systems segment dominated the Global Aerospace & Defense Market with approximately 28.60% share in 2025, while the Avionics segment is the fastest growing with a CAGR of approximately 9.80%.
-
By Operation, the Manned segment dominated the Global Aerospace & Defense Market with approximately 82.40% share in 2025, while the Autonomous/Unmanned segment is the fastest growing with a CAGR of approximately 13.60%.
-
By Application, the Military & Defense Operations segment dominated the Global Aerospace & Defense Market with approximately 52.30% share in 2025, while the Space Exploration & Satellites segment is the fastest growing with a CAGR of approximately 9.70%.
By Segment/Domain, defense systems & services dominates, space systems grows fastest
Defense systems and services held the largest share of the segment/domain category in 2025, covering military aircraft, naval platforms, munitions, and missile systems that together represent the industry's single largest and most stable revenue base. Sustained government defense budgets across dozens of countries, combined with the multi-decade sustainment tail that follows every major weapons platform once fielded, keep this segment generating consistent, predictable revenue that commercial aerospace's more cyclical order book doesn't always match. Long procurement cycles spanning fifteen to thirty-five years give contractors in this segment unusually strong revenue visibility relative to most other capital-intensive global industries.
Space systems are growing fastest as governments and private operators alike expand satellite constellations, launch services, and space-based communication networks at a pace the industry hasn't previously sustained. Rising investment in observation, navigation, and defense-oriented space missions is boosting demand for spacecraft, payloads, and launch vehicles well beyond the traditional government space agency customer base. Commercial launch providers scaling reusable rocket technology have meaningfully lowered the cost of reaching orbit, opening the segment to a broader range of both government and private buyers than existed even a decade ago.
By Platform, commercial aircraft dominates, unmanned systems grows fastest
Commercial aircraft held the largest share of the platform segment in 2025, driven by rising global passenger traffic, fleet renewal programs, and growing airline demand for more fuel-efficient jets that reduce operating costs over an aircraft's decades-long service life. The large installed base of active commercial aircraft worldwide, combined with continuous maintenance, upgrade, and new-delivery demand, keeps this platform category generating the industry's highest production volumes by unit count. Airlines' accelerating replacement of older, less efficient aircraft continues reinforcing commercial aircraft's dominant position within the broader platform mix.
Unmanned systems are growing fastest as military drone adoption continues expanding well beyond surveillance into strike, logistics, and combat support roles that manned platforms previously handled exclusively. Rising investment in autonomous fighter jet and drone development across multiple defense budgets reflects how central unmanned capability has become to modern military modernization planning. Falling per-unit cost relative to comparable manned platforms, combined with reduced risk to aircrew, gives unmanned systems a compelling value proposition that's accelerating adoption across an increasing number of national defense programs worldwide.
By Component, weapon systems dominates, avionics grows fastest
Weapon systems held the largest share of the component segment in 2025, spanning missiles, munitions, and integrated fire-control technology that represent both a significant share of individual platform cost and a recurring revenue stream through ongoing munitions replenishment. Sustained defense budgets prioritizing missile defense and precision-guided munitions continue reinforcing this component category's dominant position within overall program spending. Multi-year munitions production contracts, often running into the tens of billions of dollars for a single award, give this component segment unusually large individual deal sizes relative to most other categories in the industry.
Avionics is growing fastest as AI-enabled systems and advanced sensor fusion technology become standard requirements across both new-build and modernization programs for military and commercial platforms alike. Rising investment in AI-enabled weapons systems, now representing a meaningful and growing share of total defense spending, is pulling development capital toward this component category faster than the broader, more mature weapon systems segment is growing. Block modernization programs that upgrade existing airframes with new avionics packages are extending this growth well beyond new-aircraft production alone.
By Operation, manned dominates, autonomous/unmanned grows fastest
Manned operation held the large majority of the operation segment in 2025, reflecting the continued dominance of piloted aircraft and crewed systems across both commercial aviation, where autonomous passenger flight remains far from regulatory approval, and the majority of current military aviation programs. Established certification pathways, decades of operational safety data, and deep pilot training infrastructure all continue supporting manned platforms as the default choice across most current aerospace and defense procurement programs.
Autonomous and unmanned operation is growing fastest as defense modernization programs increasingly prioritize drone and autonomous vehicle capability across surveillance, logistics, and combat support missions. Growing confidence in autonomous system reliability, combined with the reduced aircrew risk and lower operating cost these platforms offer, continues pulling development investment and program funding toward this operation category faster than manned systems are growing. Expanding adoption of autonomous vehicles and drones across defense applications over the past five years reflects how quickly this shift has accelerated relative to the industry's historically slow pace of operational change.
By Application, military & defense operations dominates, space exploration & satellites grows fastest
Military and defense operations accounted for the largest application share in 2025, driven by sustained investment in mission-critical platforms including fighter aircraft, air-defense systems, surveillance assets, and battlefield communication networks across land, air, sea, and space missions. That broad operational footprint across every military domain ensures consistent demand for modernization and readiness programs regardless of which specific platform or technology generation is currently in procurement. Sustained global defense budget growth continues reinforcing this application's dominant position within the broader aerospace and defense revenue mix.
Space exploration and satellites is the fastest-growing application as expanding investment in satellite constellations, launch programs, and space-based communication systems accelerates across both government and commercial customers. Increasing reliance on space-based assets for navigation, communication, and defense-oriented observation missions continues pulling this application's growth well ahead of the broader, more established military and defense operations category. Rising launch cadence, more than doubling over the past several years, reflects genuinely accelerating commercial and government investment in space infrastructure rather than a temporary spike in activity.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.64% |
|
Europe |
France |
26.42% |
|
Asia Pacific |
China |
37.85% |
|
Latin America |
Brazil |
34.92% |
|
Middle East & Africa |
Saudi Arabia |
31.27% |
North America Global Aerospace & Defense Market Insights
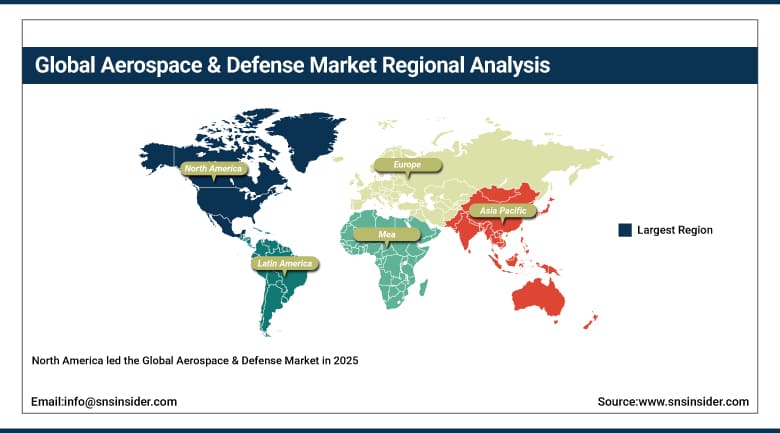
North America led the Global Aerospace & Defense Market in 2025, anchored by the United States' position as home to the world's largest concentration of prime defense contractors and the deepest, most sustained government defense procurement budget of any single national market. That combination of contractor density and procurement scale gives the region a level of industrial depth that no other market currently matches, spanning fighter aircraft, missile systems, space platforms, and commercial jetliner manufacturing all within the same national industrial base. Continued U.S. government prioritization of defense and space system modernization keeps reinforcing this leading position.
Canada contributes a meaningful share through its own defense procurement programs and aerospace manufacturing sector, particularly in regional aircraft and defense electronics, while Mexico's market continues expanding alongside growing aerospace component manufacturing tied to North American supply chain integration. Cross-border supplier relationships tie much of North American demand together, with major U.S. primes routinely sourcing components and subassemblies from both Canadian and Mexican manufacturing facilities as part of an integrated regional industrial base.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Global Aerospace & Defense Market Insights
Asia Pacific is expected to register the fastest regional growth through 2035, driven by rising defense budgets across the region's largest economies and rapidly expanding domestic aerospace manufacturing capability that reduces historical dependence on Western suppliers. China's continued military modernization program and growing domestic commercial aircraft manufacturing ambitions give the region substantial baseline demand, while broader regional geopolitical tension continues reinforcing sustained government defense investment across multiple national budgets simultaneously.
India's expanding defense procurement and growing domestic aerospace manufacturing sector are drawing significant new investment, supported by government policy favoring indigenous production over imported systems. Japan and South Korea represent more mature, technology-forward markets with established domestic defense contractors and deep alliance relationships with U.S. suppliers, while Southeast Asian markets continue expanding defense budgets in response to regional security concerns, reinforcing the broader Asia Pacific growth trajectory.
Europe Global Aerospace & Defense Market Insights
Europe represents a mature, technically advanced aerospace and defense market, anchored by France's position as home to Airbus, Dassault Aviation, Thales, and Safran, giving the country one of the deepest aerospace industrial bases anywhere in the world. Rising European defense spending, driven substantially by ongoing regional security concerns, continues pushing member states toward increased domestic procurement and modernization programs across fighter aircraft, air-defense systems, and naval platforms.
The United Kingdom, Germany, and Italy contribute significant additional manufacturing and procurement activity, each hosting major defense contractors and substantial commercial aerospace supply chain presence. Growing European commitment to strategic autonomy in defense procurement, reducing reliance on non-European suppliers for critical systems, continues shaping national and EU-level investment priorities across the region's largest aerospace and defense markets.
MEA & Latin America Global Aerospace & Defense Market Insights
The Middle East and Africa host a strategically significant share of the global aerospace and defense market, with Saudi Arabia driving substantial demand through large-scale defense procurement and growing domestic aerospace manufacturing ambitions tied to the country's broader economic diversification strategy. The UAE contributes meaningful additional demand through its own defense modernization programs and growing role as a regional aerospace maintenance and logistics hub serving customers across the broader Middle East and African markets.
Latin America is a growing market led by Brazil, home to Embraer's substantial commercial and regional aircraft manufacturing operations and a domestic defense industrial base serving both national and export markets. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing aerospace component manufacturing sectors and defense modernization programs responding to evolving regional security priorities.
Market Dynamics
Growth Drivers: Geopolitical tension and commercial aviation recovery fueling adoption
Rising geopolitical tension worldwide is one of the clearest forces behind rising aerospace and defense demand, as governments across more than 60 countries fund sustained modernization programs spanning fighter aircraft, missile defense, and battlefield communication networks simultaneously. That elevated tension has shifted defense procurement from a discretionary, cyclical budget item into a sustained strategic priority in most major economies, giving the industry a demand base that's proven considerably more resilient through recent economic cycles than most other capital-intensive global sectors have experienced.
Recovery and continued expansion of commercial aviation adds a second major driver, as rising global passenger traffic and airline fleet renewal programs sustain strong order backlogs at both Boeing and Airbus well into the next decade. Airlines' accelerating replacement of older, less fuel-efficient aircraft with newer, more economical models continues reinforcing this demand base, particularly as fuel costs and emissions regulation both push operators toward more efficient fleets regardless of near-term travel demand fluctuations.
Restraints: Supply chain constraints and certification headwinds limiting production speed
Supply chain and industrial constraints remain a genuine restraint across the industry, since both commercial and defense aircraft production depend on deeply specialized component suppliers whose own capacity expansion often lags behind surging order demand. That bottleneck has repeatedly limited how quickly prime contractors can convert record order backlogs into actual delivered aircraft, constraining revenue recognition even when underlying demand remains exceptionally strong across nearly every major program.
Certification and quality control headwinds add a further restraint, as recent high-profile production and safety issues across the commercial aviation sector have intensified regulatory scrutiny and extended certification timelines for new aircraft programs. That heightened oversight, while ultimately beneficial for safety, has meaningfully slowed the pace at which manufacturers can bring new platforms to market, adding real cost and schedule risk that wasn't as pronounced in the industry's regulatory environment a decade ago.
Opportunities: Space systems expansion and autonomous defense technology opening new growth avenues
Expanding space systems investment offers manufacturers and technology providers a genuinely significant opportunity, as governments and private operators alike scale satellite constellation deployment, launch services, and space-based communication infrastructure well beyond the traditional government space agency customer base. Companies that build strong commercial space capability alongside their traditional government relationships are positioned to capture disproportionate growth as this segment continues expanding faster than the broader aerospace and defense market overall.
Autonomous and AI-enabled defense technology represents a second significant opportunity, as growing confidence in unmanned system reliability continues pulling development investment toward drone and autonomous vehicle capability across surveillance, logistics, and combat support missions. Companies that build genuine autonomous systems expertise, spanning both hardware platforms and the AI-enabled software that makes them operationally useful, are positioned to capture premium program funding as defense modernization priorities continue shifting toward this capability.
Recent Developments:
-
November 26, 2025: Boeing secured an approximately $4.7 billion foreign military sales contract for AH-64E Apache helicopters, with Poland among the international customers.
-
December 23, 2025: Boeing was awarded a $2.04 billion contract for the B-52 Commercial Engine Replacement Program.
-
April 1, 2025: Lockheed Martin received foreign military sales notification for an approximately $5.6 billion F-16 Block 70/72 sale to the Philippines.
-
December 23, 2025: Lockheed Martin's C-130J Super Hercules contract ceiling was raised to approximately $25 billion.
Global Aerospace & Defense Market Key Players
-
Lockheed Martin Corporation
-
The Boeing Company
-
Airbus SE
-
Northrop Grumman Corporation
-
RTX Corporation
-
General Dynamics Corporation
-
BAE Systems plc
-
Thales Group
-
Safran SA
-
GE Aerospace
-
Kawasaki Heavy Industries, Ltd.
-
L3Harris Technologies, Inc.
-
Leonardo S.p.A.
-
Honeywell International Inc.
-
Textron Inc.
-
Rolls-Royce Holdings plc
-
Elbit Systems Ltd.
-
Dassault Aviation SA
-
Mitsubishi Heavy Industries, Ltd.
-
Hindustan Aeronautics Limited
Global Aerospace & Defense Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 850.0 Billion |
| Market Size by 2035 | USD 1550.0 Billion |
| CAGR | CAGR of 6.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Segment/Domain (Defense Systems & Services, Commercial Aerospace, Space Systems, Others) • by Platform (Commercial Aircraft, Military Aircraft, Rotorcraft/Helicopters, Unmanned Systems, Space Systems, Others) • by Component (Airframe, Avionics, Propulsion/Engines, Weapon Systems, Others) • by Operation (Manned, Autonomous/Unmanned) • by Application (Commercial Aviation, Military & Defense Operations, Space Exploration & Satellites, Others) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Lockheed Martin Corporation, The Boeing Company, Airbus SE, Northrop Grumman Corporation, RTX Corporation, General Dynamics Corporation, BAE Systems plc, Thales Group, Safran SA, GE Aerospace, Kawasaki Heavy Industries, Ltd., L3Harris Technologies Inc., Leonardo S.p.A., Honeywell International Inc., Textron Inc., Rolls-Royce Holdings plc, Elbit Systems Ltd., Dassault Aviation SA, Mitsubishi Heavy Industries, Ltd., Hindustan Aeronautics Limited |
Frequently Asked Questions
Key players in the Global Aerospace & Defense Market include Lockheed Martin Corporation, The Boeing Company, Airbus SE, Northrop Grumman Corporation, and RTX Corporation, among others.
Key opportunities in the Global Aerospace & Defense Market include expanding space systems investment beyond traditional government space agencies and autonomous, AI-enabled defense technology across surveillance, logistics, and combat support missions.
The market is driven by rising geopolitical tension prompting sustained defense modernization across more than 60 countries, combined with continued recovery and expansion of commercial aviation fleet renewal.
The Defense Systems & Services segment dominated the Global Aerospace & Defense Market, accounting for approximately 57.60% market share.
The North America region dominated the Global Aerospace & Defense Market in 2025 with an 81.64% share within the region, driven by the world's largest concentration of prime defense contractors and sustained federal defense procurement.
