
Industrial Radiography Market Report Scope & Overview:
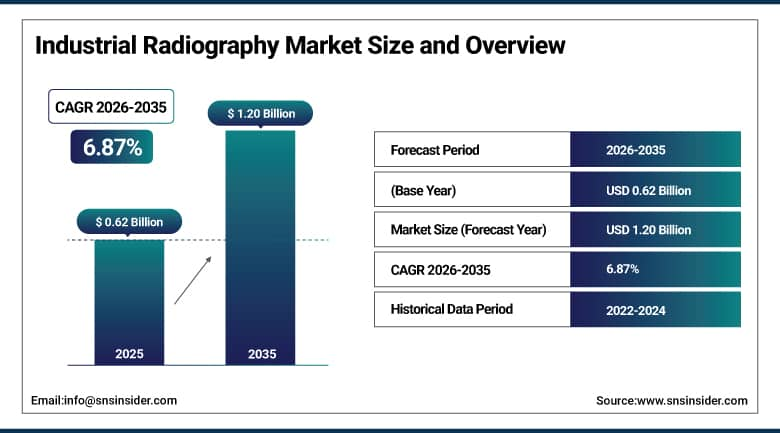
The Industrial Radiography Market was valued at USD 0.62 Billion in 2025 and is expected to reach USD 1.20 Billion by 2035, growing at a CAGR of 6.87% from 2026-2035.
The Industrial Radiography Market includes the sale of non-destructive testing tools and software used for the inspection of welds, castings, pipelines, and pressure vessels through X-rays and gamma rays, and this market is underpinned by stringent safety rules and quality standards set by governments in the oil and gas, aerospace, automotive, and power generation industries, since any undetected flaw could lead to a catastrophic accident. Over 57% of the manufacturing plants worldwide use radiography testing to verify their structural integrity, with almost 52% of its usage tied to applications involving weld and pressure vessel inspection. The market is slowly transitioning from film-based radiography tools towards the use of digital flat panel detectors, which cut down the inspection cycles and reduce the cost of consumables compared to chemical film, and software-based image analysis is now helping to differentiate equipment suppliers.
In April 2026, Hexagon AB entered into a definite agreement with Baker Hughes regarding acquisition of its subsidiary Waygate Technologies along with its leading Radiography and Remote Visual Inspection product lines for an approximate amount of USD 1.45 billion, where radiography and RVI product line alone was contributing to an annual revenue of around USD 330 million and earning EBIT margins of 16% in fiscal year 2025. The deal is about combining the coordinate measuring machines and metrology software products from Hexagon with computed tomography and radiography systems of Waygate to create a combined precision measurement and inspection solution from exterior to internal component analysis; thus, depicting the trend that radiography equipment vendors are now getting merged with industrial metrology systems.
To Get More Information On Industrial Radiography Market - Request Free Sample Report
Industrial Radiography Market Trends
- Continued displacement of film-based radiography by digital flat-panel detector systems.
- Growing integration of AI-assisted defect recognition software to reduce technician interpretation variance.
- Rising adoption of automated and robotic radiographic inspection systems for hazardous or hard-to-access assets.
- Expanding use of cloud-based platforms that automate inspection compliance reporting and data management.
- Increasing industry consolidation as metrology and inspection platform providers acquire radiography specialists.
U.S. Industrial Radiography Market Outlook
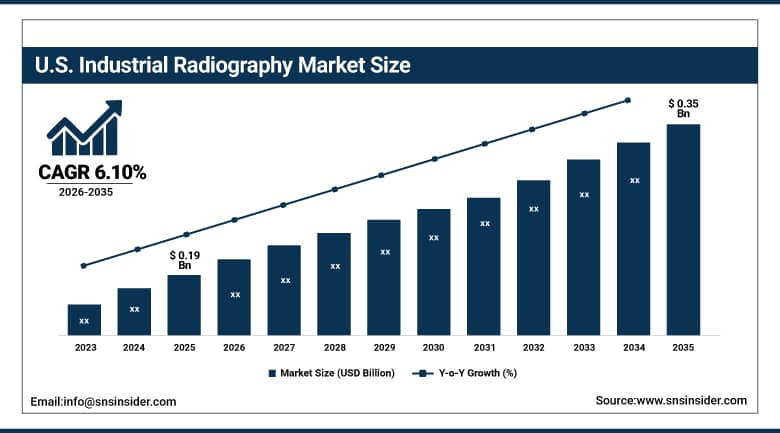
The U.S. Industrial Radiography Market was valued at USD 0.19 Billion in 2025 and is expected to reach USD 0.35 Billion by 2035, growing at a CAGR of 6.10% from 2026-2035.
The US continues to be a key national industrial radiographic inspection market owing to the presence of tight occupational safety and quality regulation rules within the oil and gas, aerospace, and power generation industries along with a solid presence of equipment manufacturers and inspection companies. The constant need for preventive maintenance of aging industrial infrastructure such as pipelines, refining, and power generation facilities contributes to a steady demand for inspection services and hardware in the country. Some of the top players in the industry include GE Inspection Technologies, Mistras Group, and Waygate Technologies.
In April 2024, Waygate Technologies, then a Baker Hughes business, launched the Krautkrämer CL Go+ portable ultrasonic flaw detector, expanding its non-destructive testing instrument portfolio alongside its established radiography product lines. The launch reflects how leading NDT equipment providers continue to broaden their inspection technology portfolios beyond radiography alone, offering customers integrated multi-modality inspection capability that combines radiographic, ultrasonic, and other testing methods within a single vendor relationship, a strategy that is increasingly important as industrial customers seek to consolidate their inspection equipment and service supplier base.
Industrial Radiography Market Segment Analysis
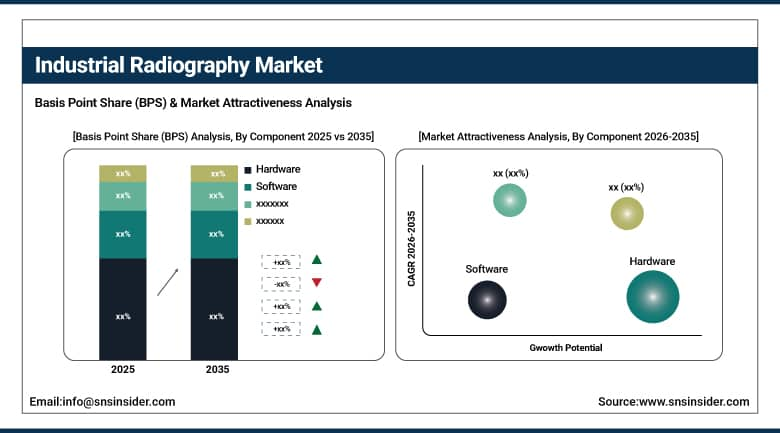
- By Component, the Hardware segment dominated the Industrial Radiography Market with approximately 56.40% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 9.20%.
- By Imaging Technology, the Digital Radiography segment dominated the Industrial Radiography Market with approximately 52.75% share in 2025, while the Computed Radiography segment is the fastest growing with a CAGR of approximately 8.65%.
- By End-User, the Oil & Gas segment dominated the Industrial Radiography Market with approximately 28.90% share in 2025, while the Aerospace & Defense segment is the fastest growing with a CAGR of approximately 8.40%.
By Component, Hardware dominates, and Software grows fastest
Hardware remained the main component contributor in 2025 due to the essential capital equipment investments necessary for the manufacturing of the X-ray, the gamma-ray equipment, digital detectors, and imaging systems – the tangible assets which constitute the basis of an industrial radiography inspection capacity irrespective of software installed on top.
Software is the fastest-growing component segment thanks to the growing importance of artificial intelligence in defect detection and the automation of reporting provided by cloud-based services. Customers increasingly measure the value of radiography vendors not only by hardware performance but also by the quality of software and analytics.
By Imaging Technology, Digital Radiography dominates, and Computed Radiography grows fastest
The digital radiography market accounted for the lion's share of imaging technology market size in 2025, as the industry continued its transition from film radiography to digital flat panel detectors, which provided faster cycle times, reduced costs of supplies, and instant access to digital images for analysis and storage.
Compared to other imaging technologies, computed radiography grew the fastest because it represented an economic option for the transition from film to digital radiography, since it does not require significant capital investments into detector arrays necessary for the use of direct digital radiography.
By End-User, Oil & Gas dominates, and Aerospace & Defense grows fastest
Oil & Gas held the largest end-user share in 2025, reflecting the sector's extensive use of radiographic weld inspection and pipeline integrity testing to comply with stringent safety regulations governing pressurized hydrocarbon transport and processing infrastructure, where inspection failures carry severe safety and environmental consequences.
Aerospace & Defense is the fastest-growing end-user segment as increasing aircraft production rates, growing additive manufacturing adoption requiring internal defect verification, and expanding satellite constellation deployment requiring space-grade component qualification all drive sustained radiographic inspection demand. Rising automation in aerospace manufacturing is further reinforcing demand for radiography systems capable of integrating with automated production and quality assurance workflows.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
78.30 |
|
Europe |
Germany |
30.65 |
|
Asia Pacific |
China |
40.20 |
|
Middle East & Africa |
Saudi Arabia |
38.75 |
|
Latin America |
Brazil |
46.40 |
North America Industrial Radiography Market Insights
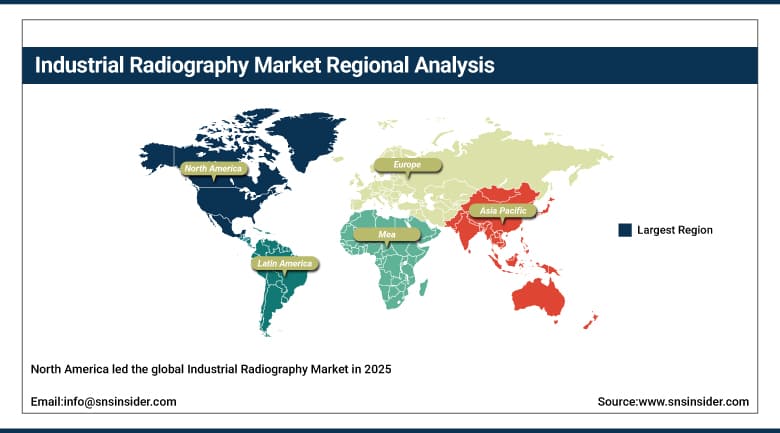
North America led the global Industrial Radiography Market in 2025, driven by stringent safety regulations and advanced technology adoption across the region's oil and gas, aerospace, and power generation sectors. The United States accounted for the substantial majority of regional demand, supported by an established base of equipment manufacturers and inspection service providers including GE Inspection Technologies and Mistras Group.
Canada contributes additional regional demand through its own oil and gas pipeline infrastructure requiring ongoing integrity inspection. Continued preventive maintenance requirements for aging industrial infrastructure across the region are expected to sustain North America's leading market position through the near term of the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Industrial Radiography Market Insights
Asia Pacific represents the fastest-growing region in the Industrial Radiography Market, which is anticipated to grow at a CAGR of about 8.30% through 2026 to 2035, driven by increasing infrastructure spending and non-destructive testing needs in China, India, and Southeast Asia. The growing manufacturing, power, and oil and gas infrastructure of China is driving high regional demand for radiographic testing equipment and services.
The increasing industrial and infrastructure spending in India, along with the growing domestic manufacturing of the aerospace and automotive industry, is driving increasing regional demand. The ongoing industrialization of Southeast Asian economies is expected to keep up the above-average growth rate of the region during the forecast period.
Europe Industrial Radiography Market Insights
Europe represents a significant industrial radiography market, underpinned by stringent EU industrial safety and product quality regulations and a well-established base of radiography equipment manufacturers. Germany leads regional demand, supported by its large manufacturing base and concentration of NDT equipment and software providers.
France, Italy, and the United Kingdom contribute significant additional regional demand through their own aerospace, automotive, and power generation sectors, each subject to rigorous EU-wide industrial safety and quality assurance requirements. Continued European emphasis on industrial safety compliance is expected to sustain steady regional demand growth through the forecast period.
MEA & Latin America Industrial Radiography Market Insights
The Middle East & Africa industrial radiography market is expected to grow due to investments in oil and gas facilities, and petrochemical facilities by Gulf Cooperation Council nations with Saudi Arabia accounting for the majority of demand owing to its substantial hydrocarbon production and processing facilities which need integrity testing.
Latin America will be driven by Brazil, which is experiencing continuous activity within the oil and gas industry, petrochemicals industry, and manufacturing industry, thus increasing demand for industrial radiography. Mexico will be contributing to Latin American demand due to its growing manufacturing industry and energy industry.
Market Dynamics
Growth Drivers: Industrial Safety Regulation and Preventive Maintenance
Stringent government regulations governing industrial safety and product quality across oil and gas, aerospace, and power generation industries remain the primary driver of industrial radiography demand, as regulators mandate periodic radiographic inspection of welds, pressure vessels, and other critical components to prevent catastrophic structural failures.
Growing emphasis on preventive maintenance of aging industrial equipment is reinforcing this driver, as facility operators increasingly move from reactive inspection following incidents toward scheduled radiographic testing programs designed to identify developing defects before they progress to failure. This preventive maintenance shift is particularly pronounced in industries operating long-lived capital assets such as pipelines, refineries, and power generation infrastructure.
Restraints: High Equipment Costs and Radiation Safety Requirements
The substantial capital cost of digital radiography systems, particularly high-resolution flat-panel detector arrays, remains a meaningful restraint for smaller inspection service providers and facilities in cost-sensitive markets, where film-based or computed radiography alternatives may be viewed as adequate despite their longer inspection cycle times.
Radiation safety requirements associated with X-ray and gamma-ray radiography, including specialized technician certification, shielding infrastructure, and regulatory licensing for radioactive source handling, add operational complexity and cost that continues to constrain broader market penetration, particularly in developing regions where radiation safety infrastructure and trained personnel remain limited.
Opportunities: AI-Driven Defect Recognition and Robotic Inspection Automation
The integration of AI-assisted defect recognition software presents a significant opportunity for equipment vendors to differentiate on inspection accuracy and consistency, reducing the technician interpretation variance that has historically been a source of inspection quality inconsistency across different operators and facilities.
Growing adoption of automated and robotic radiographic inspection systems, capable of accessing hazardous or hard-to-reach industrial assets without direct human exposure to radiation sources, presents a further opportunity for vendors serving oil and gas, power generation, and other industries with challenging inspection environments. Vendors successfully commercializing robotic inspection platforms are positioned to capture premium pricing from customers prioritizing both inspection quality and worker safety.
Recent Developments:
- 2025- Eddyfi Technologies completed its acquisition of NDT Global GmbH, creating a combined entity with enhanced pipeline inspection capabilities and broader geographic reach across Europe and the Middle East.
- 2024- Pragma NDT launched the PragmaFlex, described as the world's first portable NDE 4.0 instrument platform supporting advanced ultrasonic and eddy current testing techniques.
- 2024- Waygate Technologies, then a Baker Hughes business, launched the Krautkrämer CL Go+ portable ultrasonic flaw detector, expanding its non-destructive testing instrument portfolio.
Industrial Radiography Market Key Players
- General Electric Company (GE Inspection Technologies)
- Siemens AG
- Mistras Group, Inc.
- Nikon Metrology NV
- Evident Corporation (Olympus)
- Zetec, Inc.
- FUJIFILM Holdings Corporation
- AMETEK, Inc.
- Intertek Group plc
- Waygate Technologies
- 3DX-RAY Ltd.
- Bosello High Technology S.r.l.
- Revvity, Inc.
- Mettler-Toledo International Inc.
- Anritsu Corporation
- COMET Holding AG
- Shimadzu Corporation
- Eddyfi Technologies
- Acuren Inspection Inc.
- YXLON International GmbH
Industrial Radiography Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.62 Billion |
| Market Size by 2035 | USD 1.20 Billion |
| CAGR | CAGR of 6.22% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Hardware, Software, and Services) • By Imaging Technology (Digital Radiography, Computed Radiography, and Film-Based Radiography) • By End-User (Oil & Gas, Aerospace & Defense, Power Generation, and Automotive & Manufacturing) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | General Electric Company (GE Inspection Technologies); Siemens AG; Mistras Group, Inc.; Nikon Metrology NV; Evident Corporation (Olympus); Zetec, Inc.; FUJIFILM Holdings Corporation; AMETEK, Inc.; Intertek Group plc; Waygate Technologies; 3DX-RAY Ltd.; Bosello High Technology S.r.l.; Revvity, Inc.; Mettler-Toledo International Inc.; Anritsu Corporation; COMET Holding AG; Shimadzu Corporation; Eddyfi Technologies; Acuren Inspection Inc.; YXLON International GmbH. |
Frequently Asked Questions
Key players in the Industrial Radiography Market include General Electric Company, Siemens AG, Mistras Group, Inc., Nikon Metrology NV, and Evident Corporation, among others.
Key opportunities lie in AI-assisted defect recognition software that reduces inspection variance, and in automated and robotic radiographic inspection systems for hazardous or hard-to-reach assets.
Stringent industrial safety regulation combined with growing preventive maintenance requirements for aging industrial infrastructure is the major growth factor.
By Component, the Hardware segment dominated the Industrial Radiography Market with approximately 56.40% share in 2025.
North America dominated the Industrial Radiography Market in 2025, supported by stringent safety regulations and advanced technology adoption.
