
Liquid Packaging Market Report Scope & Overview:
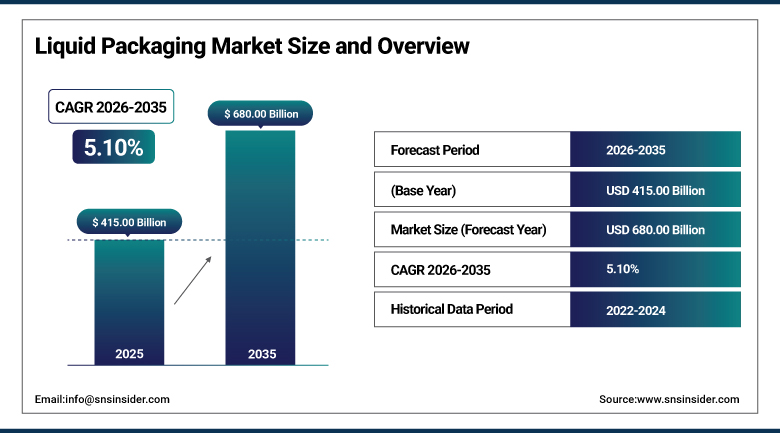
The Liquid Packaging Market was valued at USD 415.00 Billion in 2025 and is expected to reach USD 680.00 Billion by 2035, growing at a CAGR of 5.10% from 2026–2035.
Liquid packaging covers every container built to hold something that pours, from a gable-top milk carton to an aseptic juice box to a pharmaceutical vial, engineered around a single non-negotiable requirement: keep the liquid inside sealed, uncontaminated, and stable for however long the label promises. Aseptic technology in particular has quietly reshaped global food distribution, letting a carton of milk sit unrefrigerated on a shelf for months without spoiling, something that would have required a dedicated cold chain a generation ago. Rising packaged beverage consumption and expanding e-commerce delivery of liquid products have both been pushing steady demand growth across nearly every material and format category.
SIG Group launched what it called the world's first aluminum-layer-free, full-barrier aseptic carton material for multi-serve formats in May 2025, followed two months later by the world's first 1-litre aluminum-free aseptic carton pack. Removing the thin aluminum foil layer that has protected aseptic cartons from oxygen and light for decades, while still holding shelf life and barrier performance steady, is exactly the kind of unglamorous materials-science problem the entire liquid packaging industry has been racing to solve, since that foil layer is also what makes a carton harder to recycle through standard paper streams.
To Get more information Liquid Packaging Market - Request Free Sample Report
Liquid Packaging Market Trends
-
Aluminum-free aseptic carton technology continues advancing from pilot programs toward genuine multi-serve, high-speed production line adoption, addressing one of the category's longest-standing recyclability limitations.
-
Chemical and mechanical recycling investment continues expanding across major liquid packaging material producers, driven by both regulatory recycled-content mandates and brand owner sustainability commitments.
-
Healthcare and pharmaceutical liquid packaging demand continues accelerating as rising biologics, vaccine, and personalized-medicine volumes require sterile, traceable primary packaging beyond standard commodity beverage containers.
-
Personal care formulators are migrating toward aluminum aerosol bottles and post-consumer resin content, reflecting broader sustainability pressure spreading beyond food and beverage into cosmetics and household liquid products.
-
Manufacturers continue expanding aseptic carton production capacity in emerging markets, particularly South Asia, to meet rising demand for shelf-stable dairy and juice packaging that doesn't depend on cold-chain infrastructure.
U.S. Liquid Packaging Market Outlook
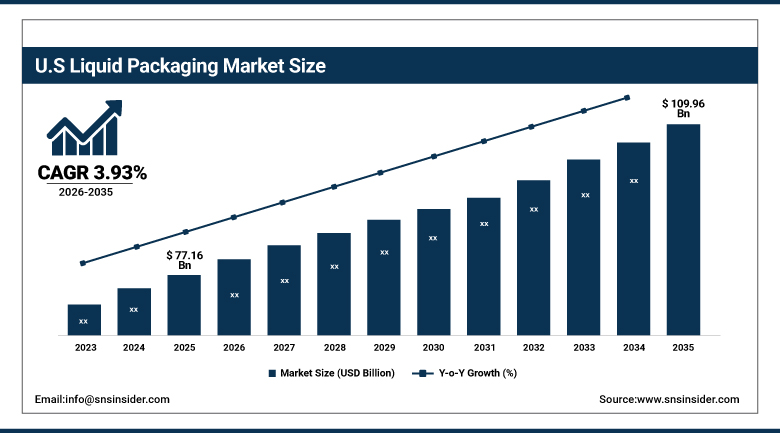
The U.S. Liquid Packaging Market was valued at approximately USD 77.16 Billion in 2025 and is expected to reach approximately USD 109.96 Billion by 2035, growing at a CAGR of approximately 3.93%.
Demand in the United States spans a large, mature beverage and dairy packaging industry alongside a growing pharmaceutical and healthcare liquid packaging segment tied to rising biologics and vaccine manufacturing capacity. Domestic converters continue investing in automated aseptic filling and recycling infrastructure to meet both regulatory sustainability requirements and brand owner commitments, even as the American liquid packaging market remains more fragmented across multiple domestic brand portfolios than Europe's more carton-concentrated aseptic packaging landscape. Growing e-commerce delivery of liquid consumer products continues adding a further layer of demand for leak-resistant, shipping-durable packaging formats.
Sealed Air Corporation, headquartered in Charlotte, North Carolina, continues expanding automated aseptic packaging technology across its Cryovac and Liquibox brands, both widely used across U.S. dairy, beverage, and liquid food processing, while pursuing a company-wide commitment to reach net-zero emissions by 2040. That timeline puts Sealed Air on a similar sustainability trajectory to its larger European competitors, even though the American liquid packaging market remains more fragmented across multiple domestic brand portfolios than Europe's carton-dominated aseptic packaging landscape.
Liquid Packaging Market Segment Analysis
-
By Material Type, the Plastic segment dominated the Liquid Packaging Market with approximately 44.60% share in 2025, while the Paper segment is the fastest growing with a CAGR of approximately 7.20%.
-
By Packaging Type/Format, the Rigid Packaging segment dominated the Liquid Packaging Market with approximately 85.50% share in 2025, while the Flexible Packaging segment is the fastest growing with a CAGR of approximately 7.60%.
-
By Technology, the Aseptic Liquid Packaging segment dominated the Liquid Packaging Market with approximately 38.40% share in 2025, while the Blow Molding segment is the fastest growing with a CAGR of approximately 7.90%.
-
By End-User Industry, the Food & Beverage segment dominated the Liquid Packaging Market with approximately 48.30% share in 2025, while the Pharmaceuticals & Healthcare segment is the fastest growing with a CAGR of approximately 7.87%.
-
By Container Capacity, the 1–10 L segment dominated the Liquid Packaging Market with approximately 52.60% share in 2025, while the ≤1 L segment is the fastest growing with a CAGR of approximately 6.80%.
By Material Type, plastic dominates, paper grows fastest
Plastic held the largest share of the material-type segment in 2025, valued for its lightweight nature, cost-effectiveness, durability, and versatility in meeting diverse packaging needs across food and beverage, pharmaceutical, and personal care industries simultaneously. Its compatibility with high-speed blow-molding and filling equipment across nearly every liquid packaging format keeps plastic the default material choice for the majority of commodity liquid packaging applications worldwide.
Paper is growing fastest as brand owners and regulators alike push toward fiber-based liquid packaging, particularly aseptic cartons, that offers a more straightforward recycling pathway than multi-material plastic and foil laminate structures. Continued innovation in paper-based aseptic barrier technology, eliminating aluminum foil layers while maintaining shelf-life performance, is directly reinforcing this above-average growth trajectory relative to the broader, plastic-dominated material mix.
By Packaging Type/Format, rigid dominates, flexible grows fastest
Rigid packaging held the overwhelming majority of the packaging-type segment in 2025, driven by its higher usage across pharmaceutical drugs and beverage packaging where structural strength, leak prevention, and contamination protection all matter more than the marginal cost or weight savings flexible formats might offer. That combination of durability and secure containment keeps rigid packaging the dominant format across the vast majority of liquid packaging applications globally.
Flexible packaging is growing fastest as convenient, easy-to-carry, and easy-to-store options continue gaining favor for applications where safe, cost-efficient transportation and storage matter more than the premium shelf presence rigid containers typically offer. Growing adoption of pouches and flexible sachets across personal care and household liquid products is reinforcing this above-average growth trajectory relative to the broader, rigid-dominated packaging format mix.
By Technology, aseptic liquid packaging dominates, blow molding grows fastest
The aseptic liquid technology sub-segment accounted for the largest market size in 2025 due to its ability to offer increased shelf life without preservatives while maintaining the integrity of the product and satisfying food safety standards in ambient and non-refrigerated distribution. Such a combination of increased shelf life and less reliance on cold chain distribution has resulted in aseptic technology becoming the dominant option for dairy, juice, and other highly perishable liquid foods.
Blow molding is gaining the highest growth as players keep investing in faster and more advanced blow molding machinery that can create more complex shapes at larger production volumes. Such a combination of fast production speed and design flexibility is what is driving the growth of this technology segment ahead of other more traditional options such as aseptic packaging.
By End-User Industry, food & beverage dominates, pharmaceuticals & healthcare grows fastest
Food and beverage accounted for the largest end-user share in 2025, driven by rising demand for packaged drinks including bottled water, fizzy beverages, and dairy products, alongside growing consumer desire for convenience and portability across nearly every liquid food and beverage category. That combination of high transaction volume and broad product diversity keeps food and beverage the anchor end-user industry across the entire liquid packaging market.
Pharmaceuticals and healthcare is the fastest-growing end-user industry as rising biologics, vaccine, and personalized-medicine volumes mandate sterile and traceable primary packaging that commodity food and beverage containers weren't designed to provide. That specialized requirement for contamination-free, precisely dosed liquid packaging is pulling this end-user industry's growth well ahead of the broader, higher-volume food and beverage segment.
By Container Capacity, 1–10 L dominates, ≤1 L grows fastest
Containers in the 1 to 10 liter range held the largest share of the container-capacity segment in 2025, matching the standard household and retail packaging sizes most common across dairy, juice, and household liquid product categories worldwide. That broad compatibility with typical household consumption patterns keeps this capacity range the default specification across the majority of retail liquid packaging.
Containers of 1 liter or less are growing fastest as single-serve and portion-controlled packaging trends continue expanding across beverages, personal care, and pharmaceutical products aimed at individual, on-the-go consumption. Rising demand for portability and convenience among busy, urban consumers continues reinforcing this above-average growth trajectory relative to the broader, larger-format container capacity segment.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.75% |
|
North America |
United States |
80.85% |
|
Europe |
Germany |
25.60% |
|
Latin America |
Brazil |
35.40% |
|
Middle East & Africa |
Saudi Arabia |
29.65% |
Asia Pacific Liquid Packaging Market Insights
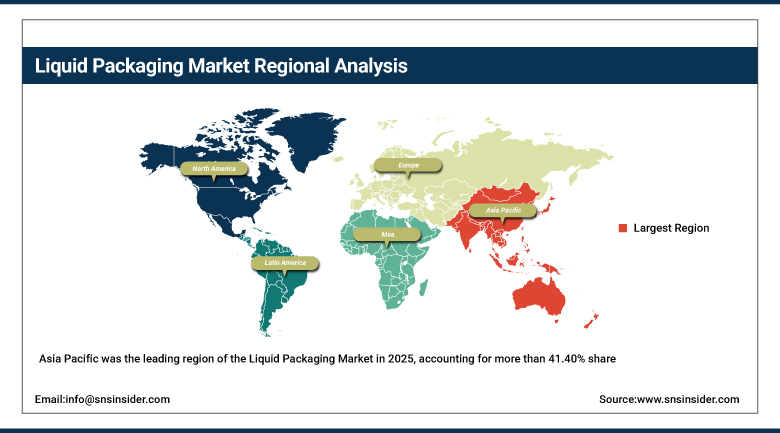
Asia Pacific was the leading region of the Liquid Packaging Market in 2025, accounting for more than 41.40% share of the total global market revenue, and the region is estimated to record the highest regional CAGR of around 8.53% up to 2035. The rapid growth of e-commerce and online shopping portals, the high use of liquid packaging in the healthcare industry, and constant improvements in packaging materials technologies are driving the growth of the market in the major and fastest urbanizing economies of the region. The rising need for packaged drinks, like bottled water and dairy products, coupled with an increasing consumer preference for convenience, is adding to this dominance and rapid growth.
The large manufacturing base of China in the food & beverages industry makes Asia Pacific a strong initial market, while the expanding organized dairy and pharmaceutical industries of India are attracting investments in the liquid packaging infrastructure. Japan and South Korea are more mature and quality-conscious markets with set standards for aseptic packaging, while the Southeast Asian markets continue their urbanization-led growth path.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Liquid Packaging Market Insights
North America represents a substantial liquid packaging market, with the United States accounting for the large majority of regional demand through its mature beverage, dairy, and pharmaceutical packaging industries. Growing healthcare sector adoption of specialized liquid packaging, combined with rising e-commerce delivery of liquid consumer products, continues supporting steady regional demand growth across nearly every packaging format and material category.
Canada contributes additional demand through its own dairy and beverage processing sector, while Mexico's market continues expanding alongside growing packaged food and beverage manufacturing investment. Cross-border supply relationships tie much of North American demand together, with major manufacturers typically serving all three markets through shared production and distribution networks.
Europe Liquid Packaging Market Insights
Europe is an established sustainable liquid packaging market characterized by high recycled content targets and the absence of aluminum in cartons set by leading aseptic pack manufacturers, in addition to robust packaging waste regulation in the EU. The country driving European demand for liquid packaging is Germany, which has a significant dairy and beverage production industry along with several large liquid pack manufacturing companies.
Also contributing to regional demand are France, Italy, and the Netherlands due to their significant dairy, beverage, and pharmaceutical manufacturing industries. These countries have had to adapt to stricter sustainability targets. The development of recycling facilities to reclaim both plastic and aluminum components of aseptic cartons is continually being developed.
MEA & Latin America Liquid Packaging Market Insights
The Middle East and Africa represent a smaller but developing liquid packaging market, with Saudi Arabia driving demand through growing beverage and dairy processing investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader food and beverage manufacturing and organized retail infrastructure development.
Latin America is a growing market led by Brazil, where expanding dairy and beverage manufacturing continues driving demand for aseptic and rigid liquid packaging formats. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing packaged beverage and pharmaceutical manufacturing sectors.
Market Dynamics
Growth Drivers: Packaged beverage demand and healthcare packaging expansion fueling adoption
Rising demand for packaged beverages, including bottled water, dairy products, and functional drinks, is one of the clearest forces behind rising liquid packaging demand, as growing consumer desire for convenience and portability continues expanding packaged beverage consumption across both developed and emerging markets. That consistent, high-frequency purchase pattern gives the liquid packaging market a demand base that holds up reliably across economic cycles.
Expanding healthcare and pharmaceutical liquid packaging demand adds a second major driver, as rising biologics, vaccine, and personalized-medicine volumes require sterile, traceable primary packaging that commodity beverage containers can't provide. Growing global healthcare infrastructure investment continues reinforcing this demand base independent of broader packaged beverage consumption trends, giving the market a genuinely diversified growth foundation.
Restraints: Raw material price volatility and recycling infrastructure gaps limiting margin stability
Fluctuating plastic resin and paperboard prices add real cost unpredictability for manufacturers, since both material categories remain exposed to broader commodity and petrochemical market swings that directly affect production costs and, ultimately, project budgets for brand owner customers. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-packaging demand remains steady.
Uneven recycling infrastructure across different markets adds a further restraint, since multi-material aseptic cartons and laminated flexible pouches both require specialized processing that many regions haven't yet built at meaningful scale. That infrastructure gap limits how quickly genuine circularity can improve even as producers invest heavily in aluminum-free and mono-material packaging redesigns as an alternative pathway.
Opportunities: Aluminum-free aseptic technology and single-serve format expansion opening new growth avenues
Aluminum-free aseptic carton technology offers manufacturers a genuine path to capturing premium business from brand owners chasing credible sustainability commitments ahead of tightening packaging waste regulation across major markets. Companies that successfully commercialize this technology at multi-serve, high-speed production scale are positioned to capture significant new business as regulatory and brand pressure on multi-material packaging continues building.
Single-serve and portion-controlled format expansion represents a second significant opportunity, as rising demand for portability and convenience continues pulling consumer preference toward smaller, individually packaged liquid products across beverages, personal care, and pharmaceutical categories. Manufacturers that build strong single-serve production capability are positioned to capture disproportionate growth as this consumption pattern continues expanding across urban, on-the-go consumer segments worldwide.
Recent Developments:
-
February 13, 2025: SIG Group officially inaugurated its first aseptic carton manufacturing plant in India, located in Ahmedabad, Gujarat.
-
February 24, 2025: Tetra Pak introduced packaging material containing 5% certified recycled polymers in India, complying with new regulatory mandates for recycled content.
-
2025: Tetra Pak continued scaling its paper-based aseptic barrier technology, first launched commercially with Portuguese dairy producer Lactogal in 2023, onto additional customer production lines including a juice packaging launch with Spanish drinks brand García Carrión.
-
2025: Elopak continued expanding its aluminum-free, fully recyclable carton portfolio, building on its earlier gable-top carton launches for dairy customers across Europe.
Liquid Packaging Market Key Players
-
Tetra Laval International S.A. (Tetra Pak)
-
Mondi Group
-
Amcor plc
-
SIG Group AG
-
ProAmpac Intermediate Inc.
-
Greatview Aseptic Packaging Co., Ltd.
-
Klabin S.A.
-
DOW Inc.
-
Smurfit WestRock plc
-
Pactiv Evergreen Inc.
-
Refresco Group B.V.
-
Reynolds Group Holdings Limited
-
Elopak ASA
-
Berry Global Inc.
-
Sonoco Products Company
-
Sealed Air Corporation
-
Huhtamaki Oyj
-
Stora Enso Oyj
-
International Paper Company
-
Nampak Ltd.
Liquid Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 415.00 Billion |
| Market Size by 2035 | USD 680.00 Billion |
| CAGR | CAGR of 5.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material Type (Plastic, Paperboard, Glass, Metal, Others) • by Packaging Type/Format (Rigid Packaging, Flexible Packaging) • by Technology (Aseptic Liquid Packaging, Blow-Fill-Seal, Form Fill Seal, Blow Molding, Others) • by End-User Industry (Food & Beverage, Pharmaceuticals & Healthcare, Personal Care & Cosmetics, Chemicals, Others) • by Container Capacity (≤1 L, 1–10 L, Above 10 L) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Tetra Laval International S.A. (Tetra Pak), Mondi Group, Amcor plc, SIG Group AG, ProAmpac Intermediate Inc., Greatview Aseptic Packaging Co., Ltd., Klabin S.A., DOW Inc., Smurfit WestRock plc, Pactiv Evergreen Inc., Refresco Group B.V., Reynolds Group Holdings Limited, Elopak ASA, Berry Global Inc., Sonoco Products Company, Sealed Air Corporation, Huhtamaki Oyj, Stora Enso Oyj, International Paper Company, Nampak Ltd. |
Frequently Asked Questions
Key players in the Liquid Packaging Market include Tetra Laval International S.A., Mondi Group, Amcor plc, SIG Group AG, and ProAmpac Intermediate Inc., among others.
Key opportunities in the Liquid Packaging Market include aluminum-free aseptic carton technology for multi-serve, high-speed production and single-serve, portion-controlled format expansion across beverages and personal care.
The market is driven by rising demand for packaged beverages including bottled water and dairy products, combined with expanding healthcare and pharmaceutical liquid packaging demand.
The Rigid Packaging segment dominated the Liquid Packaging Market, accounting for approximately 85.50% market share.
The Asia Pacific region dominated the Liquid Packaging Market in 2025 with more than 41.40% share, driven by significant expansion of e-commerce platforms and widespread adoption of liquid packaging in the healthcare sector.
