
Population Health Management Market Report Scope & Overview:
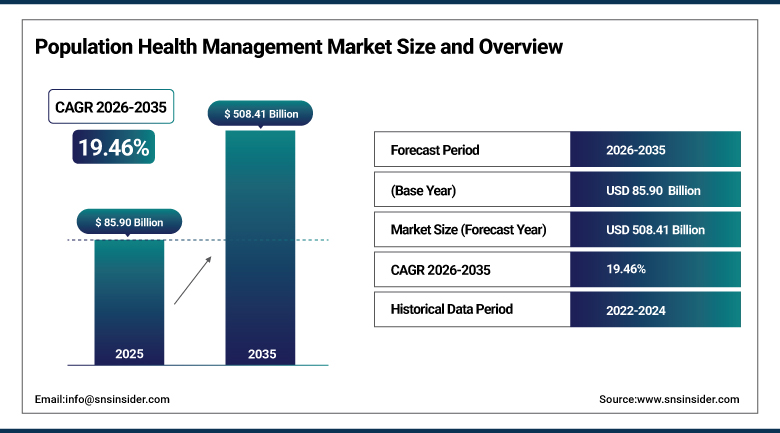
The Population Health Management Market was valued at USD 85.90 Billion in 2025 and is expected to reach USD 508.41 Billion by 2035, growing at a CAGR of 19.46% from 2026-2035.
The Population Health Management Market is on a strong expansion path, underpinned by the transition of health systems, insurers and employers from volume-based reimbursement toward outcome-linked payment for defined patient groups. Platforms that consolidate clinical, claims and social data allow stakeholders to stratify risk, close care gaps and direct outreach before avoidable costs are incurred. The increasing prevalence of chronic disease, population aging and the spread of accountable care contracts are encouraging sustained investment in analytics and care management tools. Advances in artificial intelligence are improving predictive accuracy, while cloud delivery is lowering entry barriers. North America accounts for the leading share, and Asia Pacific is anticipated to register the fastest growth.
⮞The Centers for Disease Control and Prevention reported in May 2026 that roughly three in four U.S. adults live with at least one chronic condition, and that chronic diseases account for USD 5.3 trillion in annual health care expenditure. The scale of this burden is prompting risk-bearing organizations to build population-level programs.
To Get more information Population Health Management Market - Request Free Sample Report
Population Health Management Market Trends
-
Adoption of AI and agentic tools for risk stratification, care plan drafting and automated patient outreach
-
Transition from fee-for-service toward value-based and risk-sharing contracts among payers and providers
-
Incorporation of social determinants, behavioral health and pharmacy data into unified dashboards
-
Migration to cloud-based and unified data platforms that merge clinical and claims records
-
Expansion of remote monitoring, hospital-at-home and technology-enabled chronic care programs
U.S. Population Health Management Market Outlook
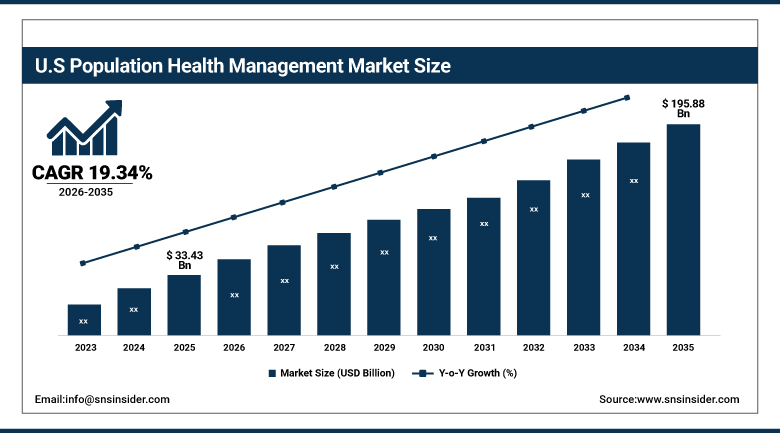
The U.S. Population Health Management Market was valued at USD 33.43 Billion in 2025 and is expected to reach USD 195.88 Billion by 2035, growing at a CAGR of 19.34% from 2026-2035.
The U.S. Population Health Management Market represents the largest national market, supported by accountable care programs, the growth of Medicare Advantage and a heavy chronic disease cost burden. Hospitals, physician groups and health plans deploy these platforms to identify high-risk patients, close quality gaps and administer shared savings arrangements. Federal payment models that reward cost control and improved outcomes continue to sustain demand for analytics and care coordination solutions. Electronic record vendors, specialist analytics firms and large insurers compete for the associated budgets. Interoperability requirements and the diffusion of AI tools provide additional momentum, while data privacy obligations shape the design of every deployment.
⮞In February 2026, the Centers for Medicare and Medicaid Services reported that about 14.3 million beneficiaries participate in Medicare accountable care initiatives for 2026, a 4.4% increase over 2025. With 511 accountable care organizations now enrolled in the Shared Savings Program, the installed base of organizations requiring population-level tools continues to widen.
Population Health Management Market Segment Analysis
-
By Component, the Services segment dominated the Population Health Management Market with approximately 58.43% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 21.05%.
-
By Delivery Mode, the Cloud-Based segment dominated the Population Health Management Market with approximately 66.51% share in 2025, and is also the fastest growing with a CAGR of approximately 21.40%.
-
By Application, the Population Health Analytics segment dominated the Population Health Management Market with approximately 28.13% share in 2025, while the Patient Engagement segment is the fastest growing with a CAGR of approximately 22.65%.
-
By End User, the Healthcare Providers segment dominated the Population Health Management Market with approximately 52.75% share in 2025, while the Healthcare Payers segment is the fastest growing with a CAGR of approximately 22.30%.
By Component, Services Dominates the Population Health Management Market and Software Grows Fastest
The dominance of the services component is attributed to the dependence of population health programs on data integration, workflow design, care management staffing and continuous analytical support, capabilities that most provider and payer organizations are unable to assemble internally. Multi-year agreements covering implementation, data normalization, quality reporting and outsourced care coordination are common. Source data originates in numerous record systems, claims feeds and community partners, and reconciling it into a common model requires specialized teams. Such engagements generate recurring revenue for vendors and consultants and typically extend as programs are widened to additional populations and contracts.
Software, in contrast, is projected to expand at the faster pace as platforms mature and buyers favor configurable products that their own staff can operate. Vendors are embedding AI-based risk scoring, automated care gap lists and outreach functions within core platforms, which raises the value captured per license. Subscription pricing lowers initial outlay and distributes expenditure across contract years, while unified data platforms are displacing several stand-alone tools. As organizations accumulate operating experience, a growing portion of spending is expected to shift from external services toward software that scales across larger patient groups at a lower marginal cost.
⮞In July 2025, athenahealth expanded its value-based care marketplace and data exchange to connect additional practices with payer programs. The initiative illustrates the growing integration of population tools into the routine workflows of electronic record vendors.
By Delivery Mode, Cloud-Based Dominates the Population Health Management Market and Is Also the Fastest Growing
Cloud-based delivery commands the leading position, and is also advancing most rapidly, because population health platforms must combine large volumes of clinical, claims and social data and scale as new contracts are added. Providers avoid sizable server investments and obtain faster updates to quality measures and payer rules. Vendors can deploy AI models across their entire customer base simultaneously, improving accuracy and shortening feature release cycles. Smaller physician groups and community health centers with limited information technology resources rely on hosted products that can be operational within weeks of contract signature.
On-premise and hybrid models retain relevance among large health systems and public agencies subject to strict data residency requirements or dependent on legacy data warehouses. Many such organizations keep sensitive records on local servers while running analytics and engagement tools in the cloud, a practice that favors hybrid architectures. Hybrid delivery is anticipated to gain ground as cloud vendors introduce secure connectivity to local systems. Public sector buyers in several countries additionally prefer controlled environments, so suppliers offering flexible hosting options are positioned to compete for both categories of contract.
In January 2026, Lumeris disclosed that Hackensack Meridian Health would deploy its Tom AI platform within a Medicare shared savings accountable care organization. The deployment signals demand for AI-enabled platforms inside risk-bearing networks.
By Application, Population Health Analytics Dominates the Population Health Management Market and Patient Engagement Grows Fastest
Population health analytics holds the largest position because every program begins with determining who is at risk, which conditions drive expenditure and which interventions are effective. Analytical tools combine claims, clinical and social data to generate risk scores, cost projections and quality dashboards that inform contract management and care planning. Providers apply them to shared savings administration, whereas payers use them for member outreach and benefit design. The growing appetite for predictive models reflects the objective of detecting avoidable admissions, emergency visits and disease progression at an earlier stage.
Patient engagement is anticipated to register the strongest growth as organizations recognize that analytical insight yields limited benefit unless patients respond to outreach. Platforms deliver reminders, educational content, screening invitations and two-way messages through text, mobile applications and calls, with AI tools tailoring timing and tone to individual preferences. Engagement results feed back into risk models and quality scores, linking outreach activity to financial performance under value-based contracts. Care coordination and data integration tools are also expanding, since they connect the clinical teams, community services and data sources that underpin each program.
⮞The Office of the National Coordinator for Health Information Technology reported in September 2025 that 71% of U.S. hospitals used predictive artificial intelligence in 2024, compared with 66% in 2023. The increase reflects a rising level of confidence in models that support risk scoring.
By End User, Healthcare Providers Dominates the Population Health Management Market and Healthcare Payers Grows Fastest
Healthcare providers represent the largest user group, as hospitals, health systems and physician groups carry accountable care and shared savings obligations and are responsible for the quality and cost of their attributed patients. These organizations employ platforms to identify care gaps, monitor chronic conditions, manage care transitions and report quality measures. Federally qualified health centers and community clinics are adopting lower-cost cloud products to serve patients with complex needs. Large integrated delivery networks tend to standardize on enterprise suites, while independent practices obtain technology through the networks they join.
Healthcare payers are projected to grow at the fastest rate as insurers extend value-based contracting, Medicare Advantage programs and member engagement services. Health plans use these platforms to forecast risk, target outreach, equip providers with gap lists and monitor performance across networks. Employer groups constitute a further expanding buyer category, since escalating benefit costs encourage programs that manage chronic conditions among the workforce. Government agencies contribute additional demand by applying population platforms to public health planning, registries and community health initiatives.
⮞The Business Group on Health reported in August 2025 that employers anticipate a median 9% rise in health care costs for 2026. The projected increase is intensifying pressure on employers to fund chronic care management programs.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
80.84 |
|
Europe |
United Kingdom |
23.47 |
|
Asia Pacific |
China |
38.64 |
|
Latin America |
Brazil |
44.12 |
|
Middle East & Africa |
Saudi Arabia |
31.28 |
North America Population Health Management Market Insights
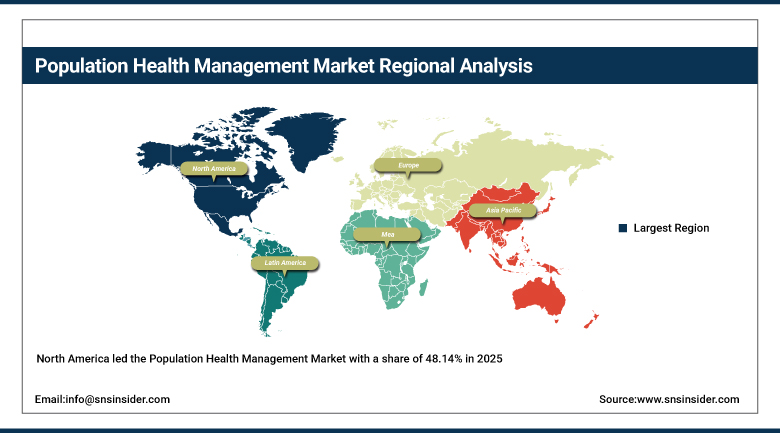
North America led the Population Health Management Market with a share of 48.14% in 2025, a position supported by accountable care programs, the expansion of Medicare Advantage and elevated chronic disease costs. U.S. providers and payers command substantial budgets for analytics and care management, and a deep base of specialist vendors and record suppliers keeps product choice broad. Federal interoperability rules and payment models that reward quality continue to compel organizations to modernize data platforms and report outcomes with greater precision. Employers and state programs also fund chronic care initiatives that rely on the same platforms.
Canada contributes to regional demand through provincial programs that group patients by risk and coordinate care between hospitals and community services. Health expenditure is large and publicly financed, so purchasing priorities center on chronic disease registries, primary care networks and integrated records that follow patients across care settings. Procurement is led by provincial agencies, which lengthens sales cycles relative to the United States, although the programs funded tend to be sizable and to run for several years. Academic centers and health authorities in Ontario, Alberta and British Columbia are among the early users of risk stratification. Cross-border vendors adapt their products to local privacy rules and language requirements.
⮞The Canadian Institute for Health Information reported in November 2025 that total health spending is projected to reach CAD 399 billion for 2025, equivalent to 12.7% of gross domestic product. The magnitude of expenditure reinforces the rationale for tools that manage population-level costs.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Population Health Management Market Insights
Europe is considered a large regional market where the UK, Germany, and France comprise most of the spending. Health services and statutory insurance organizations use population segmentation to deliver care and treat chronic diseases as well as prevent unnecessary admissions. Integrated care systems in the UK rely on population segmentation with shared data and risks management tools between hospitals, general practitioners, and community teams while Germany focuses on disease management programs and electronic health records of insured persons. Insurers in Switzerland and the Netherlands increase demand for risks management tools among their members.
The European Health Data Space creates a common set of rules for using health data that will help to perform analytics and provide access to research data. Countries from the Nordics have been maintaining connected registries that make the analysis of population easy; however, Southern and Eastern markets are at the early stage of developing such databases. The procurement process in Europe is based on tenders and is rather lengthy; this circumstance allows suppliers who already have an established name to win the bid; however, local suppliers with data protection experience get contracts with particular health systems and insurers.
⮞In June 2025, the World Health Organization Regional Office for Europe reported 1.8 million avoidable deaths from noncommunicable diseases each year across the region. The figure strengthens the case for prevention and risk management programs.
Asia Pacific Population Health Management Market Insights
Asia Pacific is projected to be the fastest-growing regional market, expanding at a CAGR of 19.80% during 2026-2035, as governments digitize health records and introduce national programs to manage chronic disease. Aging populations in Japan, South Korea and China, together with rising diabetes and heart disease across South Asia, are prompting health authorities to monitor risk at the population level. Large hospital groups and private insurers are also adopting analytics and engagement tools. Private insurers and employers in the region are testing wellness and chronic care programs.
China is developing regional health information platforms and family doctor programs, India is widening digital health accounts under a national mission, and Singapore operates a national program that enrolls residents with a chosen family clinic. Australia maintains a mature national record that supports analytics, while Japan draws on insurer data for health checks and prevention. Differences in language, regulation and payment systems are considerable, so vendors collaborate with local partners and tailor products to each country. Government funding for digital health infrastructure is widening the buyer base beyond large hospital groups.
⮞In May 2026, India's National Health Authority announced that accounts created under the Ayushman Bharat Health Account system had surpassed 900 million. Enrollment on this scale provides a foundation for population-level data use.
MEA & Latin America Population Health Management Market Insights
In the Middle East and Africa, the Gulf states generate most of the regional demand. Saudi Arabia and the United Arab Emirates are constructing national health data platforms and risk programs under economic modernization plans, and regulators are encouraging the application of AI to preventive care. South Africa and Egypt are showing rising interest through private insurers and hospital networks, although funding constraints, uneven connectivity and shortages of data skills hold back progress across much of Africa. National health data platforms in the Gulf are expected to serve as reference models for neighboring countries.
⮞In October 2025, the Department of Health Abu Dhabi introduced an AI-powered population health intelligence platform developed with Microsoft at a major technology exhibition. The launch demonstrates the investment public health authorities in the Gulf are directing toward population analytics.
Brazil is the largest market in Latin America, where the unified health system serves a very large population and primary care teams operate with electronic records. Mexico, Colombia, Chile and Argentina contribute additional demand through private insurers and hospital chains seeking to contain costs among patients with chronic conditions. Currency volatility and uneven data quality restrict large projects, although the growing burden of noncommunicable disease is steering health ministries and insurers toward risk-based programs. Primary care teams in Brazil already use population registers, which gives local vendors an advantage in public contracts.
⮞In June 2025, Brazil's Ministry of Health reported that 97.6% of basic health units use electronic patient records. This coverage furnishes a data foundation for population programs in primary care.
Market Dynamics
Growth Drivers: Chronic Disease Burden, Value-Based Payment and AI Analytics Drive Growth in the Population Health Management Market
The escalating burden of chronic disease is the principal growth driver, as conditions such as diabetes, heart disease and respiratory illness account for the majority of health spending and respond favorably to early, coordinated care. Payers and providers require tools to determine which individuals are at risk, monitor progress and allocate scarce care team capacity to the patients who stand to benefit most. Population aging in North America, Europe and Asia increases the number of people managing multiple conditions, which strengthens the case for systematic programs that follow each person over time. Care teams using risk lists to prioritize outreach report better use of limited staff time, reinforcing support for further investment.
Financial incentives amplify this effect, because accountable care contracts, shared savings and Medicare Advantage rules reward organizations that reduce costs and raise quality. AI analytics extend the benefit by improving risk prediction and automating outreach, allowing small teams to manage large populations. Wider adoption of unified records and interoperability standards simplifies the combination of clinical and claims data, which improves model accuracy and the return on platform investment. Employers and public programs apply the same logic, adding buyers that seek to contain costs through prevention and chronic care support.
⮞The Pan American Health Organization reported in July 2025 that deaths from noncommunicable diseases in the Americas have risen 43% since 2000 and now represent about 65% of regional mortality. This trajectory adds weight to the case for population-level programs.
Restraints: Data Privacy, Fragmented Data and Implementation Costs Restrain Growth in the Population Health Management Market
Data privacy and security obligations constrain the pace at which organizations can share and analyze patient information. Platforms process clinical, claims and social data from numerous sources, so breaches can result in penalties and erosion of trust, and compliance reviews extend purchasing cycles. Storage of sensitive records in the cloud remains a concern in certain countries, and data residency rules raise costs. Smaller providers frequently hesitate to adopt tools that require data sharing with partners outside their control. Many vendors are responding with investments in privacy controls and certifications, although these measures add cost and time.
Fragmented and incomplete data further slows outcomes, since records are dispersed across many systems and often lack consistent coding or social information. Fragmentation between provider, payer and community sources remains the largest technical obstacle for new programs and commonly delays the first measurable results. Integration and implementation costs are high, and organizations need multidisciplinary teams of analysts, clinicians and care managers who are difficult to recruit. Limited reimbursement for preventive and care coordination activity in many systems delays financial returns, and digital skills gaps among staff and patients reduce adoption in emerging markets.
⮞In November 2025, the Africa Centres for Disease Control and Prevention reported that only about 30% of primary health care systems in Africa are digitalized. The shortfall illustrates how limited data infrastructure can hold back population programs.
Opportunities: Technology-Enabled Chronic Care, Social Data Integration and Health Data Spaces Create Opportunities in the Population Health Management Market
Technology-enabled chronic care presents a sizable opportunity as payers and governments introduce payment models that reward remote monitoring and measurable outcomes. Hospital-at-home programs, virtual care and disease-specific platforms for cancer, kidney disease, heart disease and behavioral health allow vendors to develop focused products with clear financial value. Suppliers that merge monitoring data with risk models and care team workflows can demonstrate savings quickly, which appeals to providers and insurers seeking quantifiable results. Payers funding these programs also gain faster visibility into risk, supporting contracts built around shared savings.
The integration of social determinants of health, behavioral health and pharmacy data into a single view offers a complementary opening, since these inputs explain a large proportion of avoidable cost. Emerging markets in Asia Pacific, the Middle East and Latin America are building national records and programs that require analytics and engagement tools. Partnerships among record vendors, analytics firms and insurers can accelerate adoption by packaging data, models and services into a single offering. Suppliers that provide data standards and models for these programs can reach new customer groups rapidly, a prospect strengthened by public funding for primary care digitization in several regions.
⮞The European Health Data Space Regulation entered into force in March 2025, with key provisions applying from March 2029. The European Commission expects the framework to deliver savings of EUR 11 billion over a decade.
Recent Developments:
-
In January 2025, Innovaccer secured USD 275 million in a Series F funding round to scale its healthcare intelligence cloud. The capital is intended to support the expansion of its data and AI platform for provider and payer customers.
-
In July 2025, ZeOmega and MedeAnalytics introduced the Population Health Navigator, a jointly developed solution that places analytics directly at the disposal of care management teams. The product delivers risk and quality insight at the point where care managers make decisions.
-
In December 2025, Lightbeam Health Solutions acquired Syntax Health, adding value-based contracting and incentive design capabilities. The transaction extends the platform from care gap management into contract and incentive planning.
-
In October 2026, Arcadia launched Ascent, CareJourney and LifeScience at its annual conference, presenting an agentic population health platform. The release adds AI agents and benchmarking data to the company's offering.
Population Health Management Market Key Players
-
Innovaccer Inc.
-
Arcadia
-
Health Catalyst, Inc.
-
Oracle Corporation (Oracle Health)
-
Optum, Inc. (UnitedHealth Group)
-
Epic Systems Corporation
-
Azara Healthcare (including i2i Population Health)
-
ZeOmega Inc.
-
Lightbeam Health Solutions
-
Lumeris
-
Elligint Health (HealthEC and VirtualHealth)
-
Milliman MedInsight
-
MedeAnalytics, Inc.
-
athenahealth, Inc.
-
Veradigm Inc.
-
Persivia
-
Medecision
-
Netsmart Technologies, Inc.
-
WellSky
-
Inovalon
Population Health Management Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 85.90 Billion |
| Market Size by 2035 | USD 508.41 Billion |
| CAGR | CAGR of 19.46% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Services and Software) • By Delivery Mode (Cloud-Based, On-Premise, and Hybrid) • By Application (Population Health Analytics, Patient Engagement, Care Coordination, Data Integration and Management, and Other Applications) • By End User (Healthcare Providers, Healthcare Payers, Employer Groups, and Government and Other End Users) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Innovaccer Inc., Arcadia, Health Catalyst, Inc., Oracle Corporation (Oracle Health), Optum, Inc. (UnitedHealth Group), Epic Systems Corporation, Azara Healthcare (including i2i Population Health), ZeOmega Inc., Lightbeam Health Solutions, Lumeris, Elligint Health (HealthEC and VirtualHealth), Milliman MedInsight, MedeAnalytics, Inc., athenahealth, Inc., Veradigm Inc., Persivia, Medecision, Netsmart Technologies, Inc., WellSky, Inovalon |

Frequently Asked Questions
Some of the major companies operating in the Population Health Management Market include Innovaccer, Arcadia, Health Catalyst, Oracle Health, Optum, Epic Systems, Azara Healthcare, ZeOmega, Lightbeam Health Solutions, Lumeris, Elligint Health, Milliman MedInsight, MedeAnalytics, athenahealth, Veradigm, Persivia, Medecision, Netsmart, WellSky and Inovalon.
Key opportunities include technology-enabled chronic care and hospital-at-home programs, the integration of social determinants, behavioral health and pharmacy data into a single view, and new national health data programs in Asia Pacific, the Middle East and Latin America.
The rising burden of chronic disease, together with the shift to value-based payment and the spread of AI analytics, is the key growth factor for the market.
By Component, the Services segment dominated the Population Health Management Market with approximately 58.43% share in 2025, owing to the dependence of population health programs on data integration, workflow design and care management support that most organizations cannot build internally.
North America dominated the Population Health Management Market with a share of 48.14% in 2025, supported by accountable care programs, the growth of Medicare Advantage and high chronic disease costs.
