
Radiation Hardened Electronics Market Report Scope & Overview:
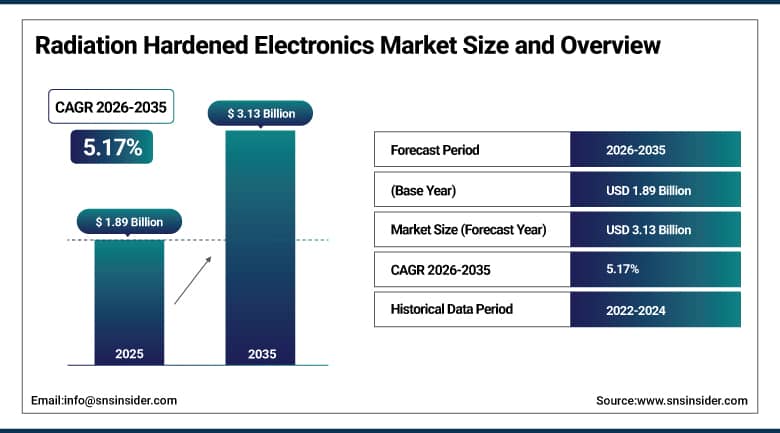
The Radiation Hardened Electronics Market was valued at USD 1.89 Billion in 2025 and is estimated at USD 1.99 Billion in 2026. It is projected to reach USD 3.13 Billion by 2035, advancing at a CAGR of 5.17% from 2026 to 2035. Satellite constellations, defense space programs, crewed lunar missions, and nuclear power projects all require components that keep working under ionizing radiation, where ordinary parts suffer data corruption or permanent damage. Designers are moving to advanced process nodes, plastic packages, and wide-bandgap power devices, which widens the range of suppliers and applications served.
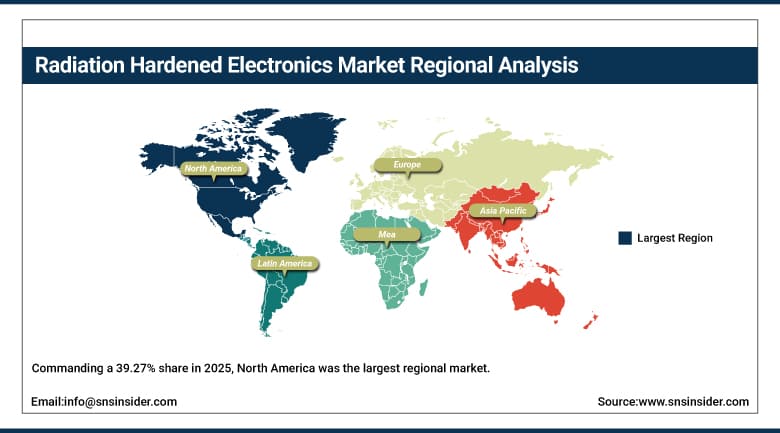
North America was the largest regional market in 2025 with a 39.27% share, supported by government space and defense budgets, trusted foundry programs, and a deep base of qualified suppliers. Asia Pacific is expected to grow fastest over the forecast period as China, India, and Japan expand launch rates and local satellite manufacturing, while Europe benefits from sovereign space programs and space-grade semiconductor initiatives. Latin America and the Middle East & Africa remain smaller but are adding satellite and research capacity. Together, these dynamics keep demand resilient even in years when launch schedules slip.
To Get More Information On Radiation Hardened Electronics Market - Request Free Sample Report
Key Report Takeaways:
-
By component, power management held a 28.63% share in 2025, while memory is the fastest growing.
-
By manufacturing technique, radiation hardening by design accounted for a 53.18% share in 2025, while radiation hardening by process is the fastest growing.
-
By application, space represented a 51.93% share in 2025, while medical is the fastest growing.
-
By material, silicon commanded a 66.12% share in 2025, while gallium nitride is the fastest growing.
-
By region, North America led with a 39.27% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights:
Radiation-tolerant commercial and plastic-packaged parts are entering low Earth orbit programs. Satellite builders producing hundreds of units cannot afford fully qualified ceramic parts for every socket, so suppliers offer screened plastic devices backed by new qualification standards and lot testing.
Advanced process nodes are reaching space compute. Fully depleted silicon-on-insulator and FinFET platforms now underpin rad-hard processors and field-programmable gate arrays, giving on-board artificial intelligence and image processing the performance that older nodes could not provide.
Wide-bandgap power devices are gaining qualification. Gallium nitride and silicon carbide switches offer higher efficiency and smaller size for satellite power systems, and suppliers are releasing devices tested for total ionizing dose and single-event effects.
Drivers Impact Analysis:
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Low Earth Orbit Constellations and Smallsat Programs |
+2.46% |
North America, Europe, and Asia Pacific |
Short term (2 years or less) |
|
Defense and Space Budget Expansion |
+1.92% |
North America, Europe, and Asia Pacific |
Medium term (2 to 4 years) |
|
Deep-Space and Lunar Mission Activity |
+1.04% |
North America, Europe, and Asia Pacific |
Long term (4 years or more) |
|
Nuclear Power New Build and Life Extension |
+0.88% |
Asia Pacific, Europe, and Middle East & Africa |
Long term (4 years or more) |
|
Advanced-Node and Wide-Bandgap Device Adoption |
+0.77% |
North America and Europe |
Medium term (2 to 4 years) |
Low Earth Orbit Constellations and Smallsat Programs
Commercial and government operators are launching large fleets for communications, earth observation, and navigation, and each satellite carries processors, memory, power converters, and data converters that must tolerate radiation. Orbits are becoming crowded, and the European Space Agency's Space Environment Report 2025, issued in April 2025, counted about 11,000 active payloads among roughly 40,000 tracked objects. Volume production pushes suppliers toward radiation-tolerant plastic parts and shorter qualification flows, which increases unit shipments even where prices per device are lower than for traditional ceramic components.
Defense and Space Budget Expansion
Governments are raising spending on missile warning, secure communications, and space domain awareness, and these systems rely on radiation hardened processors and memory that can survive both natural and hostile radiation. The U.S. Department of the Air Force requested USD 71.10 Billion for the Space Force in its fiscal year 2027 budget in April 2026, a sharp rise over the prior year. European and Asian governments are following with sovereign space and defense plans, which supports multiyear demand for qualified electronics and trusted manufacturing.
Deep-Space and Lunar Mission Activity
Missions beyond low Earth orbit expose electronics to higher doses of radiation and to long operating lives, so designers specify the most robust devices available. NASA launched Artemis II on 1 April 2026 and completed the crewed lunar flyby later in the month, which demonstrated flight hardware for the Moon and set the stage for surface operations. Planetary science, lunar landers, and space stations create recurring demand for processors, memory, and power devices with proven radiation performance, often in small batches at high unit prices.
Nuclear Power New Build and Life Extension
Reactor instrumentation, robotics for inspection and decommissioning, and fuel handling equipment operate in radiation fields that damage standard semiconductors. The International Atomic Energy Agency reported in August 2025 that 417 reactors were operating in 31 member states and 62 were under construction in 15 countries. New plants in Asia and the Middle East, along with life extensions in North America and Europe, call for qualified sensors, controllers, and communication devices, and small modular reactor designs add further opportunities. Operators also require long-term parts availability.
Advanced-Node and Wide-Bandgap Device Adoption
Onboard processing of imagery, signals, and navigation data requires more computing performance than legacy radiation hardened processors deliver. In January 2026 the European Cooperation for Space Standardization introduced the ESCC 9030 standard for high-performance microcircuits in plastic or flip-chip packages, which provides a qualification route for modern devices. Gallium nitride power transistors and fully depleted silicon-on-insulator logic raise the performance of power and compute subsystems, allowing suppliers to command higher content per spacecraft. Suppliers that invest early in qualification can secure position in programs that run for a decade or longer.
Restraints Impact Analysis:
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Qualification Cost and Long Qualification Cycles |
-0.82% |
Global |
Medium term (2 to 4 years) |
|
Limited Foundry Capacity and Supplier Base |
-0.58% |
North America and Europe |
Long term (4 years or more) |
|
Export Control Restrictions |
-0.31% |
Asia Pacific and Europe |
Medium term (2 to 4 years) |
|
Small Volumes Relative to Commercial Semiconductors |
-0.19% |
Global |
Long term (4 years or more) |
High Qualification Cost and Long Qualification Cycles
Qualifying a radiation hardened device requires wafer lot testing, heavy-ion and total dose irradiation, thermal and mechanical screening, and detailed documentation, and the process commonly takes between one and three years. New entrants must fund this work before they can sell, and any change in process or design can force requalification. Costs are spread over small production volumes, so unit prices remain high and program managers sometimes delay adoption of new parts, which slows revenue growth for suppliers of advanced devices.
Limited Foundry Capacity and Supplier Base
Only a handful of foundries maintain specialized processes for radiation hardening, and many of them operate older nodes that cannot deliver the performance sought by modern payloads. The U.S. Department of Defense committed USD 16.00 Million under Defense Production Act Title III in September 2026 to re-establish a 45 nm silicon-on-insulator storefront, a sign of how fragile the supply base has become. A single fab interruption can delay satellite programs, and limited alternatives restrict price competition. Alternative sources remain scarce for many process nodes.
Export Control Restrictions
Radiation hardened electronics are controlled under export regimes in the United States and Europe, so shipments to many customers need licenses and end-use checks. Satellite builders in Asia, the Middle East, and Latin America often face long approval times or restricted access to the most capable devices. Buyers respond by qualifying local sources or redesigning around uncontrolled parts, which fragments demand and favors regional programs. Suppliers also carry compliance cost and risk, which makes smaller export opportunities less attractive. Delays are common.
Small Volumes Relative to Commercial Semiconductors
The Semiconductor Industry Association reported global chip sales of USD 791.70 Billion in 2025 when it released annual figures in February 2026, and radiation hardened devices account for a tiny fraction of that total. Fabs tend to give priority to large commercial customers, and rad-hard product lines depend on a few programs for most of their volume. This imbalance limits investment in new process generations, keeps design resources scarce, and leaves buyers exposed to sudden changes in supplier priorities. Tiny volumes constrain scale.
Radiation Hardened Electronics Market Segment Analysis:
By Component, Power Management Dominates Radiation Hardened Electronics Market; Memory to Register Fastest Growth.
Power management devices lead because every spacecraft, weapon system, and nuclear instrument needs regulators, converters, and switches that hold output steady while radiation degrades the semiconductor. Designers often choose power components first, since failure at this level disables the entire payload. Established suppliers hold deep portfolios of space-qualified controllers and field-effect transistors, and long program lifetimes protect repeat orders. Power management held 28.63% of the market in 2025. Long flight heritage also reassures program managers about reliability and lifetime.
Memory is advancing quickest as satellites process more imagery and sensor data on board and need larger storage close to the processor. Radiation-tolerant dynamic memory, flash storage, and magnetoresistive devices are entering production, and spacecraft makers want capacity measured in gigabytes instead of megabytes. Artificial intelligence workloads at the edge add further requirements, and these needs underpin a CAGR of 6.77% from 2026 to 2035. Suppliers are responding with higher-density parts built on newer nodes and packaged for launch environments.
By Manufacturing Technique, Radiation Hardening by Design Dominates Radiation Hardened Electronics Market; Radiation Hardening by Process to Register Fastest Growth.
Radiation hardening by design relies on circuit layout rules, redundancy, and error-correcting logic applied to commercial foundry processes, which avoids the expense of dedicated fabrication lines. Designers can reuse standard libraries, move to newer nodes sooner, and iterate faster than with process-based methods. Programs with tight budgets and short schedules prefer it, and this approach captured 53.18% of the market in 2025. Foundry partnerships let design houses access modern libraries while keeping verification effort manageable for small teams.
Radiation hardening by process is growing fastest because deep-space, human-rated, and strategic defense programs demand tolerance that layout methods cannot guarantee alone. Specialized silicon-on-insulator and silicon-on-sapphire flows deliver high total dose and latch-up immunity. Government funding is reviving domestic and allied fabrication capacity for these processes, which supports a CAGR of 6.74% from 2026 to 2035. Allied governments view these processes as strategic, and they are offering contracts that guarantee volumes to keep fabrication lines economically viable over time.
By Application, Space Dominates Radiation Hardened Electronics Market; Medical to Register Fastest Growth.
Space remains the primary buyer because satellites, launch vehicles, and probes operate in constant radiation exposure and cannot be repaired after launch. Communications, navigation, observation, and science missions all specify qualified parts, and the growth of commercial constellations has multiplied the number of spacecraft being built each year. Government agencies also fund long-duration exploration programs. Space applications accounted for 51.93% of the market in 2025. Launch rates continue to rise steadily each year across commercial, civil, and government operators.
Medical applications are growing fastest as proton and heavy-ion therapy centers, radiotherapy equipment, and advanced imaging systems expand in hospitals around the world. These systems expose control and sensing electronics to repeated radiation, and cancer centers need dependable operation across long duty cycles. Investment in particle therapy facilities, particularly in Asia and Europe, supports a CAGR of 6.31% from 2026 to 2035. Hospitals also value electronics that need little recalibration after repeated exposure, which lowers maintenance costs and downtime.
By Material, Silicon Dominates Radiation Hardened Electronics Market; Gallium Nitride to Register Fastest Growth.
Silicon continues to dominate because the vast majority of processors, memory, and mixed-signal devices are manufactured on silicon, and decades of radiation testing have produced well-characterized processes. Silicon-on-insulator variants reduce charge collection and improve single-event resistance, which makes them the base for most flight-proven designs. Manufacturing infrastructure and design tools are also mature. Silicon represented 66.12% of the market in 2025. Costs per device are also lower than for alternative materials, which keeps silicon attractive for large production runs.
Gallium nitride is expected to grow fastest as satellite power systems and radio-frequency payloads seek higher efficiency, lower mass, and higher switching speeds than silicon allows. The material tolerates high levels of ionizing radiation, and qualified power transistors and drivers are appearing from several suppliers. Smaller power converters help reduce launch weight, and these advantages support a CAGR of 5.96% from 2026 to 2035. Several suppliers have already released qualified devices, which lowers adoption risk for cautious program managers.
Geography Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
88.14% |
|
Europe |
Germany |
28.37% |
|
Asia Pacific |
China |
33.46% |
|
Middle East & Africa |
Saudi Arabia |
29.84% |
|
Latin America |
Brazil |
46.17% |
North America Radiation Hardened Electronics Market
Commanding a 39.27% share in 2025, North America was the largest regional market. The region combines the world's largest government space and defense budgets with a cluster of qualified suppliers, trusted foundries, and test facilities for radiation effects. Commercial constellation operators, launch providers, and national security programs all place orders for rad-hard processors, memory, and power parts. Federal funding for foundry modernization further strengthens the supplier base for future programs. Established test facilities for heavy-ion and proton irradiation also shorten qualification schedules for new devices.
The United States contributed USD 654.18 Million in 2025 and is forecast to grow at a CAGR of 5.52% from 2026 to 2035. NASA awarded a USD 50.00 Million contract in August 2022 for a high-performance spaceflight computing processor offering at least 100 times the capacity of current flight computers. Canada adds activity through its space agency programs and satellite manufacturers, which buy components from U.S. and European suppliers. Space agency and defense programs remain the largest buyers of the most demanding devices.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Radiation Hardened Electronics Market
Asia Pacific is the fastest-growing region, expected to expand at a CAGR of 6.26% from 2026 to 2035. China is increasing launch cadence and building large constellations, India is developing indigenous processors for its space missions, and Japan and South Korea are strengthening satellite and launch capabilities. Governments encourage local component production to reduce reliance on controlled imports, and this policy supports new radiation hardened product lines. Japan and South Korea add demand through navigation, earth observation, and defense satellite programs that favor locally supported suppliers.
Nuclear power build-out is another source of demand, with reactors under construction in China, India, and South Korea requiring qualified instrumentation. Particle therapy centers in Japan and China add medical demand. Export control limits on imported devices push regional engineers toward domestic alternatives, and test infrastructure for heavy-ion and proton irradiation is expanding at universities and national laboratories across the region. Commercial launch startups and satellite manufacturers in the region are also exploring lower-cost plastic parts for constellation programs, which broadens the buyer base beyond state agencies.
Europe Radiation Hardened Electronics Market
Europe holds a significant position through national space agencies, the European Space Agency, and defense programs that favor sovereign sources of critical electronics. France, Germany, Sweden, and the United Kingdom host suppliers of processors, memory, and field-programmable gate arrays for flight, and regional qualification standards from the space standardization community guide procurement. Programs for secure connectivity constellations add further volume. Radiation test centers in Belgium, Germany, and France support qualification campaigns, and agency programs fund development of European sources for critical components.
European buyers are cultivating independent supply chains for processors and programmable logic to reduce dependence on controlled imports. Public funding supports fully depleted silicon-on-insulator production in the region, and agency-backed microcontroller projects are reaching flight. Nuclear fleets in France and the United Kingdom, along with research facilities such as particle accelerators, create supplementary demand for radiation tolerant sensing and control devices. Competition from imported devices remains strong, so European suppliers focus on performance at advanced nodes and on offering shorter delivery times to regional satellite manufacturers.
Middle East & Africa Radiation Hardened Electronics Market
Middle East & Africa is a smaller region where demand is concentrated in Gulf states building national satellite capabilities and nuclear energy programs. The United Arab Emirates has an established space agency and lunar and planetary missions, and Saudi Arabia is expanding its space sector under national diversification plans. Most spacecraft are built with foreign partners, so electronics are typically imported from North American and European suppliers. Government funding for space centers and university programs is steadily building local engineering skills.
Nuclear power adds demand as the United Arab Emirates operates its first commercial reactors and other states evaluate new plants. Africa shows early-stage activity, with Egypt, South Africa, and Nigeria operating earth observation and communications satellites through partnerships. Funding, workforce, and export approvals are constraints, but regional agencies are building engineering teams and ground infrastructure that will support additional missions over time. Regional partnerships with established manufacturers offer a route to technology transfer, and small satellite programs in the region continue to expand their orders for qualified parts.
Latin America Radiation Hardened Electronics Market
Latin America is the smallest region, led by Brazil, which maintains satellite programs, a launch center, and a nuclear power sector. Argentina builds earth observation and communications satellites through its national space agency, while Mexico and Chile are growing their involvement with small satellite constellations. Most requirements are met through imports of qualified parts, often bundled with spacecraft purchased from foreign manufacturers. Regional universities also contribute to payload design, and a growing number of small satellite startups are creating demand for low-cost radiation tolerant devices.
Demand is influenced by national space plans, university programs, and nuclear research reactors. Budget limits and export license requirements restrict the range of devices that regional programs can buy, so many projects favor lower-cost radiation tolerant parts. Partnerships with North American and European suppliers, along with cooperation among regional space agencies, are expected to widen access to qualified components in the coming decade. Cooperation agreements among national agencies and technology transfer provisions in satellite purchase contracts help build local expertise over time.
Competitive Landscape:
The market is moderately concentrated. A group of defense prime-affiliated microelectronics units, global semiconductor companies with space product lines, and specialist radiation hardened design houses supplies most qualified devices, while smaller firms serve targeted components such as memory or programmable logic. Competition revolves around flight heritage, qualification level, performance at advanced nodes, supply security, and ability to meet export and trusted-source requirements.
Vendors pursue acquisitions, product launches, and foundry partnerships to secure capacity. Companies are combining radiation hardened microcontroller and processor assets under larger semiconductor portfolios, expanding storefront programs at commercial foundries, and launching radiation-tolerant plastic parts aimed at low Earth orbit constellations. Strategic alliances with space agencies and satellite manufacturers help secure early design wins for new platforms.
Radiation Hardened Electronics Market Industry Leaders:
1. BAE Systems: Developer of radiation hardened processors, single-board computers, and custom ASICs for space and defense programs, operating as a trusted source.
2. Microchip Technology: Supplier of radiation tolerant and radiation hardened microcontrollers, programmable logic, power devices, and a high-performance spaceflight processor family.
3. Renesas Electronics: Provider of Intersil-brand radiation hardened power, data communication, and protection integrated circuits qualified to space-level standards.
4. Infineon Technologies: Supplier of radiation hardened power integrated circuits and transistors, including controllers rated for high total ionizing dose levels.
5. STMicroelectronics: Manufacturer of radiation hardened discrete, analog, and logic devices, and of the fully depleted silicon-on-insulator process used for European space programmable logic.
Companies Covered in this Report:
-
BAE Systems
-
Microchip Technology
-
Renesas Electronics
-
Infineon Technologies
-
Texas Instruments
-
Analog Devices
-
Teledyne Technologies
-
Honeywell Aerospace
-
Frontgrade Technologies
-
Data Device Corporation
-
GSI Technology
-
QuickLogic
-
NanoXplore
Recent Developments:
-
July 2025: Frontgrade Technologies introduced a 32 GB radiation-tolerant eMMC storage device for low Earth orbit satellites, with flight units planned for the fourth quarter of 2025.
-
August 2025: Texas Instruments supplied radiation hardened power devices, data converters, interface circuits, and clocking parts used on the NISAR earth observation satellite.
-
October 2025: Infineon Technologies launched the RIC70847 radiation hardened buck controller with integrated gate drive, rated to 100 krad(Si).
-
November 2025: BAE Systems announced the RH12 storefront for custom radiation hardened chips built on a 12LP FinFET platform in Malta, New York.
-
December 2025: QuickLogic expanded its strategic radiation hardened FPGA contract to a 12LP process and completed tape-out of a test chip.
-
March 2026: Teledyne Technologies began full production of its 16 GB DDR4 radiation-tolerant flight memory modules.
-
October 2026: Microchip Technology acquired VORAGO Technologies, a supplier of radiation hardened Arm microcontrollers and processors.
Scope and Research Methodology
This report defines the Radiation Hardened Electronics Market as the commercial value of integrated circuits, memory, processors, programmable logic, power devices, and related components designed or manufactured to withstand ionizing radiation, sold for space, aerospace and defense, nuclear power, medical, and other uses. It covers radiation hardened and radiation tolerant products built by design, by process, or with shielding. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. Segmentation covers component, manufacturing technique, application, material, and region. Services such as qualification testing and design support are excluded unless sold with the device.
Secondary research forms the first layer of work and draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research follows through structured interviews and surveys with executives, product and business heads, procurement managers, and end-user stakeholders across the value chain. Responses are used to validate assumptions, adoption rates, and pricing, and to test how demand is likely to change by region and application. Analysts also review qualification records and program announcements. Findings from both routes are cross-referenced before use. Analysts also review launch manifests and procurement notices for satellite programs.
Market engineering begins with a bottom-up build from vendor revenue and shipment data, which is then cross-checked top-down against end-user spending and sector indicators such as satellite launches and defense budgets. Triangulation continues until the two routes converge. The forecast reflects adoption trends, regulation, technology change, and macroeconomic conditions, and sensitivity checks test the stability of key assumptions. Senior analysts review every estimate and narrative section for accuracy and consistency before the final model is released. Regional estimates are checked against national space and defense budgets, launch statistics, and reactor programs so that country totals align with the global figure.
Radiation Hardened Electronics Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.89 Billion |
| Market Size by 2035 | USD 3.13 Billion |
| CAGR | CAGR of 5.17% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Power Management, Mixed-Signal ICs, Processors and Controllers, Memory, and Others) • By Manufacturing Technique (Radiation Hardening by Design, Radiation Hardening by Process, and Radiation Hardening by Shielding) • By Application (Space, Aerospace and Defense, Nuclear Power Plants, Medical, and Others) • By Material (Silicon, Silicon Carbide, Gallium Nitride, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BAE Systems, Microchip Technology, Renesas Electronics, Infineon Technologies, STMicroelectronics, Texas Instruments, Analog Devices, Teledyne Technologies, Honeywell Aerospace, Frontgrade Technologies, AMD, Data Device Corporation, GSI Technology, QuickLogic, NanoXplore |

Frequently Asked Questions
The market was valued at USD 1.89 Billion in 2025 and is estimated at USD 1.99 Billion in 2026. It is forecast to reach USD 3.13 Billion by 2035.
The Commercial-off-the-Shelf (COTS) Segment is leading in the market revenue share in 2023.
The market is projected to expand at a CAGR of 5.17% from 2026 to 2035.
North America led with a 39.27% share in 2025. Asia Pacific is the fastest-growing region, with a CAGR of 6.26% from 2026 to 2035.
Power management, radiation hardening by design, space, and silicon lead their axes. Memory, radiation hardening by process, medical, and gallium nitride grow fastest.
BAE Systems, Microchip Technology, Renesas Electronics, Infineon Technologies, and STMicroelectronics are the best-documented suppliers.
High qualification cost and long cycles, limited foundry capacity, export control restrictions, and small volumes relative to commercial semiconductors are the main challenges.
