
Semiconductor in Military and Aerospace Market Report Scope & Overview:
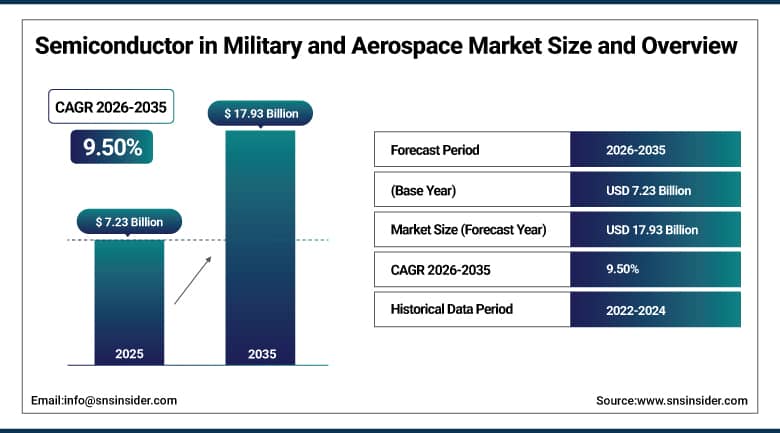
The Semiconductor in Military and Aerospace Market was valued at USD 7.23 Billion in 2025 and is expected to reach USD 17.93 Billion by 2035, growing at a CAGR of 9.50% from 2026 to 2035.
The growth rate of the semiconductor in the military and aerospace market is very fast because of the modernization and upgrading of aircraft and the increasing requirement for advanced defense systems, which includes unmanned aerial vehicles, radar systems, and guided ammunition. The semiconductor in military and aerospace is a unique kind of component for the electronics industry that provides an electronic component to perform communication, navigation, surveillance, and weapon guidance and needs to have superior thermal properties and high radiation tolerance and longevity compared to normal semiconductors used in general commercial applications.
In addition, the growth of the market is supported by the application of AI and machine learning in avionics and defense electronics, the increase in the usage of gallium nitride and silicon carbide semiconductor for radiation tolerance and high reliability, and the growth of defense infrastructure in space.
About 60% of current military and aerospace technology depends on semiconductors for functions like communications, navigation, and surveillance, thus highlighting the vital importance of these devices in securing the efficiency and reliability of the ever-evolving high-tech military and aviation technologies around the world.
To Get More Information On Semiconductor in Military and Aerospace Market - Request Free Sample Report
Semiconductor in Military and Aerospace Market Trends
- Rising AI and edge computing adoption is increasing demand for high-performance semiconductors processing complex sensor data in real time.
- Growing compound semiconductor adoption is supporting radiation-tolerant and thermally efficient defense and aerospace electronics.
- Increasing COTS component adoption is expanding access to commercially available semiconductors for non-critical military applications.
- Expanding UAV and drone deployment is driving demand for compact, low-power, high-performance semiconductor solutions.
- Strategic partnerships are accelerating development of radiation-tolerant, mission-critical semiconductor technologies for aerospace and defense applications.
The U.S. Semiconductor in Military and Aerospace Market Outlook
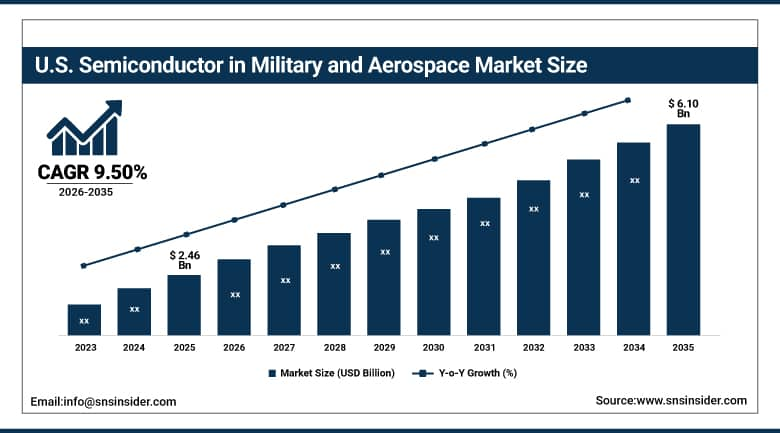
The U.S. Semiconductor in Military and Aerospace Market was valued at USD 2.46 Billion in 2025 and is projected to reach USD 6.10 Billion by 2035, growing at a CAGR of 9.50% during 2026–2035.
The top defense contractors and semiconductor companies in the country continue to invest in military and aerospace semiconductors as a result of continued modernization efforts in the Defense Department as well as increased production of radiation-hardened and compound semiconductors in the country. Increased investments in future combat systems and modernization of the current military fleets, as well as the increased need for space-based military and satellite communications infrastructure, ensure that there will be continued domestic demand for advanced semiconductors in the country's defense and aerospace industry.
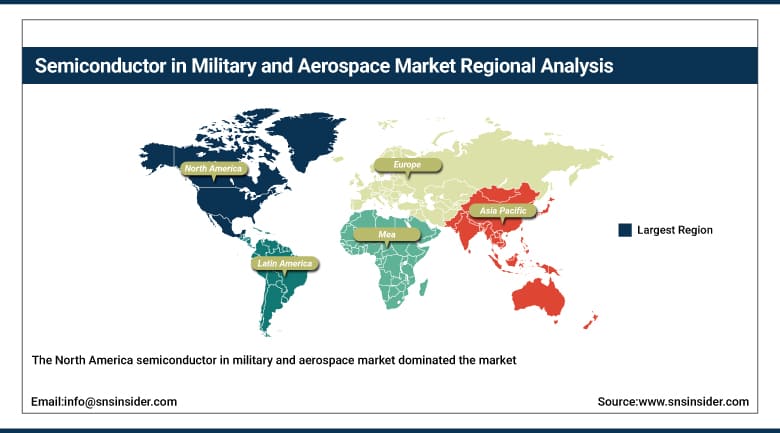
North America dominated the semiconductor in military and aerospace market, accounting for a substantial growth share during the forecast period, supported by sustained Pentagon investment in next-generation combat platforms and continued modernization of existing military fleets requiring advanced radiation-hardened electronic components.
Semiconductor in Military and Aerospace Market Segment Analysis
- By Component, integrated circuits dominated the semiconductor in military and aerospace market with a 52.60% share in 2025, while optical devices is the fastest-growing component segment with a CAGR of 9.90% from 2026–2035.
- By Application, imaging & radar dominated the semiconductor in military and aerospace market with a 34.60% share in 2025, while electronic warfare is the fastest-growing application segment with a CAGR of 10.40% from 2026–2035.
- By End User, defense dominated the semiconductor in military and aerospace market with a 46.80% share in 2025, while space systems is the fastest-growing end user segment with a CAGR of 11.00% from 2026–2035.
- By Technology, radiation-hardened dominated the semiconductor in military and aerospace market with a 44.60% share in 2025, while compound semiconductors (GaN/SiC) is the fastest-growing technology segment with a CAGR of 10.80% from 2026–2035.
By Component, integrated circuits dominated the semiconductor in military and aerospace market, while optical devices is the fastest-growing segment.
The integrated circuits segment dominated the semiconductor in military and aerospace market with a revenue share of 52.60% in 2025. Integrated circuits are still the prevailing components because of the essential presence of microcontrollers, application specific integrated circuits (ASICs), field-programmable gate arrays (FPGAs), and digital signal processors in nearly all subsystems of the military electronics equipment, including, for instance, the AN/APG-81 AESA radar of the F-35 Lightning II that employs radiation-hardened transmit/receive modules ICs in its active array.
The optical device segment is projected to expand at a CAGR of 9.90% during the forecast period 2026-2035, with the increasing use of optical sensors, laser systems, and photonic components driving strong demand. Growing integration of advanced targeting, range finding, and directed-energy systems across modern military platforms is expanding the role of optical semiconductor devices beyond traditional imaging applications into increasingly sophisticated defense electronic warfare and precision guidance systems.
By Application, imaging & radar dominated the semiconductor in military and aerospace market, while electronic warfare is the fastest-growing segment.
The imaging & radar segment dominated the semiconductor in military and aerospace market with a revenue share of 34.60% in 2025. Imaging and radar applications remain the dominant category owing to their critical role in surveillance, target acquisition, and navigation systems that must operate reliably in harsh environments, including low-light and high-temperature conditions, while resisting electromagnetic interference across virtually every major military platform requiring situational awareness capability.
The electronic warfare segment is expected to register the fastest CAGR of 10.40% during the forecast period 2026-2035. Field-Programmable Gate Arrays capable of reconfiguring and adapting to evolving threat conditions have become indispensable components of electronic countermeasure systems, driving strong demand as defense organizations increasingly prioritize adaptive, software-defined electronic warfare capability across next-generation combat platforms.
By End User, defense dominated the semiconductor in military and aerospace market, while space systems is the fastest-growing segment.
The defense segment dominated the semiconductor in military and aerospace market with a revenue share of 46.80% in 2025. Defense applications remain the largest end-user category owing to sustained government investment in advanced defense technologies, including guided munitions, combat aircraft, and communication systems, representing the foundational and most substantial semiconductor demand driver across the broader military and aerospace electronics ecosystem.
The space systems segment is anticipated to grow at a CAGR of 11.00% during the forecast period 2026-2035, driven by expansion of space-based defense and satellite communication infrastructure. The Space-Based Infrared System missile warning constellation illustrates the radiation-hardened semiconductor demand profile of mature military space programs, where each satellite requires dedicated rad-hard signal processors, power management ICs, and image sensor arrays operating under continuous ionizing radiation conditions.
By Technology, radiation-hardened dominated the semiconductor in military and aerospace market, while compound semiconductors (GaN/SiC) is the fastest-growing segment.
The radiation-hardened segment dominated the semiconductor in military and aerospace market with a revenue share of 44.60% in 2025. Radiation-hardened technology remains the dominant category owing to its essential role in satellite payloads, space systems, and high-altitude defense platforms, where defense-specific IC variants including radiation-hardened ASICs demand distinct foundry qualifications that sustain demand resilience through the forecast period.
The compound semiconductors (GaN/SiC) segment is expected to witness the fastest CAGR of 10.80% during the forecast period 2026-2035. Compound semiconductor devices such as gallium nitride transistors and silicon carbide MOSFETs have found increased use due to their radiation hardening properties and reliability. Radiation hardening technology has become very important in the development of communication system components used in both military and satellite communications.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
44.80% |
|
Middle East & Africa |
UAE |
27.60% |
|
Latin America |
Brazil |
37.70% |
North America Semiconductor in Military and Aerospace Market Insights
The North America semiconductor in military and aerospace market dominated the market and accounted for the largest growth share during the forecast period, supported by extensive domestic defense electronics manufacturing infrastructure and sustained government investment in advanced military and aerospace modernization programs.
The US was the leading country within the North America semiconductor in military and aerospace market in 2025, driven by sustained Department of Defense modernization investment and strong domestic production of radiation-hardened and compound semiconductor components. Canada is contributing to regional growth through its own expanding aerospace and defense electronics manufacturing capability.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Semiconductor in Military and Aerospace Market Insights
The Europe semiconductor in military and aerospace market was a major contributor in 2025. This is attributed to the region's substantial aerospace manufacturing base, strong presence of leading defense contractors, and growing military modernization investment across member states pursuing enhanced defense electronic capability.
Germany is one of the major markets in Europe owing to its strong aerospace and defense electronics manufacturing base and presence of leading semiconductor technology providers. Other countries such as the United Kingdom and France, home to major aerospace and defense manufacturers, are also contributing to market growth through expanding military modernization investment.
Asia Pacific Semiconductor in Military and Aerospace Market Insights
The Asia Pacific semiconductor in military and aerospace market is expected to witness the fastest growth rate during the forecast period 2026-2035. The market growth is driven by rising defense budgets, expanding domestic aerospace manufacturing capability, and growing space program investment across the region's major and emerging economies.
China is one of the main growth drivers in the Asia Pacific semiconductor in military and aerospace market, owing to its rapidly expanding domestic defense electronics manufacturing capability and growing military modernization investment. Japan, South Korea, and India are also contributing to regional growth through expanding defense procurement and rising domestic aerospace semiconductor manufacturing investment.
Middle East & Africa and Latin America Semiconductor in Military and Aerospace Market Insights
Middle East & Africa and Latin American regions are gradually expanding semiconductor in military and aerospace adoption as defense and aerospace investment grows across both regions, supported by increasing regional military modernization and space program development.
Brazil is set to be a prominent Latin American market fueled by growing domestic aerospace and defense industry investment. The Middle East & Africa region has UAE and Saudi Arabia investing heavily in advanced military and aerospace technology as part of broader defense modernization strategies, driving sustained demand for advanced semiconductor components across the region's expanding defense procurement programs.
Market Dynamics
Growth Drivers: Rising aircraft modernization and defense technology demand driving market growth
Increased upgrading and modernization of aircraft and rising demand for advanced defense technologies, including unmanned aerial vehicles, sophisticated radar systems, and guided munitions, are among the primary drivers of the Semiconductor in Military and Aerospace Market. High-performance, high-reliability discrete semiconductor devices offering thermal performance, radiation resistance, and long-life support capabilities are increasingly critical to commercial, military, and space aerospace platforms requiring exceptional operational reliability.
Moreover, the need for semiconductors with high-performance is expected to increase due to rising demand for secure communication infrastructure and advancements like machine learning and artificial intelligence. The rise in complexity in avionics and flight control systems, increasing adoption of radar and communication technology, growing space exploration and satellite systems, and increased use of unmanned aerial vehicles and drones are some of the factors that will propel the demand in the coming years.
Restraints: High development costs and lengthy qualification cycles limiting market expansion
One of the significant impediments to the expansion of the market is the substantial costs involved in producing radiation-hardened and military-grade semiconductor parts that necessitate specific fabrication techniques and rigorous testing that is far more expensive than conventional semiconductor production.
Moreover, lengthy periods that military and aerospace semiconductors take to be certified and approved for use can result in delays in the development process of several years, thus resulting in a continuous gap between semiconductor advancements in the commercial space and defense-certified components. The problem of a shortage in semiconductor chips, as well as overall supply chain optimization difficulties, adds another layer of complexity to the defense procurement process.
Opportunities: Expansion of space systems and compound semiconductor adoption creating new growth avenues
Growth in space exploration and satellite constellations is expected to generate substantial opportunities for the Semiconductor in Military and Aerospace Market, as expanding space-based defense infrastructure requires dedicated radiation-hardened signal processors, power management ICs, and image sensor arrays capable of operating under continuous ionizing radiation conditions.
There is a considerable growth opportunity in the continued development of compound semiconductor technology, including gallium nitride and silicon carbide components, that offer superior radiation hardening and thermal performance for demanding defense applications. The expansion of defense modernization investment and domestic semiconductor manufacturing capability in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Mercury Systems launched an updated radiation-hardened processing module designed for space applications, offering enhanced computing performance for satellite payload and missile warning system customers.
- 2025: Microchip Technology expanded its radiation-tolerant FPGA product line, providing defense and space customers with reconfigurable logic components capable of withstanding harsh orbital radiation environments.
- 2026: Texas Instruments introduced a new space-grade power management integrated circuit, targeting satellite and space system manufacturers requiring reliable power delivery under continuous ionizing radiation conditions.
- 2026: Infineon Technologies expanded its gallium nitride semiconductor production capacity for defense radar applications, strengthening its ability to supply radiation-tolerant compound semiconductor components to military electronics customers.
Semiconductor in Military and Aerospace Market key players are:
- RTX Corporation (Raytheon Technologies)
- Northrop Grumman Corporation
- Lockheed Martin Corporation
- General Dynamics Corporation
- BAE Systems plc
- Airbus Group SE
- Infineon Technologies AG
- Intel Corporation (Altera)
- Microchip Technology Inc. (Microsemi)
- Texas Instruments Incorporated
- Honeywell International Inc.
- Thales Group
- L3Harris Technologies, Inc.
- Analog Devices, Inc.
- STMicroelectronics N.V.
- Renesas Electronics Corporation
- Teledyne Technologies Incorporated
- Mercury Systems, Inc.
- Curtiss-Wright Corporation
- Data Device Corporation
Semiconductor in Military and Aerospace Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.23 Billion |
| Market Size by 2035 | USD 17.93 Billion |
| CAGR | CAGR of 9.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Integrated Circuits, Sensors & Actuators, Optical Devices, Others) • By Application (Imaging & Radar, Communication & Navigation, Electronic Warfare, Guidance & Control) • By End User (Defense, Aerospace/Commercial Aviation, Space Systems) • By Technology (Radiation-Hardened, Commercial-Off-The-Shelf (COTS), Compound Semiconductors (GaN/SiC)) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | RTX Corporation (Raytheon Technologies), Northrop Grumman Corporation, Lockheed Martin Corporation, General Dynamics Corporation, BAE Systems plc, Airbus Group SE, Infineon Technologies AG, Intel Corporation (Altera), Microchip Technology Inc. (Microsemi), Texas Instruments Incorporated, Honeywell International Inc., Thales Group, L3Harris Technologies, Inc., Analog Devices, Inc., STMicroelectronics N.V., Renesas Electronics Corporation, Teledyne Technologies Incorporated, Mercury Systems, Inc., Curtiss-Wright Corporation, Data Device Corporation. |
Frequently Asked Questions
The Semiconductor in Military and Aerospace Market is expected to grow at a CAGR of 9.50% from 2026 to 2035.
The Semiconductor in Military and Aerospace Market was valued at USD 7.23 Billion in 2025.
The market is driven by increased upgrading and modernization of aircraft and rising demand for advanced defense technologies including UAVs, radar systems, and guided munitions.
The Integrated Circuits segment dominated the Semiconductor in Military and Aerospace Market in 2025, accounting for approximately 52.60% market share.
The North America region dominated the Semiconductor in Military and Aerospace Market in 2025.
