
Shrink Films Market Report Scope & Overview:
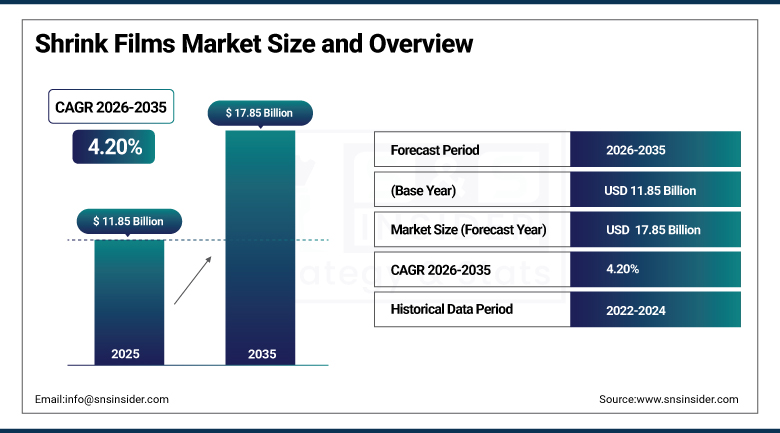
The Shrink Films Market was valued at USD 11.85 Billion in 2025 and is expected to reach USD 17.85 Billion by 2035, growing at a CAGR of 4.20% from 2026 to 2035.
The Shrink Films Market is growing steadily due to increasing activities in e-commerce and logistics, rising need for packaging films that are tamper-proof and moisture resistant, and continuous adoption of automated high-speed packaging lines in food, beverages, and consumer goods manufacturing sectors. Shrink films refer to flexible plastic film packaging products that shrink tightly on the packaged items or pallets upon exposure to heat. The materials used to manufacture shrink films include polyethylene, polypropylene, polyolefin, and PVC resins. The packaging solutions provide protective features and act as a branding surface for various kinds of products including primary, secondary, and collation packaging. With the increase in retail and e-commerce logistics channels around the world and rising need for effective packaging solutions, there is increasing demand for shrink films globally.
In 2026, Amcor plc expanded its shrink film production capacity in Asia to strengthen supply to regional food and beverage manufacturers, reinforcing its position across the fast-growing Asia-Pacific packaging market.
To Get more information On Shrink Films Market - Request Free Sample Report
Shrink Films Market Trends:
-
Rising e-commerce and logistics activity is driving demand for durable, tamper-evident shrink film packaging solutions.
-
Growing adoption of biodegradable and post-consumer recycled shrink films is supporting circular economy packaging initiatives.
-
Expanding automated high-speed packaging line adoption is accelerating demand for consistent, machine-compatible shrink film formulations.
-
Increasing regulatory pressure to reduce single-use plastic waste is reshaping shrink film material development toward sustainable alternatives.
-
Strategic capacity expansions by packaging film manufacturers are strengthening regional supply chain reliability for food and retail customers.
U.S. Shrink Films Market Outlook:
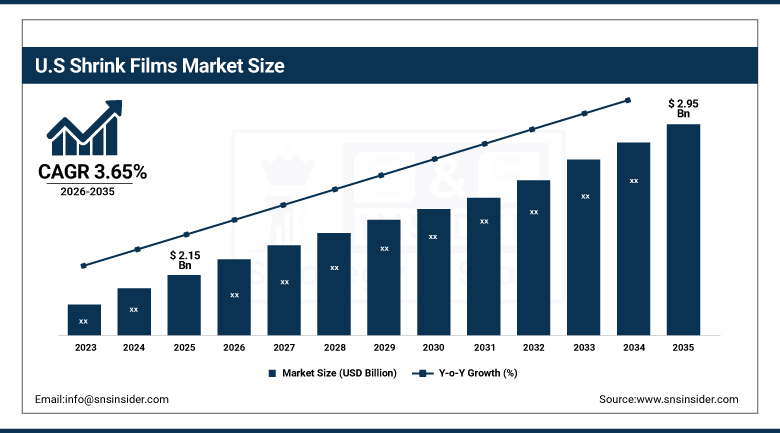
The U.S. Shrink Films Market was valued at USD 2.15 Billion in 2025 and is projected to reach USD 2.95 Billion by 2035, growing at a CAGR of 3.65% during 2026–2035.
The United States is still making up a large proportion of the worldwide market for shrink films due to the presence of many food and beverages factories in addition to the country's strong distribution network that consists of retail and online stores, alongside increasing attention towards sustainable packaging materials. Local producers keep adding to the domestic production of shrink films that have been recycled from post-consumer use and high clarity shrink films to cater to their food, consumer goods and industrial packaging clients, in addition to the automation of packaging lines in the country's distribution centers that increases the demand for machine friendly shrink films.
In 2025, Sealed Air Corporation introduced an upgraded high-clarity shrink film formulation designed for improved branding and shelf appeal in retail packaging applications across North America.
Shrink Films Market Segment Analysis:
-
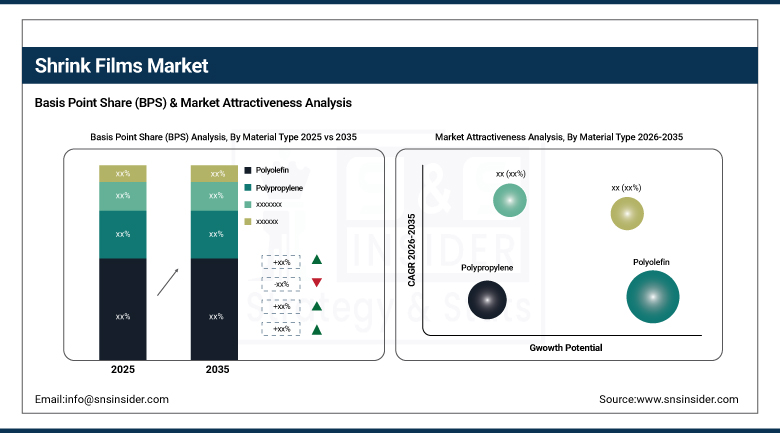
By Material Type, Polyolefin dominated the Shrink Films Market with a 42.80% share in 2025, while Polypropylene is the fastest-growing material type segment with a CAGR of 5.60% from 2026–2035.
-
By Product Type, Unprinted Films dominated the Shrink Films Market with a 63.40% share in 2025, while Printed Films is the fastest-growing product type segment with a CAGR of 5.90% from 2026–2035.
-
By Application, Product Protection dominated the Shrink Films Market with a 38.60% share in 2025, while Tamper Evidence is the fastest-growing application segment with a CAGR of 6.40% from 2026–2035.
-
By End-Use Industry, Food & Beverages dominated the Shrink Films Market with a 34.60% share in 2025, while Retail & E-commerce is the fastest-growing end-use industry segment with a CAGR of 6.80% from 2026–2035.
By Material Type, Polyolefin led while Polypropylene is the fastest-growing segment.
The Polyolefin segment was the leading contributor to revenue in the Shrink Films Market in 2025. The reason for this is the inherent clarity, puncture resistance, and wide temperature range exhibited by polyolefin films, when compared to PVC based films, along with an excellent recyclability factor that conforms to increasing environmental regulations. This combination has helped establish polyolefin as the material of choice in applications like food and beverages packaging, as well as consumer goods packaging.
The Polypropylene segment is expected to witness the highest CAGR of 5.60% during the forecast period 2026-2035. Increasing requirement for high performance shrink films made from polypropylene that offer chemical resistance and dimensional stability, in addition to manufacturers' interest in the recycling benefits of polypropylene over multi-layer films, is increasing the pace of adoption of this particular segment as compared to other types of shrink films.
By Product Type, Unprinted Films led while Printed Films is the fastest-growing segment.
The Unprinted Films segment dominated the Shrink Films Market in 2025. Unprinted films remain the dominant product type category owing to their cost-effectiveness and broad applicability across secondary and collation packaging applications where the primary function is product protection and load stabilization rather than retail shelf presentation, reinforcing unprinted films as the foundational product format driving the majority of global shrink film consumption across industrial and logistics applications.
The Printed Films segment is expected to register the fastest CAGR of 5.90% during the forecast period 2026-2035. There is increasing pressure on brand owners to ensure that their products have more shelf differentiation and customer engagement, and thus there is increasing use of printed shrink films, which have the branding of the product, nutrition facts, and compliance labels, directly printed on the package surface, in order to benefit from their marketing advantages.
By Application, Product Protection led while Tamper Evidence is the fastest-growing segment.
The Product Protection segment dominated the Shrink Films Market in 2025. Protection of the product is still the most dominant category of applications because the basic function of shrink films in protecting products against moisture, dust, and any kind of damage that may occur while storing and transporting them forms the core reason for the high demand for these films worldwide.
The Tamper Evidence segment is expected to witness the fastest CAGR of 6.40% during the forecast period 2026-2035. Rising regulatory and consumer emphasis on product safety and authenticity verification across food, pharmaceutical, and consumer goods categories is driving accelerated demand for tamper-evident shrink film seals, as brand owners increasingly prioritize packaging solutions that provide visible evidence of product integrity from manufacturing through point of sale.
By End-Use Industry, Food & Beverages led while Retail & E-commerce is the fastest-growing segment.
The Food & Beverages segment dominated the Shrink Films Market in 2025. Food and beverage applications remain the dominant end-use industry as shrink films are extensively used for multipack bundling, shelf-life extension, and moisture protection across packaged food and beverage products, reinforcing this industry as the foundational driver of the majority of global shrink film consumption across established and emerging consumer markets worldwide.
The Retail & E-commerce segment is expected to witness the fastest CAGR of 6.80% during the forecast period 2026-2035. The increased demand for packaging materials that can protect their products effectively during multi-stage shipment is being witnessed due to increased orders of e-commerce companies worldwide, which need to have secure and economically packaged orders that are capable of surviving through multi-stage shipment processes.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
71.80% |
|
Europe |
Germany |
25.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
24.80% |
|
Latin America |
Brazil |
33.60% |
North America Shrink Films Market Insights
The North America Shrink Films Market represented a significant portion of the global market in 2025, supported by extensive food and beverage manufacturing activity, well-established retail and e-commerce distribution infrastructure, and growing regulatory emphasis on sustainable packaging materials. The region's mature packaging film manufacturing base continues to support steady demand across established consumer and industrial applications.
The US was the leading country within the North America Shrink Films Market in 2025 with a market share of 71.80% of the regional market, driven by extensive food and beverage manufacturing and substantial e-commerce distribution activity. Canada is contributing to regional growth through its expanding retail packaging sector and growing sustainable packaging material adoption.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Shrink Films Market Insights
The Europe Shrink Films Market accounted for a substantial share of the global market in 2025, supported by stringent plastic waste reduction regulations under EU directives, a strong food and beverage manufacturing base and growing consumer preference for recyclable and sustainable packaging solutions across established European retail markets.
Germany was one of the major markets in Europe in 2025, supported by its significant production of food and beverages products and strong representation of leading film packers. Other nations like France and Italy, which already have consumer products and food processing industry, are also aiding regional demand due to their ongoing consumption of shrink films.
Asia Pacific Shrink Films Market Insights
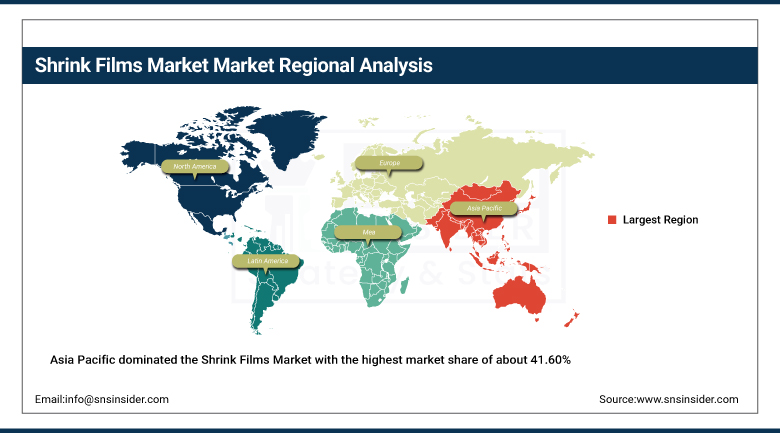
Asia Pacific dominated the Shrink Films Market with the highest market share of about 41.60% in 2025, and is also expected to register the fastest growth rate during the forecast period 2026-2035 at a CAGR of 5.80%. This dual leadership reflects the region's massive food and beverage manufacturing base, rapidly expanding e-commerce infrastructure, and dense concentration of packaging film production facilities across major and emerging manufacturing economies.
China was the leading country within the Asia Pacific Shrink Films Market in 2025, Supported by its wide array of food and beverages manufacturing sector and packaging films production facilities. India and Southeast Asian nations have been making their mark on the regional growth story by virtue of their developing e-commerce logistics system, increasing organized retail footprint, and increasing flexible packaging needs.
Middle East & Africa and Latin America Shrink Films Market Insights
Middle East & Africa and Latin American regions are gradually expanding shrink films adoption as food and beverage manufacturing and organized retail activity grows, supported by rising e-commerce distribution infrastructure investment and growing consumer packaged goods consumption across the regions' major economies.
Brazil is set to be a prominent Latin American market, accounting for 33.60% of the regional market in 2025, fueled by its substantial food and beverage manufacturing base and growing organized retail sector. The Middle East & Africa region has the UAE investing in retail and logistics distribution infrastructure, accounting for 24.80% of the regional market in 2025, as the country strengthens its position as a regional trade and distribution hub.
Market Dynamics:
Growth Drivers: Rising e-commerce activity and food packaging demand driving market growth
One of the key reasons behind the growth of the Shrink Films Market can be attributed to the constant growth in the activities associated with global E-Commerce and logistics, along with the increasing need for tamper-proof and moisture-proof food packaging. The benefits offered by shrink films in terms of protection, visibility of products, and surfaces for branding have always made them one of the preferred packaging solutions.
Rising food and beverage brand emphasis on shelf-life extension and hygiene compliance, combined with growing automated high-speed packaging line adoption requiring consistent, machine-compatible film formulations, continues to expand market opportunity across diverse end-use applications. Continued manufacturer investment in post-consumer recycled and biodegradable shrink film formulations addressing tightening plastic waste regulations is further supporting demand growth across the forecast period.
Restraints: Raw material price volatility and plastic waste regulation limiting market expansion
One of the most critical obstacles to market growth is the volatility in petrochemical feedstock pricing used in polyethylene, polypropylene, and polyolefin resin production, which directly impacts shrink film manufacturing economics and creates margin pressure for producers operating under long-term supply contracts with food and retail customers requiring stable, predictable pricing.
In addition, increased regulation of single-use plastic waste in key markets, especially those in Europe and specific states in America, would involve continued formulation of products and expenditure on regulation that increases development costs for companies, especially smaller regional companies that do not have much regulatory capability. Furthermore, increased competition from other forms of packaging such as paper and compostable packaging material also limits the addressable market size for shrink film.
Opportunities: Sustainable formulation innovation and e-commerce expansion creating new growth avenues
The increasing availability of post-consumer recycled and biodegradable formulations of shrink films, along with the increased e-commerce distribution networks in emerging countries, are providing many opportunities for the growth of the Shrink Films Market. There is an increasing preference by packaging converters and brand owners who wish to make their packaging sustainable and yet maintain the effectiveness of the packages.
There is significant growth opportunity in high-clarity and printed films as consumers look at engaging with brands and distinguishing from competitors on the shelves. As Asia-Pacific and Latin American markets witness expansion in organized retail and e-commerce fulfillment facilities, along with increased use of automation in packaging lines, demand for shrink films will remain on the rise.
Recent Developments:
-
2025: Berry Global Group launched a new post-consumer recycled polyolefin shrink film product line targeting sustainability-focused food and beverage customers.
-
2026: Buergofol GmbH launched a new co-extruded collation shrink film designed for heavy-duty industrial bundling and logistics applications.
Shrink Films Market key players are:
-
Amcor plc
-
Berry Global Group, Inc.
-
Sealed Air Corporation
-
Dow Inc.
-
Coveris Holdings S.A.
-
Intertape Polymer Group Inc.
-
Nova Chemicals Corporation
-
Mondi plc
-
Polypak Packaging
-
Schur Flexibles Holding GmbH
-
Buergofol GmbH
-
Scientex Berhad
-
Napco National
-
Sigma Plastics Group
-
Winpak Ltd.
-
Polyplex Corporation Limited
-
Uflex Ltd.
-
Jindal Poly Films Ltd.
-
Taghleef Industries
-
ProAmpac LLC
Shrink Films Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.85 Billion |
| Market Size by 2035 | USD 17.85 Billion |
| CAGR | CAGR of 4.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (Polyethylene, Polypropylene, Polyolefin, PVC & Others) • By Product Type (Printed Films, Unprinted Films) • By Application (Product Protection, Tamper Evidence, Moisture Resistance, Branding Enhancement & Others) • By End-Use Industry (Food & Beverages, Consumer Goods, Healthcare & Pharmaceuticals, Industrial Packaging, Retail & E-commerce & Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Berry Global Group, Inc., Sealed Air Corporation, Dow Inc., Coveris Holdings S.A., Intertape Polymer Group Inc., Nova Chemicals Corporation, Mondi plc, Polypak Packaging, Schur Flexibles Holding GmbH, Buergofol GmbH, Scientex Berhad, Napco National, Sigma Plastics Group, Winpak Ltd., Polyplex Corporation Limited, Uflex Ltd., Jindal Poly Films Ltd., Taghleef Industries, ProAmpac LLC. |
Frequently Asked Questions
Key players include Amcor plc, Berry Global Group, Sealed Air Corporation, Dow Inc., and Coveris Holdings S.A., among others worldwide.
Key opportunities include developing post-consumer recycled and biodegradable film formulations, and expanding high-clarity, printed film formats for retail branding and packaging.
Growth is driven by expanding e-commerce and logistics activity, rising demand for tamper-evident food packaging, and automated packaging line adoption.
The Product Protection segment dominated the Shrink Films Market, accounting for approximately 38.60% market share, due to its fundamental packaging role.
Asia Pacific dominated the Shrink Films Market in 2025 with a 41.60% share, driven by massive food and beverage manufacturing activity.
