
Silicone Surfactants Market Report Scope & Overview:
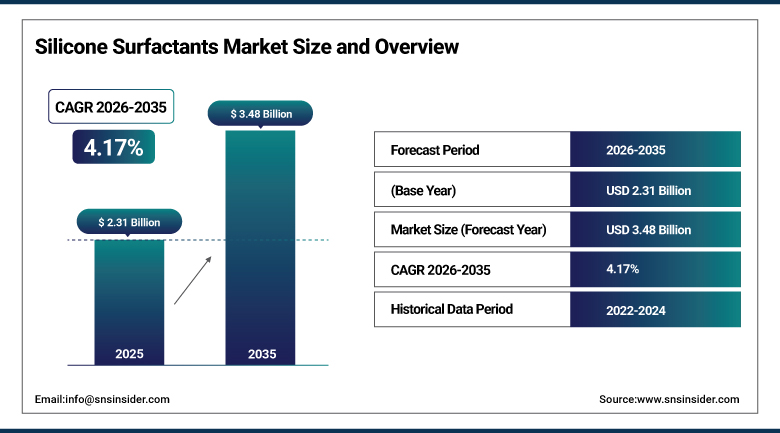
The Silicone Surfactants Market was valued at USD 2.31 Billion in 2025 and is expected to reach USD 3.48 Billion by 2035, growing at a CAGR of 4.17% from 2026-2035.
The Silicone Surfactants Market is experiencing steady growth on account of increasing demand in the personal care, cosmetic, construction, agriculture, and textile segments. Silicone surfactants possess the capacity to lower surface tension, spread, emulsify, and offer other characteristics such as stabilization and foam control. This makes these chemicals suitable for various purposes. The preference of consumers for good quality skin and hair care products and multi-functional cosmetic products has increased the use of silicone surfactants in personal care applications. In addition, the increasing use in polyurethane foams, paints, coatings, and construction chemicals has driven industrial applications.
To Get more information Silicone Surfactants Market - Request Free Sample Report
Silicone Surfactants Market Trends
-
Sulfate-free, waterless and sensorial personal care formats are lifting use of silicone emulsifiers.
-
Super spreader adjuvants are gaining ground in precision and drone-based crop spraying.
-
Restrictions on cyclic siloxanes are accelerating reformulation toward low-concern grades.
-
Capacity additions are moving toward Asia while ownership of silicone portfolios consolidates.
-
Bio-based, sugar-modified and low-VOC grades are widening product ranges as online ordering of specialty ingredients grows.
U.S. Silicone Surfactants Market Outlook
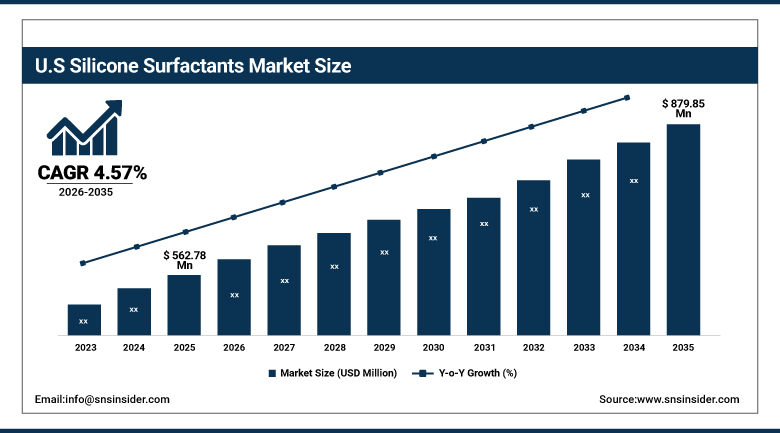
The U.S. Silicone Surfactants Market was valued at USD 562.78 Million in 2025 and is expected to reach USD 879.85 Million by 2035, growing at a CAGR of 4.57% from 2026-2035.
The U.S. Silicone Surfactants Market is experiencing stable growth, which is being fueled by rising demands from the personal care, cosmetics, construction, and agriculture sectors. The growing consumer demand for high-quality skincare and haircare, and multi-functional cosmetic products is fueling the application of silicone surfactants for superior spreading, emulsification, conditioning, and formulation stability purposes. Furthermore, the growing construction and infrastructure projects are boosting the demand for silicone additives in polyurethane foams, coatings, and construction chemicals. Increasing usage of advanced agricultural formulations, especially pesticide sprays and adjuvants, is further boosting the market growth. Moreover, consistent product innovation
⮞In April 2026, the American Coatings Association reported that U.S. paint and coatings product shipments reached USD 33.20 Billion in 2024 across a workforce of 312,000 people. This shipment base supports steady demand for silicone wetting and leveling additives.
Silicone Surfactants Market Segment Analysis
-
By Type, the Water-Soluble segment dominated the Silicone Surfactants Market with approximately 60.50% share in 2025, while the Oil-Soluble segment is the fastest growing with a CAGR of approximately 5.47%.
-
By Application, the Emulsifiers segment dominated the Silicone Surfactants Market with approximately 41.51% share in 2025, while the Foaming Agents segment is the fastest growing with a CAGR of approximately 5.17%.
-
By End Use, the Personal Care segment dominated the Silicone Surfactants Market with approximately 42.22% share in 2025, while the Paints and Coatings segment is the fastest growing with a CAGR of approximately 5.07%.
-
By Distribution Channel, the Offline segment dominated the Silicone Surfactants Market in 2025, while the Online segment is the fastest growing with a CAGR of approximately 5.87%.
By Type, Water-Soluble Dominates Silicone Surfactants Market; Oil-Soluble to Register Fastest Growth.
Water-soluble lead because most commercial formulations are aqueous. Polyether-modified siloxanes disperse in water, so shampoos, cleaners, waterborne coatings and crop spray tanks accept them without co-solvents. They lower surface tension sharply at small dosages, which trims cost per batch. Pressure on solvent emissions pushes formulators toward water-based systems, and suppliers offer wide molecular weight ranges that let buyers tune foam, wetting and spreading. Foam makers also depend on these copolymers for stable cell structure. Existing mixing equipment suits them.
Oil-soluble are advancing as cosmetic makers build water-in-oil systems for sunscreens, foundations and long-wear color products. These emulsifiers disperse pigments and mineral filters evenly and leave a silky finish that consumers prefer. Lubricant, electronics and specialty coating producers also use them to modify surface behavior in solvent-based media. Premium skin care launches in Asia and Europe lift volumes from a small base, and waterproof or transfer-resistant claims widen the customer set. Their compatibility with silicone fluids simplifies formulation.
By Application, Emulsifiers Dominate Silicone Surfactants Market; Foaming Agents to Register Fastest Growth.
Nearly every cream, lotion, sunscreen and makeup base needs a stable blend of oil and water, and that is where emulsifiers earn their lead. Silicone versions hold droplets together at very small use levels and tolerate wide temperature and electrolyte ranges, which protects shelf life. Agrochemical concentrates, polishes, textile softeners and coating emulsions add consumption. Cold-process and sugar-modified grades cut energy use in manufacturing, so multinational brands keep approving them in reformulation projects. Low dosage also lowers formulation cost.
Foaming agents gain pace through polyurethane foam, where silicone copolymers govern bubble nucleation and cell opening during rise. Insulation boards for buildings and cold chain equipment need fine and uniform cells to meet thermal targets, and efficiency codes are lifting insulation installation. Furniture and automotive seating makers add demand for molded and viscoelastic grades. In personal care, rinse-off products seek denser lather, and low-irritation foaming silicones support sulfate-free positioning. Appliance and refrigeration makers add further insulation foam volume.
⮞In July 2025, the Food and Agriculture Organization reported that global agricultural pesticide use reached 3.73 Million tonnes of active ingredients in 2023. Volumes of this size sustain demand for spray adjuvants and emulsifiers that improve coverage.
By End Use, Personal Care Dominates Silicone Surfactants Market; Paints and Coatings to Register Fastest Growth.
Hair, skin and sun products gain a smooth and non-tacky feel from silicone surfactants that organic alternatives struggle to match. Brands add them to conditioners, serums, antiperspirants and color cosmetics to stabilize emulsions and carry actives. Premiumization and rising grooming spend in emerging economies widen the buyer base, while sulfate-free and waterless formats favor mild silicone emulsifiers. Long qualification cycles with multinational customers keep volume locked in once a grade is approved. Regulatory acceptance across major markets eases launches.
Waterborne paints are prone to craters, poor substrate wetting and foam, so formulators are turning to silicone surfactants as they leave solvent-borne systems behind. Small additions lower surface tension and give smooth leveling on wood, metal and plastic. Industrial, automotive refinish and ink producers adopt them to meet tighter emission limits without losing film quality. Infrastructure spending and renovation activity in Asia Pacific add consumption, and low-VOC labeling encourages upgrades of additive packages. Printing inks and varnishes show similar needs.
⮞In January 2026, China's National Bureau of Statistics reported that cosmetics retail sales rose 5.10% in 2025. Sustained consumer spending of this kind underpins formulation volumes for silicone emulsifiers and conditioning agents.
By Distribution Channel, Offline Dominates Silicone Surfactants Market; Online to Register Fastest Growth.
Industrial buyers procure through direct supply contracts, technical sales teams and chemical distributors that provide samples, regulatory documents and formulation support. Selection usually follows trials in the customer's own process, so relationships last for years. Bulk deliveries in drums, intermediate containers and tankers need controlled logistics and credit terms that traditional distribution handles well. Large personal care, foam and coatings manufacturers prefer negotiated annual agreements that secure supply and consistent grade quality. Technical support during scale-up is valued highly.
Small cosmetic brands, laboratories and independent formulators now buy samples and small packs through digital marketplaces and supplier web shops. Transparent pricing, searchable datasheets and quick delivery shorten the trial phase for startups. Suppliers are adding digital catalogs and ordering portals to serve mid-sized customers, and distributors report stronger repeat purchases through e-commerce. Direct-to-consumer beauty brands often launch with limited batch sizes, which enlarges the pool of buyers comfortable with remote purchasing. Quick courier delivery simplifies small purchases.
⮞In August 2026, the U.S. Census Bureau reported that quarterly e-commerce sales reached USD 340.20 Billion in the second quarter of 2026, equal to 17.10% of total retail sales. Growing comfort with digital buying is extending to specialty chemical sampling and small-lot orders.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
47.60 |
|
North America |
United States |
84.30 |
|
Europe |
Germany |
25.40 |
|
Latin America |
Brazil |
54.80 |
|
Middle East and Africa |
Saudi Arabia |
33.70 |
Asia Pacific Silicone Surfactants Market Insights
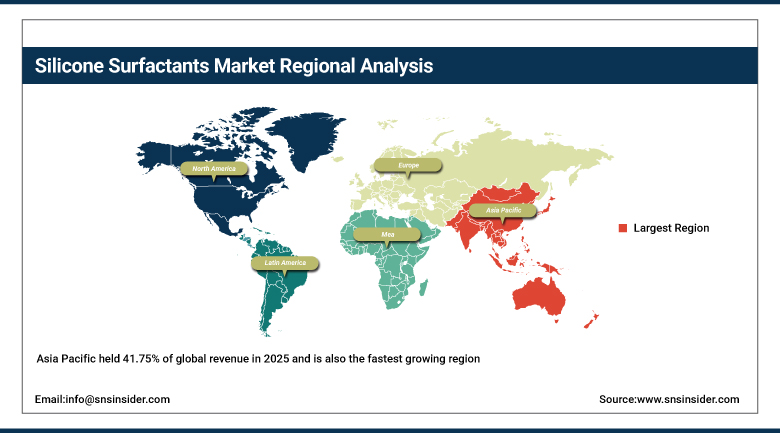
Asia Pacific held 41.75% of global revenue in 2025 and is also the fastest growing region, expanding at a CAGR of 4.59% through 2035. China supplies the largest volume through its siloxane chains and its cosmetics, textile and coatings industries. Dense manufacturing clusters give formulators short supply lines, and local producers compete hard on price. Japan contributes high-specification grades for electronics and premium cosmetics, while Southeast Asian countries add new capacity for personal care and foam. Government programs that promote local chemical self-sufficiency also reinforce regional output. Established multinational plants in the region export finished grades worldwide.
India and South Korea add growth through different routes. India benefits from rising agrochemical use, textile processing and a fast-growing cosmetics sector, and suppliers are building local emulsion capacity there. South Korea pairs a globally active beauty industry with demand for refined silicone ingredients in skincare and makeup. Rising urban incomes and larger infrastructure programs support additions in coatings and insulation, so the region keeps the broadest customer base across all end uses. Australia and Indonesia add agricultural and mining-related volumes through spray adjuvants and dispersants. Distributors in the region provide formulation guidance to small producers.
⮞In January 2026, South Korea's Ministry of Food and Drug Safety reported that cosmetics exports reached a record USD 11.43 Billion in 2025. This export strength shows the depth of regional demand for advanced silicone emulsifiers and conditioning ingredients.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Silicone Surfactants Market Insights
North America represents 28.90% of the market and relies on mature personal care, construction and agricultural industries. The United States and Canada host large brand owners that specify high-purity and low-odor silicone grades. Insulation foam demand follows building efficiency programs and refrigeration upgrades. Agricultural adjuvants support high-acreage crop production, and coating makers adopt low-VOC additives to meet environmental rules. Local manufacturing of siloxane intermediates and strong distributor networks supply mid-sized formulators reliably. Companies in the region also invest in application laboratories that help customers validate new grades quickly. Personal care launches remain a steady source of demand.
Innovation shapes regional demand. Suppliers work with cosmetic and agrochemical customers on cold-process, biodegradable and fluorine-free grades, and laboratories test new silicone polyether architectures for foam and coatings. Regulatory scrutiny of persistent substances encourages careful ingredient disclosure, which favors established suppliers with strong compliance teams. Growth is steady rather than rapid because construction spending is mixed, yet premium personal care and crop protection programs continue to absorb specialty volumes. Cooperation between suppliers and universities supports early stage research into greener chemistries. Brands in the region also promote ingredient transparency to retail partners and consumers.
⮞In 2025, Health Canada's Pest Management Regulatory Agency approved a record 386 pest control products. A larger pipeline of registered formulations increases the need for compatible adjuvants and wetting agents.
Europe Silicone Surfactants Market Insights
Europe accounts for 20.15% of the market and is shaped by strict chemical regulation and a mature cosmetics industry. Germany anchors demand through its chemical, coatings and automotive clusters, while France and Italy support cosmetics and fragrance production. Buyers place a premium on documented environmental performance, so suppliers highlight biodegradability, low residual monomer content and reduced hazard classifications. Renovation programs aimed at better building energy performance sustain demand for polyurethane insulation foam. Furniture and mattress producers in Poland and Spain add foam stabilizer demand. Regional coating makers also lead the shift to waterborne decorative paints.
Regional producers are reformulating around new restrictions on cyclic siloxanes and are investing in sugar-based and other bio-derived alternatives. Premium cosmetics houses in France and Switzerland test sensorial silicones for hair and skin products, and textile finishers in Italy use softening and wetting additives. Energy costs weigh on chemical output, yet specialized grades with high added value remain competitive. Export orders to Asia Pacific and the Middle East give regional makers additional volume. Regulators and retailers push ingredient transparency across supply chains, which raises the value of well-documented grades. Consumer awareness of sustainability further shapes sourcing.
⮞In February 2026, Eurostat reported that EU production in construction rose 0.50% in 2025. Modest building activity supports consistent use of silicone additives in coatings and insulation foam.
Latin America and Middle East and Africa Silicone Surfactants Market Insights
Latin America holds 5.90% of the market, with Brazil leading through large agricultural output and a sizable beauty industry. Mexico adds demand from personal care, automotive foam and coatings, supported by manufacturing links to North America. Argentina and Colombia contribute agrochemical and cosmetics volumes. Spray adjuvant use grows alongside planted area and aerial application. Imports from Asia and North America supply most grades, so currency movements and port logistics influence pricing and stock levels. Local formulators are also expanding hair care ranges that use silicone conditioning and emulsifying ingredients. Sugarcane and soybean growers are major adopters of adjuvants.
⮞In September 2026, Brazil's national supply company Conab estimated the 2025/26 grain and fiber crop at a record 361.70 Million tonnes. Larger harvests expand the volume of crop protection products and adjuvants applied each season.
The Middle East and Africa holds 3.30% of the market and is growing from a small base. Gulf economies are building local chemical and consumer goods production under industrial diversification programs, which creates demand for surfactants in cleaning, personal care and coatings. Housing and commercial construction drive foam and paint consumption. In Africa, South Africa and Egypt lead use in agriculture and textiles. Supply depends largely on imports, so regional distributors provide sampling and technical support. Rising urban populations and retail expansion support personal care consumption across the region. Local manufacturing incentives may raise regional sourcing over time.
⮞In March 2026, Saudi Arabia's Ministry of Industry and Mineral Resources reported that 1,201 new factories began production in 2025. Industrial expansion at this pace lifts local demand for process aids, coatings and personal care ingredients.
Market Dynamics
Growth Drivers: Rising personal care formulation activity and record crop output are increasing consumption of silicone surfactants.
Incremental personal care volumes remain the most potent force driving sales. The consumer base in developing markets is upgrading its usage to premium hair and skin products, which benefit from silicone emulsifiers for their pleasant texture and stability. Brands introducing sulfate free, waterless and sun care lines require mild but efficient emulsifying systems, and the reformulation process guarantees continuous conversations between suppliers and customers. Polyurethane foam as a raw material for construction insulation and cold storage represents the second robust source of demand. New developments in sun care, hair color and antiperspirants expand the range of available grades.
There is support from the agricultural market through trisiloxane adjuvants, which enhance spreading and coverage of herbicides, fungicides and nutrients with reduced application volume. Efficiency is valued by farmers who try to minimize waste, while drones become a new way to spray and increase demand for low volume formulations. Sustainable and sugar modified grades broaden the customer base due to growing environmental requirements. There is additional demand from the processing industry in emerging markets for wetting and softening effects of silicones. There is an increased area of high-value cultivation such as fruit and vegetable, which drives adjuvants per hectare use.
⮞In May 2026, India's Ministry of Agriculture and Farmers Welfare estimated foodgrain production at a record 376.56 Million tonnes for 2025-26. Output of this scale keeps crop protection programs active and supports adjuvant consumption.
Restraints: Volatile siloxane raw material prices and tighter limits on cyclic siloxanes are raising costs and complicating product planning.
Silicone surfactants rely on siloxane monomers and polyether intermediates, the prices of which vary according to energy prices and silicon metal supply and demand for other silicone applications. Extreme volatility either reduces supplier margins or imposes surcharges, both of which are resisted by buyers. The supply of critical trisiloxane intermediates is provided by a relatively narrow set of manufacturers, thus increasing the risk of plant disruptions and trade disruptions. Alkyl polyglucosides and sorbitan esters provide cost advantages, and cost-conscious buyers in coatings and cleaners switch when performance differences are marginal. Fluctuations in freight and energy costs further complicate yearly pricing negotiations. Inventories create additional working capital and warehousing costs.
The changing regulatory environment represents another burden. Increased transparency requirements for persistent organosilicon compounds and long approval processes for new chemistries represent additional compliance costs and delays. Environmental concerns over persistence cause some brands to avoid silicones in their clean label product lines, while irritation concerns affect certain applications. Small suppliers find testing and registration too expensive, limiting their ability to compete with large integrated suppliers with respect to grades offered. Reformulation costs are borne by buyers. Product stewardship programs and multiple regional registries impose additional paperwork for exporters.
⮞In May 2024, the European Commission adopted Regulation (EU) 2024/1328, under which D4, D5 and D6 may not be placed on the market at or above 0.10% by weight from 6 June 2026. The limit obliges suppliers to document low residual cyclic content in their grades.
Opportunities: Biodegradable grades and regionally supplied specialty chemistries are opening new routes to growth for suppliers.
Bio-based and sugar-modified silicone surfactants allow suppliers to meet sustainability goals set by brand owners and regulators. Buyers in personal care and home care are searching for biodegradable options that retain the sensory benefits of silicones, and early suppliers can command premium prices. Low-VOC formulations for coatings and eco-labeled products add further openings. Green silicone surfactants in Japan and South Korea and precision farming in North America are specific areas where tailored products can win share. Certification schemes for natural and eco-friendly formulations support premium positioning. Co-development agreements with brand owners secure early volume.
New end uses broaden the opportunity set. Electronics cooling fluids, photovoltaic sealants and advanced coatings need additives that control wetting and dispersion at fine tolerances. Customized grades for smart textiles and insulation foams give technical suppliers a path to higher margins. Regional production close to growing customers also reduces lead times and currency exposure, and producers that pair local technical service with certified low-concern chemistries are positioned to take share from commodity alternatives. Pilot projects in battery thermal management and solar module sealing create early demand. Suppliers with strong application laboratories can convert these pilots quickly.
⮞Cefic reported in December 2025 that Europe's share of global chemical industry sales fell to 13.00% in 2024 while China held 46.00%. The shift strengthens the case for regional supply of specialty additives and for suppliers that compete on innovation.
Recent Developments:
-
May 2025, Shin-Etsu Chemical launched KF-6080W, a liquid silicone emulsifier for cold-process oil-in-water formulations, together with KF-6070W silicone wax at CITE Japan 2025. The products let cosmetic makers produce stable emulsions without heating, which lowers energy use.
-
March 2026, Wacker Chemie opened a 15,000 square meter production complex for GMP-certified silicone emulsions for cosmetics at Panagarh in India as its second expansion phase. The site brings emulsion supply closer to fast-growing Asian personal care customers.
-
June 2026, Evonik Industries stated that over 95.00% of its siloxane-based coating and ink additive portfolio meets low substances-of-very-high-concern thresholds and suits Ecolabel decorative paints. The statement helps coating formulators meet environmental procurement requirements.
-
June 2026, Dow announced about USD 100.00 Million of spending through 2027 to expand liquid silicone rubber, electronics materials and cooling laboratory capacity across sites in Kentucky, Michigan, Zhangjiagang and Fukui. The plan strengthens supply of silicone materials for coatings and electronics.
Silicone Surfactants Market Key Players
-
Dow
-
Evonik Industries
-
Momentive Performance Materials
-
Wacker Chemie
-
Shin-Etsu Chemical
-
Innospec
-
BYK (ALTANA)
-
Siltech Corporation
Silicone Surfactants Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.31 Billion |
| Market Size by 2035 | USD 3.48 Billion |
| CAGR | CAGR of 4.17% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Water-Soluble and Oil-Soluble) • By Application (Emulsifiers, Foaming Agents, Wetting Agents, Dispersants, and Others) • By End Use (Personal Care, Agriculture, Paints and Coatings, Textiles, Polyurethane Foam, and Others) • By Distribution Channel (Offline and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Dow, Evonik Industries, Momentive Performance Materials, Wacker Chemie, Shin-Etsu Chemical, Innospec, BYK (ALTANA), Siltech Corporation |

Frequently Asked Questions
The key players in the Silicone Surfactants Market include Momentive Performance Materials, Innospec, BYK (ALTANA), Siltech Corporation and Evonik Industries, among others.
Biodegradable and sugar-modified grades, low-VOC coating additives and customized grades for electronics cooling, smart textiles and insulation foams offer the strongest opportunities. Regional production near growing customers adds further scope.
Rising demand for sensorial, sulfate-free and waterless personal care products is the major growth factor, supported by agrochemical adjuvant use and polyurethane foam insulation demand.
The Water-Soluble segment dominated the Silicone Surfactants Market in 2025 with approximately 60.50% share, supported by the aqueous nature of most personal care, agrochemical and coating formulations.
Asia Pacific dominated the Silicone Surfactants Market in 2025 with approximately 41.75% share, supported by large cosmetics, textile and coatings industries and expanding local production capacity.
