
Advanced Metering Infrastructure Market Report Scope & Overview:
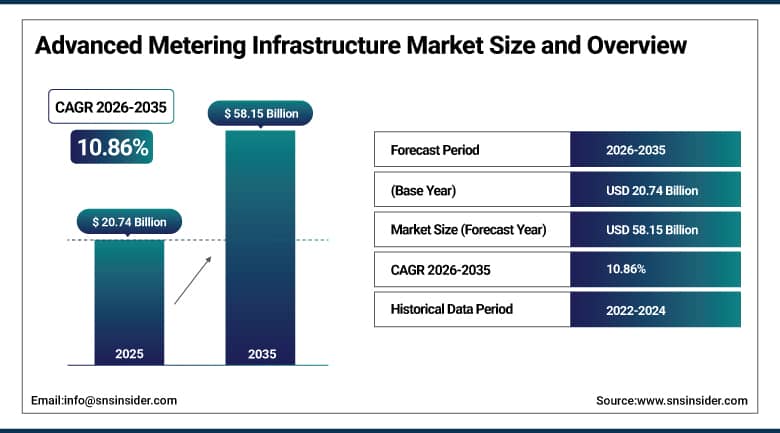
The Advanced Metering Infrastructure Market was valued at USD 20.74 Billion in 2025 and is expected to reach USD 58.15 Billion by 2035, growing at a CAGR of 10.86% from 2026-2035.
The Advanced Metering Infrastructure Market continues to expand as electric, water, and gas utilities replace legacy meters with connected systems that enable two-way communication, remote reading, and real-time grid visibility. Advanced metering infrastructure combines smart meters, communication networks, head-end systems, and meter data management software to deliver interval consumption data, outage detection, remote connection and disconnection, and time-of-use pricing. Utilities use these capabilities to significantly reduce operating costs, improve billing accuracy, detect theft and leaks, and engage customers in energy and water conservation. The rapid growth of rooftop solar, electric vehicles, heat pumps, and battery storage is increasing the need for grid edge intelligence that can monitor distributed energy resources and support demand flexibility.
To Get More Information On Advanced Metering Infrastructure Market - Request Free Sample Report
⮞Grid edge intelligence for Asia Pacific utilities advanced when Itron launched, in September 2026, its Riva S and Riva T IEC electricity meters, the first Gen6 network platform devices in the region, combining high-frequency sampling and edge computing to detect voltage issues, transformer loading, faults, and distributed energy resource impacts.
Advanced Metering Infrastructure Market Trends:
-
Rising deployment of second-generation smart meters with distributed intelligence.
-
Growing adoption of cellular IoT and eSIM connectivity for metering networks.
-
Expanding use of AMI data for distributed energy resource and EV charging management.
-
Increasing deployment of smart water meters for leak detection and conservation.
-
Rising adoption of prepaid smart metering in emerging markets.
-
Growing use of AI-driven analytics for outage detection and grid planning.
U.S. Advanced Metering Infrastructure Market Outlook:
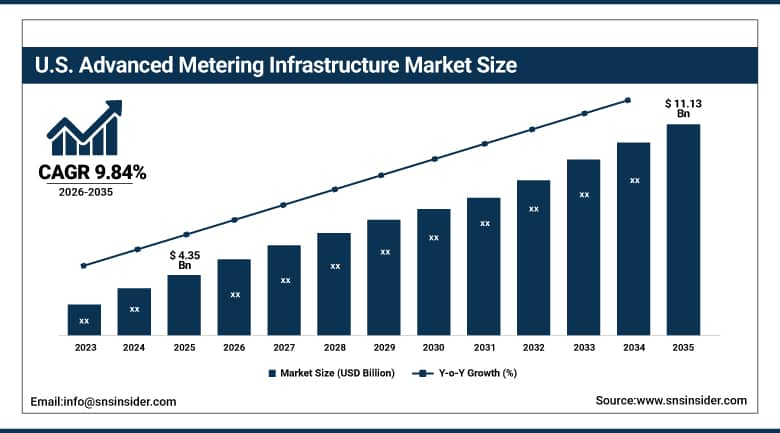
The U.S. Advanced Metering Infrastructure Market was valued at USD 4.35 Billion in 2025 and is expected to reach USD 11.13 Billion by 2035, growing at a CAGR of 9.84% from 2026-2035.
The U.S. Advanced Metering Infrastructure Market continues to grow on the strength of second-generation meter replacement programs, rising grid modernization investment, and the need to manage distributed energy resources. Many utilities that installed first-generation smart meters more than a decade ago are now upgrading to platforms with distributed intelligence, edge computing, and improved communication networks. Investor-owned utilities in California, Texas, Florida, Georgia, and the Northeast are deploying advanced meters to support time-of-use pricing, outage management, and electric vehicle integration. Municipal utilities and electric cooperatives are adopting AMI to reduce meter reading costs and improve reliability. Utilities are also using AMI data to support wildfire mitigation and storm response. Water utilities are expanding smart water metering to address leaks and drought. Federal grid resilience funding and state regulatory support for grid modernization encourage investment.
⮞Grid edge capabilities for U.S. utilities expanded when Landis+Gyr introduced, in September 2026, its Revelo E370 meter, extending its grid edge intelligence platform with greater deployment flexibility, real-time grid insight, and anomaly detection to improve utilities' operational visibility across their distribution networks.
Advanced Metering Infrastructure Market Segment Analysis:
-
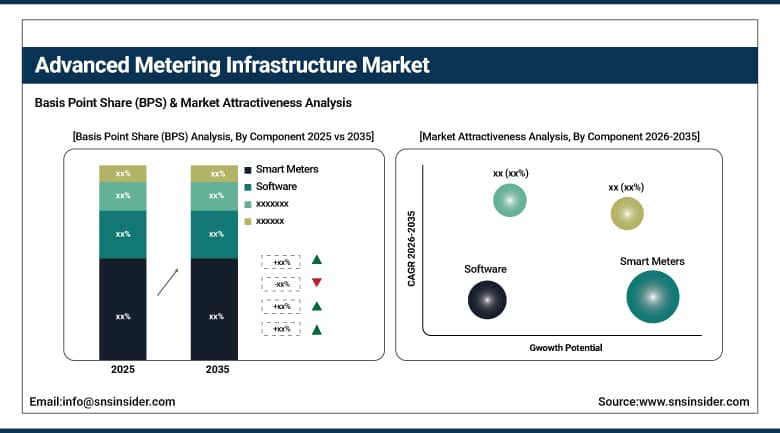
By Component, the Smart Meters segment dominated the Advanced Metering Infrastructure Market with approximately 46.28% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 13.64%.
-
By Communication Technology, the RF Mesh segment dominated the Advanced Metering Infrastructure Market with approximately 41.36% share in 2025, while the Cellular segment is the fastest growing with a CAGR of approximately 14.28%.
-
By Application, the Electricity segment dominated the Advanced Metering Infrastructure Market with approximately 66.84% share in 2025, while the Water segment is the fastest growing with a CAGR of approximately 13.82%.
-
By End-User, the Residential segment dominated the Advanced Metering Infrastructure Market with approximately 54.62% share in 2025, while the Commercial segment is the fastest growing with a CAGR of approximately 12.46%.
By Component, Smart Meters Dominate the Advanced Metering Infrastructure Market and Software Grows Fastest
Smart meters led the market in 2025, as they represent the largest share of capital spending in AMI deployments and are installed at every customer premise. Meter costs have fallen steadily. Modern smart meters measure interval consumption, voltage, and power quality, support remote connection and disconnection, and increasingly include edge computing capabilities. Large national rollouts in India, China, the United Kingdom, and other countries involve tens of millions of meters each. Replacement of first-generation smart meters in North America and Europe adds further demand. The volume and unit value of meter installations continue to secure smart meters as the largest component segment in the market.
⮞In April 2025, Landis+Gyr announced a five-year agreement to supply Enea Operator in Poland with 3 million smart electricity meters. The rollout is intended to improve grid efficiency, provide more detailed energy-consumption data and support smarter electricity network management.
Software is the fastest-growing component as utilities invest in meter data management, analytics, head-end systems, and grid edge applications to extract greater value from metering data. Software also supports billing, customer engagement, and regulatory reporting needs. Meter data analytics help utilities detect outages, theft, transformer overloads, and voltage problems, while supporting rate design and load forecasting. Cloud-based and software-as-a-service offerings reduce implementation costs and accelerate deployment of new applications. AI-driven tools, such as Itron's IEE Cloud AI, are expanding use cases across operations and customer service. Growing data volumes and distributed energy resource integration continue to drive the fastest growth in the software segment.
By Communication Technology, RF Mesh Dominates the Advanced Metering Infrastructure Market and Cellular Grows Fastest
RF mesh networks led the market in 2025, as they are widely deployed by utilities in North America, Europe, and Asia to connect large numbers of meters over wide areas. Many networks also support distribution automation devices. In RF mesh networks, each meter can relay data for neighboring devices, creating resilient, self-healing communication paths that perform well in dense urban and suburban areas. Utilities value the reliability, low latency, and ability to support additional grid devices such as streetlights and sensors. Large installed bases and proven performance from Itron, Landis+Gyr, and other vendors continue to secure RF mesh as the largest communication technology segment.
Cellular communication is the fastest-growing technology as NB-IoT, LTE-M, and 5G networks provide low-cost, wide-area connectivity without the need for utility-owned network infrastructure. Hybrid networks combining RF mesh and cellular are also gaining ground. Cellular connectivity simplifies deployment for smaller utilities, rural areas, and water and gas meters with long battery life requirements. Partnerships such as Landis+Gyr's eSIM collaboration with Thales enable secure remote management of meter connectivity across North American fleets. Telecom operators are offering dedicated IoT plans for utilities. Expanding cellular IoT coverage and falling module costs continue to drive the fastest growth among communication technology segments in the advanced metering infrastructure market.
⮞In May 2025, Landis+Gyr introduced an LTE-based load-switching device for its EMEA flexibility portfolio. The device supports remote load control and demand-side flexibility, demonstrating how cellular connectivity can help utilities manage electricity demand and integrate more responsive grid services.
By Application, Electricity Dominates the Advanced Metering Infrastructure Market and Water Grows Fastest
Electricity metering led the market in 2025, as electric utilities have been the earliest and largest adopters of advanced metering infrastructure. Electric meters also provide the backbone for wider smart grid applications. Electric AMI supports remote meter reading, outage detection, time-of-use pricing, demand response, and integration of rooftop solar, electric vehicles, and battery storage. Government mandates and national programs, such as India's Revamped Distribution Sector Scheme and Europe's smart metering targets, drive large-scale deployments. Second-generation electric meter upgrades in North America add further demand. The scale of electric utility programs worldwide continues to secure electricity as the largest application segment in the market.
⮞In October 2025, Landis+Gyr announced a grid-modernisation agreement with Rappahannock Electric Cooperative in the United States. The project will deploy the Revelo grid-edge intelligence platform and advanced metering infrastructure to strengthen grid visibility and help the cooperative manage changing electricity demand.
Water metering is the fastest-growing application as water utilities adopt smart meters to reduce non-revenue water, detect leaks, and support conservation in drought-affected regions. Water meters also typically require long battery life of fifteen years or more. Smart water meters with ultrasonic or electromagnetic sensing provide accurate interval data and alerts for continuous flow, tampering, and backflow. Utilities in the United States, Europe, Australia, the Middle East, and Asia are expanding smart water programs. Xylem Sensus, Badger Meter, Kamstrup, Diehl Metering, and Neptune Technology Group lead the segment. Rising water scarcity and infrastructure funding continue to drive the fastest growth among application segments in the market.
By End-User, Residential Dominates the Advanced Metering Infrastructure Market and Commercial Grows Fastest
The residential segment led the market in 2025, as households account for the large majority of utility meters worldwide. Prepaid metering is also expanding rapidly in emerging markets. Residential smart meters enable remote reading, time-of-use and prepaid billing, outage notification, and detailed consumption feedback that helps customers manage energy and water use. Growing adoption of rooftop solar, home batteries, heat pumps, and electric vehicle chargers is increasing the importance of residential metering data for grid management. National rollout programs targeting all households in India, Europe, and other regions continue to secure residential as the largest end-user segment in the advanced metering infrastructure market.
The commercial segment is the fastest-growing end user as businesses, retail chains, office buildings, hospitals, and data centers adopt advanced meters to monitor energy consumption, power quality, and demand charges. Commercial meters often include advanced power quality monitoring functions. Commercial customers increasingly participate in demand response, on-site solar, battery storage, and electric vehicle fleet charging, requiring detailed interval data and remote control capabilities. Utilities are deploying advanced commercial and industrial meters with higher accuracy and power quality monitoring. Rising energy costs, sustainability reporting requirements, and growing electrification of commercial buildings continue to drive the fastest growth in the commercial segment.
⮞In May 2025, Dubai Electricity and Water Authority described how its Distribution Network Smart Centre uses advanced metering infrastructure and network data to monitor electricity distribution, identify faults and support faster operational responses. The system illustrates how commercial and public infrastructure operators can use connected metering data for real-time network management.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
83.48% |
|
Asia Pacific |
China |
44.62% |
|
Europe |
United Kingdom |
21.36% |
|
Latin America |
Brazil |
42.18% |
|
Middle East & Africa |
Saudi Arabia |
36.42% |
Asia Pacific Advanced Metering Infrastructure Market Insights
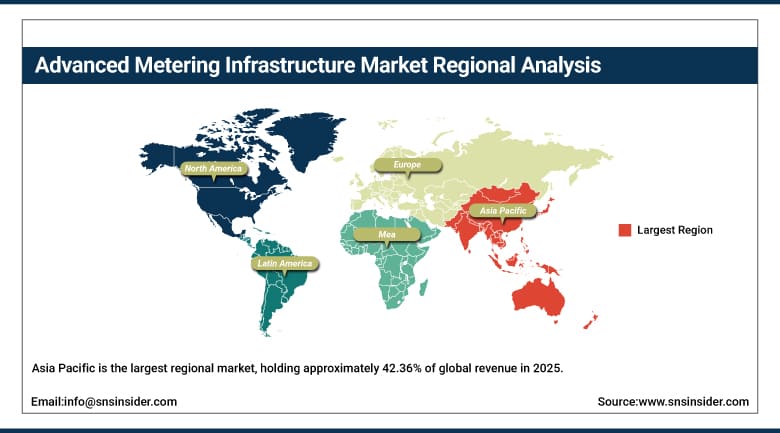
Asia Pacific is the largest regional market, holding approximately 42.36% of global revenue in 2025 and expanding at a CAGR of approximately 11.42% from 2026 to 2035. Smart meter tenders in the region are also increasingly structured as long-term service contracts that combine meter supply, installation, and data management. The region's leadership reflects China's massive smart meter installed base and ongoing replacement cycles managed by State Grid and China Southern Power Grid, along with India's national smart metering program. Chinese manufacturers including Wasion, Hexing, Holley, and Sanxing supply large volumes of meters for regional and export markets, while Japan and South Korea operate mature AMI networks.
⮞In January 2026, China’s State Grid announced plans to invest CNY 4 trillion in grid upgrades between 2026 and 2030. The investment programme targets expanded transmission and distribution infrastructure to accommodate renewable energy and growing electricity demand, creating a broader foundation for grid-edge monitoring and advanced metering applications.
India is a major growth contributor, as its Revamped Distribution Sector Scheme targets the installation of more than 200 million prepaid smart meters, with companies such as Adani Energy Solutions and Genus Power Infrastructures delivering large volumes. Prepaid metering is expanding rapidly across the region. Australia continues to expand smart metering under its accelerated rollout policy, supported by Itron's new Riva IEC meters. Southeast Asian countries, including Indonesia, Thailand, Malaysia, and Vietnam, are launching or expanding smart meter programs. Large-scale national deployments and rising electricity demand are expected to keep Asia Pacific the largest regional market over the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Advanced Metering Infrastructure Market Insights
North America accounted for approximately 25.14% of the global Advanced Metering Infrastructure Market in 2025, supported by high smart meter penetration, second-generation upgrade programs, and growing investment in grid modernization. Many utilities are now in the middle of large second-generation replacement programs that will continue through the end of the decade. Itron, Landis+Gyr, Xylem Sensus, Hubbell Aclara, Honeywell, and Badger Meter provide meters, networks, and software to investor-owned utilities, municipal utilities, and electric cooperatives across the region. Utilities are adopting distributed intelligence and edge computing to manage rooftop solar, electric vehicles, and battery storage, while smart water metering is expanding in drought-affected areas.
The United States anchors regional demand through large utility programs in California, Texas, Florida, Georgia, and the Northeast, along with rural cooperative and municipal deployments such as Benton REA's adoption of Landis+Gyr grid edge technology. Electric cooperatives and municipal utilities are also increasingly adopting cellular-connected meters. Canada is expanding AMI through utilities in Ontario, British Columbia, and Quebec, with Festival Hydro deploying the Revelo platform. Mexico's CFE is evaluating smart metering to reduce losses and improve billing accuracy. Second-generation meter replacements, distributed energy resource growth, and federal grid funding are expected to support steady regional growth over the forecast period.
⮞In April 2025, the U.S. Department of Energy documented an advanced metering infrastructure implementation project for Wray Electric System. The project involves installing AMI smart meters to improve distribution-grid monitoring, strengthen resilience and reduce the effects of power outages.
Europe Advanced Metering Infrastructure Market Insights
Europe holds a significant share of the Advanced Metering Infrastructure Market, supported by EU energy market rules that encourage smart meter deployment and by national rollout programs across member states. Many European utilities are now replacing first-generation meters installed early in the previous decade. The United Kingdom is a leading country market, with more than half of homes using smart meters under its national program. Italy, Spain, France, and the Nordic countries have high penetration and are now deploying second-generation meters, while Germany is accelerating its smart meter gateway rollout. Landis+Gyr, Kamstrup, Iskraemeco, Sagemcom, and Diehl Metering are key suppliers across the region.
⮞In April 2025, Landis+Gyr and Centrica Smart Meter Assets signed a three-year agreement to supply smart electricity and gas meters in the UK. The partnership supports ongoing meter deployment for households and businesses, extending infrastructure investment across the country's energy market.
European utilities are using AMI data to support dynamic pricing, flexibility markets, heat pump and electric vehicle integration, and energy efficiency programs. European vendors are also exporting their AMI solutions to utilities in other regions. Smart water and heat metering are expanding, particularly in Denmark, the Netherlands, and Germany, where Kamstrup and Diehl Metering are active. The EU Energy Efficiency Directive and Electricity Market Design reforms require consumers to have access to dynamic tariffs and consumption data. Strong regulatory support, second-generation replacements, and growth in distributed energy resources are expected to keep Europe a significant regional market over the forecast period.
MEA & Latin America Advanced Metering Infrastructure Market Insights
The Middle East & Africa is the fastest-growing regional market, expanding at a CAGR of approximately 13.12% from 2026 to 2035, led by Saudi Arabia, the United Arab Emirates, Qatar, and South Africa. Prepaid smart metering is particularly important for utilities in Africa. Saudi Electricity Company has deployed millions of smart meters, while Dubai Electricity and Water Authority and other Gulf utilities operate advanced smart grid programs covering electricity and water. Utilities in Africa, including those in South Africa, Kenya, and Nigeria, are adopting prepaid smart meters to reduce losses, improve revenue collection, and expand electricity access to new customers.
⮞In December 2025, Saudi Arabia’s energy minister highlighted the country’s progress in smart-grid development, including more than 11 million smart meters installed since 2021. The programme supports remote consumption monitoring and more efficient electricity use, while digital grid technologies are helping improve network automation and reliability.
Latin America is developing steadily, supported by Brazil, Mexico, Chile, and Colombia. Regional utilities are also increasingly adopting cellular-connected meters. Brazilian distribution utilities are deploying smart meters to reduce non-technical losses and improve service quality under regulatory incentives. Chile and Colombia are advancing smart metering programs linked to energy market modernization, while Argentina and Peru are testing AMI in selected cities. High levels of electricity theft and commercial losses in parts of the region make AMI particularly valuable. Rising regulatory support, loss reduction programs, and infrastructure investment are expected to support steady growth across both regions over the forecast period.
⮞In January 2026, Brazil’s Ministry of Mines and Energy introduced measures to accelerate electricity-distribution digitalization, including minimum annual targets for additional smart-meter installations. Distributors must also assess costs and benefits to determine suitable investment levels, creating a regulatory pathway for gradual expansion of advanced metering infrastructure.
Market Dynamics:
Growth Drivers: Grid Modernization and Distributed Energy Resource Integration and Government Smart Metering Mandates
Grid modernization and distributed energy resource integration represent the primary drivers of Advanced Metering Infrastructure Market growth, as utilities need detailed visibility at the edge of the grid to manage rooftop solar, electric vehicles, heat pumps, and battery storage. Utilities are also using AMI data to improve wildfire mitigation. Advanced meters provide interval consumption and voltage data that help utilities detect overloaded transformers, voltage violations, and outages. Distributed intelligence platforms allow meters to run applications locally and respond quickly to changing conditions. Rising electrification and the growth of distributed generation continue to increase the strategic value of AMI for utility operations and planning.
Government smart metering mandates are further strengthening market growth, as national programs in India, China, Europe, the Middle East, and other regions require utilities to deploy advanced meters to all customers. National programs also create local manufacturing and installation opportunities. India's Revamped Distribution Sector Scheme supports the installation of hundreds of millions of prepaid smart meters, while European regulations promote smart metering and access to dynamic tariffs. Funding programs in the United States support grid modernization and resilience. These mandates and incentives provide long-term deployment pipelines for meter manufacturers, network providers, and software vendors across many countries and regions worldwide.
⮞In February 2026, India’s Ministry of Power reported that 5.28 crore smart meters had been installed nationwide across various programmes by December 31, 2025. Under the Revamped Distribution Sector Scheme, smart-metering works had been sanctioned for consumers, distribution transformers and feeders, demonstrating the scale of government-backed investment in utility digitalisation.
Restraints: High Deployment Costs and Data Privacy and Cybersecurity Concerns
High deployment costs remain a key restraint on the Advanced Metering Infrastructure Market, as AMI programs require significant investment in meters, communication networks, software platforms, installation labor, and system integration. Supply chain constraints for chips and components have also affected deployments. Smaller utilities, cooperatives, and utilities in developing countries may struggle to finance large-scale deployments without government support or innovative business models. Regulatory approval of cost recovery can be lengthy, and benefits such as reduced losses or improved reliability may take years to fully materialize. Replacing first-generation meters before the end of their expected life also raises cost concerns for regulators.
Data privacy and cybersecurity concerns further restrain market growth, as smart meters collect detailed consumption data that can reveal information about household activities. Interoperability challenges between vendors can also slow deployments and increase costs. Consumer concerns about privacy, data ownership, and remote disconnection have led to opposition in some communities. Connected meters and communication networks also expand the attack surface for cyber threats targeting critical infrastructure. Utilities must invest in encryption, secure firmware, network monitoring, and compliance with evolving data protection regulations. These requirements add cost and complexity to AMI programs and can slow deployment in certain markets around the world.
Opportunities: Second-Generation Meter Upgrades and Smart Water and Gas Metering Expansion
Second-generation meter upgrades present significant opportunities for the Advanced Metering Infrastructure Market, as utilities in North America, Europe, Australia, and parts of Asia replace first-generation smart meters installed more than a decade ago. Upgrade programs often include new meter data management software and analytics. New meters offer distributed intelligence, edge computing, higher sampling rates, improved communication, and support for grid edge applications. Utilities can use upgraded platforms to manage distributed energy resources, detect safety hazards, and improve outage response. Vendors offering backward-compatible networks and application ecosystems are well positioned to capture large replacement programs across many regions over the forecast period.
Smart water and gas metering expansion presents a further opportunity, as water and gas utilities trail electric utilities in AMI adoption and face growing pressure to reduce losses and improve safety. Multi-utility platforms can also reduce costs for municipal utilities serving several services. Smart water meters help utilities detect leaks, reduce non-revenue water, and support conservation, while smart gas meters with ultrasonic sensing and remote shutoff improve safety and billing accuracy. Approvals such as Landis+Gyr's Surent G480 ultrasonic gas meter in New York State demonstrate growing regulatory acceptance. Vendors with multi-utility platforms can capture expanding demand across water and gas networks.
⮞In December 2025, Abu Dhabi’s Department of Energy and the Abu Dhabi Agriculture and Food Safety Authority launched an AI-powered smart-meter project in Al Wathba. The initiative connects smart meters to the AD.WE digital platform to monitor agricultural water consumption, improve resource allocation and support more efficient water management.
Recent Developments:
-
September 2026: Thales partnered with Landis+Gyr to provide eSIM connectivity for North American smart meter fleets, enabling secure remote management of meter connectivity, flexible carrier selection, and fewer field visits for utilities deploying cellular-connected meters.
-
February 2026: Adani Energy Solutions became the first Indian company to install 1 crore (10 million) smart meters across distribution companies, advancing India's Revamped Distribution Sector Scheme and its national prepaid smart metering program.
Advanced Metering Infrastructure Market Key Players:
-
Landis+Gyr Group AG
-
Itron, Inc.
-
Xylem Inc. (Sensus)
-
Honeywell International Inc. (Elster)
-
Siemens AG
-
Schneider Electric SE
-
Kamstrup A/S
-
Hubbell Incorporated (Aclara)
-
Iskraemeco d.d.
-
Networked Energy Services Corporation
-
Badger Meter, Inc.
-
Diehl Metering GmbH
-
Hexing Electrical Co., Ltd.
-
Wasion Holdings Limited
-
Genus Power Infrastructures Limited
-
Holley Technology Ltd.
-
Sagemcom SAS
-
Trilliant Holdings Inc.
-
Neptune Technology Group Inc.
-
Ningbo Sanxing Medical Electric Co., Ltd.
Advanced Metering Infrastructure Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 20.74 Billion |
| Market Size by 2035 | USD 58.15 Billion |
| CAGR | 7.36% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component: Dominant – Smart Meters (46.28% share in 2025); Fastest-Growing – Software (CAGR 13.64%) • By Communication Technology: Dominant – RF Mesh (41.36% share in 2025); Fastest-Growing – Cellular (CAGR 14.28%) • By Application: Dominant – Electricity (66.84% share in 2025); Fastest-Growing – Water (CAGR 13.82%) • By End-User: Dominant – Residential (54.62% share in 2025); Fastest-Growing – Commercial (CAGR 12.46%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Landis+Gyr Group AG, Itron, Inc., Xylem Inc. (Sensus), Honeywell International Inc. (Elster), Siemens AG, Schneider Electric SE, Kamstrup A/S, Hubbell Incorporated (Aclara), Iskraemeco d.d., Networked Energy Services Corporation, Badger Meter, Inc., Diehl Metering GmbH, Hexing Electrical Co., Ltd., Wasion Holdings Limited, Genus Power Infrastructures Limited, Holley Technology Ltd., Sagemcom SAS, Trilliant Holdings Inc., Neptune Technology Group Inc., Ningbo Sanxing Medical Electric Co., Ltd. |

Frequently Asked Questions
Key players include Landis+Gyr Group AG, Itron, Inc., Xylem Inc. (Sensus), Honeywell International Inc., Siemens AG, Schneider Electric SE, and Kamstrup A/S, among other global metering technology companies.
Second-generation meter upgrades, along with smart water and gas metering expansion, represent the primary opportunities.
Growth is primarily driven by grid modernization and distributed energy resource integration combined with government smart metering mandates.
By Application, Electricity dominated the market with approximately 66.84% share in 2025, reflecting large-scale smart meter deployments by electric utilities worldwide.
Asia Pacific dominated the market with approximately 42.36% share in 2025, driven by China's installed base and India's national smart metering program.
