
Cell Line Development Market Report Scope & Overview:
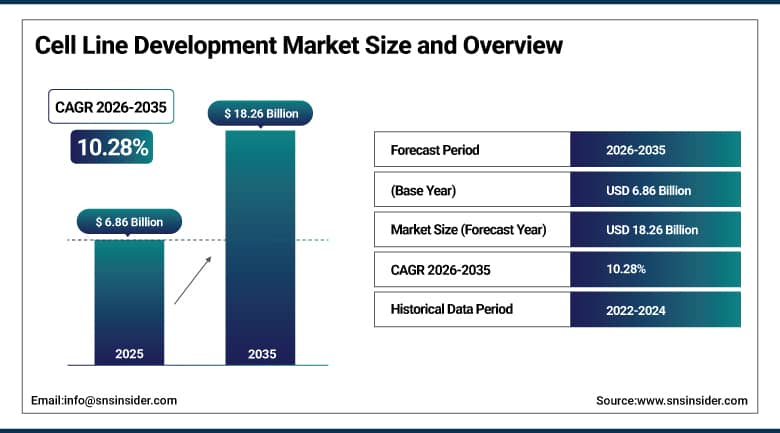
The Cell Line Development Market was valued at USD 6.86 Billion in 2025 and is expected to reach USD 18.26 Billion by 2035, growing at a CAGR of 10.28% from 2026-2035.
The Cell Line Development Market is experiencing growth because of an increase in the demand for biologics, biosimilars, vaccines, and other therapeutic products. Research activities in the fields of pharmaceuticals and biotechnology are generating the demand for better cell line development platforms that will help in drug discovery, manufacturing, and testing. Increased use of recombinant cell lines to manufacture monoclonal antibodies and therapeutic proteins is another factor driving the growth of this market. Technological advances in genetic engineering, automation, high-throughput screening, and cell culture techniques have made the process more efficient and reduced the time required for manufacturing. Increasing investment in the biopharmaceutical manufacturing sector and contract development and manufacturing organizations are providing new opportunities in the market.
⮞In late 2025, WuXi Biologics commenced operations at its new Singapore facility, representing a USD 1.4 billion investment spanning 13.5 hectares and adding 120,000 litres of bioreactor capacity to support biologics manufacturing at both clinical and commercial scale. The facility joins WuXi Biologics' existing global network and is expected to strengthen the company's cell line and process development capacity across the region.
To Get More Information On Cell Line Development Market - Request Free Sample Report
Cell Line Development Market Trends
-
Rising adoption of CRISPR-based genome editing improving precision and speed of cell line engineering.
-
Growing outsourcing of upstream process development to CDMOs amid capacity constraints at biopharmaceutical companies.
-
Expanding pipeline of cell and gene therapies driving demand for specialised human cell line platforms.
-
Increasing investment in high-throughput single-cell cloning technology improving clone selection efficiency.
-
Rising biomanufacturing capacity expansion across the United States and China supporting sustained demand.
U.S. Cell Line Development Market Overview
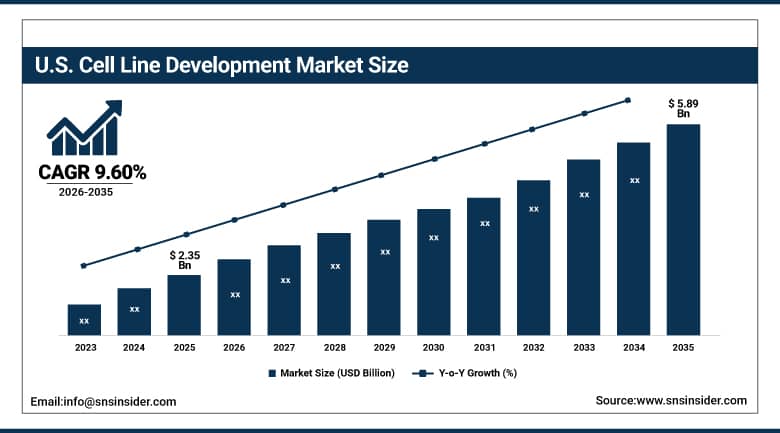
The U.S. Cell Line Development Market was valued at USD 2.35 Billion in 2025 and is expected to reach USD 5.89 Billion by 2035, growing at a CAGR of 9.60% from 2026-2035.
Domestic demand continues to be underpinned by advanced healthcare infrastructure, high cancer incidence rates, and strong adoption of innovative biologics across the country's substantial pharmaceutical and biotechnology sector. Leading contract development and manufacturing organisations continue expanding domestic bioreactor capacity to meet sustained demand from both established biopharmaceutical companies and an expanding base of smaller biotechnology developers seeking outsourced cell line engineering capability.
⮞In the fourth quarter of 2025, Thermo Fisher Scientific established a strategic collaboration with OpenAI to expand the use of artificial intelligence across its operations, products, and services, aiming to accelerate scientific breakthroughs and enhance drug development productivity. The company also expanded its bioprocess design centres across Asia, including a new site in India, to further support pharma and biotech customers with process development and scale-up.
Cell Line Development Market Segment Analysis
-
By Product & Services, Reagents and Media segment dominated the Cell Line Development Market in 2025 with 44% share; Services segment is the fastest-growing segment.
-
By Source, Mammalian Cell Line segment dominated the market in 2025 with 73% share; Mammalian Cell Line segment is also the fastest-growing segment.
-
By Type of Cell Line, Recombinant Cell Lines segment dominated the market in 2025 with 32% share; Hybridomas segment is the fastest-growing segment.
-
By Application, Bioproduction segment dominated the market in 2025 with 47% share; Tissue Engineering segment is the fastest-growing segment.
By Product & Services, Reagents and Media Dominate Cell Line Development Market; Services to Register Fastest Growth.
Reagents and Media dominate the Cell Line Development Market because they are fundamental inputs throughout cell culture, selection, screening, expansion, and characterization processes. Researchers and biopharmaceutical manufacturers require specialized media and reagents to maintain cell viability, support consistent growth, and achieve reproducible development outcomes. Their recurring consumption across research and production workflows generates sustained demand. Increasing pharmaceutical and biotechnology R&D, expanding biologics pipelines, and growing adoption of advanced cell-based research are further increasing requirements for high-quality reagents and media.
The services segment is likely to witness the highest growth due to the increasing trend of outsourcing specialized cell line development processes by pharma and biotech companies to shorten their development time and benefit from expertise and optimal costs. The specialized cell line development processes offered include customized development, screening, characterization, optimization, and validation processes that might need significant resources. The rise in biologics pipeline, complexities in cell engineering, and the need for reproducible development process have resulted in increased outsourcing trends.
⮞In March 2026, Lonza launched a Media Development Lab in Singapore to help bioprocessing customers optimize cell culture media formulations, improve process reliability, and facilitate scale-up into GMP manufacturing, strengthening support for specialized media development workflows.
By Source, Mammalian Cell Lines Dominate Cell Line Development Market; Mammalian Cell Lines to Register Fastest Growth.
Mammalian Cell Lines dominate the Cell Line Development Market because they provide biological characteristics and post-translational processing capabilities closely suited to the production of complex therapeutic proteins and other biologics. Chinese hamster ovary and other mammalian systems are widely used for producing monoclonal antibodies, recombinant proteins, and vaccines. Their established regulatory acceptance, scalability, and ability to produce biologically functional proteins support extensive adoption. The expanding biologics pipeline and increasing demand for complex therapeutic products continue to sustain strong utilization of mammalian cell lines.
Mammalian Cell Lines are also expected to register the fastest growth as pharmaceutical developers increasingly expand biologics pipelines involving monoclonal antibodies, recombinant proteins, fusion proteins, and other complex therapeutic products. Improvements in cell engineering, gene editing, productivity enhancement, and culture optimization are increasing the efficiency of mammalian expression systems. Growing demand for commercially scalable and regulatory-compatible production platforms is reinforcing their adoption. Increasing investment in biologics manufacturing capacity and development of next-generation therapies are expected to generate continued demand for advanced mammalian cell line development.
⮞In March 2026, Sartorius launched a genetically engineered Chinese hamster ovary (CHO) host cell line designed to improve therapeutic protein expression and productivity, addressing demand for higher-performing mammalian expression systems in biopharmaceutical development and manufacturing.
By Type of Cell Line, Recombinant Cell Lines Dominate Cell Line Development Market; Hybridomas to Register Fastest Growth.
The Recombinant Cell Lines hold the lead in the Cell Line Development market as they can help in the controlled production of specific proteins and other molecules having biological significance for research, diagnostic, and therapeutic purposes. They are specifically significant for the development of recombinant proteins, monoclonal antibodies, enzymes, and other biological products. Improvement in the field of genetic engineering and molecular biology has helped in developing stable cell lines producing specific molecules with similar properties. Growth in biologics research, protein therapeutics production, and requirements for expression systems has helped in maintaining high adoption rates.
Hybridomas will register the highest growth rate in the coming years owing to the increasing demand for monoclonal antibodies. Hybridoma technology is well established and is being used for the development of antibody-producing cell lines with stable and reproducible antibody production. Increase in the usage of monoclonal antibodies in disease diagnostics, biomarker research, immunoassay, and therapeutic research is helping in meeting the demand. Improvement in the screening process, characterization of antibodies, and cell culture techniques is helping in the efficient development of cell lines.
⮞In August 2026, Deepcell and Gilead Sciences announced a collaboration to develop an artificial intelligence foundation model for CHO cell morphology using Deepcell’s REM-I platform, aiming to identify high-quality antibody-producing cell lines more efficiently during biotherapeutic development.
By Application, Bioproduction Dominates Cell Line Development Market; Tissue Engineering to Register Fastest Growth.
Cell Line Development is dominated by Bioproduction as engineered cell lines play a crucial role in producing monoclonal antibodies, recombinant proteins, vaccines, enzymes, and other biological products commercially. Pharmaceutical and biotechnology companies need robust cell lines that can maintain product quality throughout the process of large-scale production. There is growing demand for cell line optimization because of increased pipeline of biologics and rising manufacturing capabilities. Targeted therapy, biosimilars, and recombinant biologics will further increase demand for cell line development and production platforms.
Tissue Engineering is likely to experience the highest CAGR during the forecast period owing to advancements in the field of regenerative medicine driving demand for standardized and reproducible cell lines for purposes of tissue development, disease modeling, and therapeutic applications. Cell lines can be used for studying cellular behavior, tissue formation, biomaterial interaction, and mechanism of tissue regeneration. Rising investments in research on regenerative medicine, stem cells, organoids, and advanced in vitro models are increasing the number of potential applications.
⮞In September 2025, the U.S. National Institutes of Health announced an $87 million, three-year commitment to establish the Standardized Organoid Modeling Center, developing reproducible organoid-based research methods that could strengthen advanced human tissue models and support applications in disease research and drug development.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|
North America |
United States |
82.45% |
|
Europe |
Germany |
24.80% |
|
Asia Pacific |
China |
36.90% |
|
Latin America |
Brazil |
27.10% |
|
Middle East & Africa |
United Arab Emirates |
22.40% |
North America Cell Line Development Market Insights
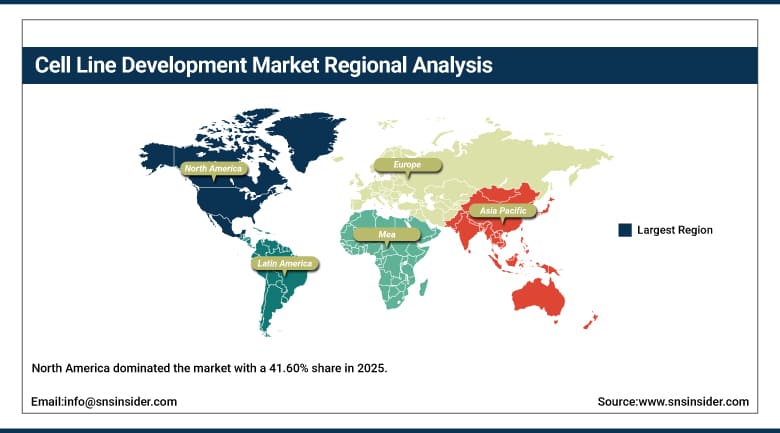
North America dominated the market with a 41.60% share in 2025. Advanced healthcare infrastructure, high cancer incidence rates, and strong adoption of innovative biologics across the region continue to anchor this leadership position. The United States in particular continues to host the highest concentration of leading biopharmaceutical companies, contract development organisations, and academic research institutions actively engaged in cell line engineering, reinforcing the region's position at the technological forefront of this industry throughout the current decade.
Canada contributes steady incremental demand as its own biotechnology sector continues expanding. Continued domestic investment in biomanufacturing capacity, exemplified by sustained facility expansion among leading contract development organisations, is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets building capability from a considerably smaller existing base.
⮞In February 2026, Johnson & Johnson announced an investment exceeding $1 billion in a next-generation cell therapy manufacturing facility in Montgomery County, Pennsylvania, intended to expand advanced medicine manufacturing capacity and strengthen its U.S. biomanufacturing infrastructure.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Cell Line Development Market Insights
Europe holds a meaningful share of the global market, supported by a well-established biopharmaceutical manufacturing base and continued government investment in biotechnology research infrastructure. Germany's substantial pharmaceutical manufacturing sector anchors regional demand, reinforced by a mature regulatory framework that continues to support advanced biologics development across the continent.
Switzerland, the United Kingdom, and other major European markets contribute consistent demand as established contract development organisations continue expanding capacity to serve both domestic and international biopharmaceutical customers. Europe is expected to register a relatively high growth rate through the forecast period, reflecting sustained investment across the region's broader biotechnology sector.
⮞In July 2026, Germany-based ProBioGen announced a collaboration with VarmX to develop a second therapeutic Factor X candidate using advanced cell line development capabilities, highlighting continued European demand for specialized expression systems supporting complex biologic drug development.
Asia Pacific Cell Line Development Market Insights
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 12.60% during 2026-2035. Rapidly expanding biomanufacturing capacity, growing government investment in biotechnology infrastructure, and an expanding domestic biologics pipeline continue to accelerate regional adoption. China's rapidly growing contract development and manufacturing sector continues to anchor regional demand, supported by substantial capital investment in new biomanufacturing facilities across the country.
South Korea's established biologics manufacturing base, anchored by leading contract development organisations pursuing large-scale international manufacturing contracts, continues to contribute meaningful regional depth. India's expanding biotechnology sector and Japan's established pharmaceutical industry contribute further regional scale, reinforcing Asia Pacific's position as the fastest-growing market for cell line development through the forecast period.
⮞In March 2026, China-based AsymBio announced that its Fengxian commercial manufacturing site in Shanghai had commenced operations, integrating biologics development and manufacturing capabilities across its Shanghai network to support programs from early development through commercial production.
MEA & Latin America Cell Line Development Market Insights
The Middle East & Africa market is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue channeling investment into biotechnology research capability and expanding domestic pharmaceutical manufacturing capacity.
Brazil drives the Latin American market with an increasing local demand for cell line development because of the emergence of its biopharmaceutical industry. Mexico adds to the growth of the market through the development of its healthcare infrastructure as well as biotechnology. The adoption of cutting-edge platforms is lower compared to more mature markets globally.
⮞In March 2026, Abu Dhabi’s Department of Health announced the launch and funding of the UAE’s first clinical trial of a gene therapy targeting MerTK-related retinitis pigmentosa, reinforcing the emirate’s efforts to expand advanced-therapy development and clinical capabilities.
⮞In November 2025, Brazil’s health regulator Anvisa authorized a Phase 1/2 clinical trial of a gene therapy developed by GEMMABio in partnership with Fiocruz for spinal muscular atrophy type 1, alongside a technology-transfer arrangement intended to support potential domestic production following regulatory approval.
Market Dynamics
Growth Drivers: Rising Biologics Pipeline Expansion and Cancer Prevalence
Rising demand for biologic drugs and biosimilars stands as the primary growth driver, as biopharmaceutical companies increasingly focus on recombinant proteins, monoclonal antibodies, and vaccines amid a broader global shift toward precision medicine and targeted therapies. The growing pipeline for biologics and biosimilars addressing chronic conditions continues to strengthen demand for advanced cell line development technologies capable of delivering the yield and consistency commercial manufacturing requires.
Increasing prevalence of cancer and an ageing global population represent a second major driver, as rising patient populations requiring monoclonal antibody and targeted biologic treatment continue to expand the addressable market for engineered cell lines. Growing vaccine production worldwide, reinforced by continued investment in genome editing and single-cell cloning technology, continues to sustain broad-based demand across established and emerging biopharmaceutical markets alike.
⮞In May 2026, Amgen announced an additional $300 million investment in its U.S. manufacturing network, bringing its announced manufacturing investments over the preceding year to nearly $2 billion and supporting expanded biologics production capacity, advanced manufacturing technologies, and supply-chain resilience.
Restraints: Complex Regulatory Landscape and Stem Cell Research Challenges
Stringent regulatory requirements certainly are a true limitation, as biopharmaceutical companies have to go through very strict and jurisdictional approval procedures when developing cell lines and expression systems, which may be very costly and time-consuming in terms of getting a new drug candidate to the market under several regulatory frameworks at once.
Limitations associated with stem cell research are another example of limitations faced by the industry, as certain applications of human cell lines continue to present high levels of scientific and ethical complexity in particular areas of therapy, thus holding back their commercial success.
Opportunities: Genome Editing Innovation and CDMO Capacity Expansion
Continued advancement of genome editing technology represents a substantial opportunity, as providers that can deliver genuinely faster, more precise cell line engineering capability stand to capture meaningful demand from biopharmaceutical companies seeking to accelerate development timelines for increasingly complex biologic candidates entering their pipelines.
Continued expansion of contract development and manufacturing capacity offers a further avenue for growth, as companies investing in new facilities across the United States and China are positioned to capture demand from biopharmaceutical companies increasingly seeking outsourced partners capable of taking programs from early cell line development through commercial-scale manufacturing.
⮞In January 2026, Aragen Life Sciences launched CHOMax™, an integrated platform combining cell line development, process development, analytics, and manufacturing support to help suitable monoclonal antibody programs progress from DNA to investigational new drug-enabling clinical supply in approximately 10 months.
Recent Developments:
-
2024, Lonza completed the first GMP product batch from its expanded manufacturing facility in Portsmouth, New Hampshire, adding a 2,000 litre single-use bioreactor supporting small- to mid-volume biologics production.
-
2025, Lotte Biologics reported that the first plant at its Songdo Bio Campus, representing a USD 1 billion investment, was slated to commence full-scale commercial production by 2027.
-
2025, Samsung Biologics signed a USD 1.24 billion contract, its largest ever with a single client, to produce biologics through December 2037, alongside a separate USD 688 million seven-year manufacturing agreement with an undisclosed European pharmaceutical company.
-
2026, Lonza expects to commission new cell and gene therapy, alongside microbial, manufacturing facilities in Visp, Switzerland, and Portsmouth, United Kingdom, expanding its specialised biomanufacturing capacity.
Cell Line Development Market Key Players
-
Thermo Fisher Scientific Inc.
-
Lonza Group AG
-
Sartorius AG
-
Danaher Corporation (Cytiva)
-
Merck KGaA
-
Corning Incorporated
-
WuXi Biologics (Cayman) Inc.
-
Charles River Laboratories International, Inc.
-
Samsung Biologics Co., Ltd.
-
FUJIFILM Diosynth Biotechnologies
-
Catalent, Inc.
-
Selexis SA
-
Promega Corporation
-
Bio-Techne Corporation
-
Agilent Technologies, Inc.
-
Revvity, Inc. (Horizon Discovery)
-
GenScript Biotech Corporation
-
Abcam plc
-
Creative Biolabs
-
ATUM
Cell Line Development Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.86 Billion |
| Market Size by 2035 | USD 18.26 Billion |
| CAGR | CAGR of 10.28% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product & Services (Reagents and Media, Equipment, Accessories and Consumables, Services) • By Source (Mammalian Cell Line, Non-mammalian Cell Line) • By Type of Cell Line (Recombinant Cell Lines, Hybridomas, Continuous Cell Lines, Primary Cell Lines) • By Application (Bioproduction, Drug Discovery, Toxicity Testing, Tissue Engineering, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Thermo Fisher Scientific Inc., Lonza Group AG, Sartorius AG, Danaher Corporation (Cytiva), Merck KGaA, Corning Incorporated, WuXi Biologics (Cayman) Inc., Charles River Laboratories International, Inc., Samsung Biologics Co., Ltd., FUJIFILM Diosynth Biotechnologies, Catalent, Inc., Selexis SA, Promega Corporation, Bio-Techne Corporation, Agilent Technologies, Inc., Revvity, Inc. (Horizon Discovery), GenScript Biotech Corporation, Abcam plc, Creative Biolabs, ATUM |

Frequently Asked Questions
Key players include Thermo Fisher Scientific Inc., Lonza Group AG, Sartorius AG, Danaher Corporation, Merck KGaA, and Samsung Biologics Co., Ltd., among other biopharmaceutical technology providers.
Continued advancement of genome editing technology and continued expansion of contract development and manufacturing capacity represent the primary opportunities for providers.
Growth is primarily driven by rising demand for biologic drugs and biosimilars, combined with increasing prevalence of cancer and an ageing global population.
By Product & Service Type, Reagents & Media dominated the market with in 2025.
North America dominated the market with a 41.60% share in 2025, supported by advanced healthcare infrastructure and strong adoption of innovative biologics.
