
eHealth Market Report Scope & Overview:
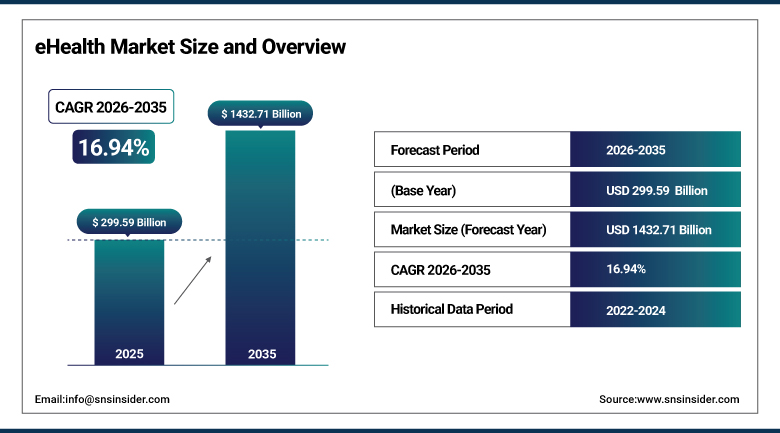
The eHealth Market was valued at USD 299.59 Billion in 2025 and is expected to reach USD 1,432.71 Billion by 2035, growing at a CAGR of 16.94% from 2026-2035.
The eHealth Market is expanding as health systems, insurers and consumers shift routine care, record keeping and communication to digital channels. Electronic health records remain the base of the industry, while telemedicine, mobile health applications and e-prescribing extend care beyond hospital walls. Governments are funding national health data platforms and setting interoperability rules that oblige vendors to open their systems. Artificial intelligence tools that draft clinical notes and automate scheduling are adding a new layer of spending. Chronic disease and workforce shortages further raise the need for remote monitoring. North America holds the largest share, while Asia Pacific is projected to grow fastest.
⮞In March 2026, Microsoft reported that more than 100,000 clinicians use Dragon Copilot every day for clinical documentation. The scale of use shows how ambient artificial intelligence is moving into routine clinical work.
To Get more information eHealth Market - Request Free Sample Report
eHealth Market Trends
-
Integration of generative AI assistants into electronic health record workflows to reduce documentation time
-
Expansion of hospital-at-home and remote monitoring programs supported by connected devices
-
Adoption of FHIR-based interfaces and national health data spaces that make records portable across providers
-
Growth of consumer-facing apps that combine appointments, prescriptions, records and payments
-
Migration of clinical systems from local servers to cloud and hybrid platforms
U.S. eHealth Market Outlook
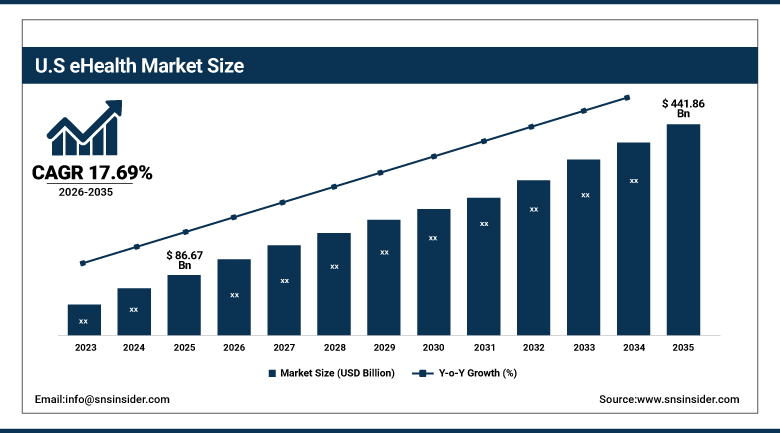
The U.S. eHealth Market was valued at USD 86.67 Billion in 2025 and is expected to reach USD 441.86 Billion by 2035, growing at a CAGR of 17.69% from 2026-2035.
The U.S. eHealth Market is the largest national market, supported by near-universal electronic health record use in hospitals, a large base of technology vendors and active federal policy on data exchange. Health systems are replacing older record systems with cloud platforms and adding AI tools for documentation and patient messaging. Telemedicine remains an established channel for primary care and behavioral health, while e-prescribing networks connect most pharmacies and prescribers. Medicare payment rules and interoperability requirements push providers to share records with patients and other organizations. Physician shortages and burnout further increase demand for tools that automate administrative work. Demand is strongest among large integrated delivery networks.
⮞In July 2025, the Centers for Medicare and Medicaid Services launched a health technology ecosystem built on an interoperability framework, with more than 60 companies pledging to meet its objectives in the first quarter of 2026. The initiative sets common expectations for how apps and records connect with patients and providers.
eHealth Market Segment Analysis
-
By Product, the Electronic Health Records segment dominated the eHealth Market with approximately 36.75% share in 2025, while the Telemedicine segment is the fastest growing with a CAGR of approximately 21.05%.
-
By Service Type, the Monitoring Services segment dominated the eHealth Market with approximately 59.04% share in 2025, while the Diagnostic Services segment is the fastest growing with a CAGR of approximately 19.44%.
-
By End User, the Healthcare Providers segment dominated the eHealth Market with approximately 54.03% share in 2025, while the Patients and Consumers segment is the fastest growing with a CAGR of approximately 20.48%.
-
By Deployment, the Cloud-Based segment dominated the eHealth Market with approximately 52.10% share in 2025, while the Hybrid segment is the fastest growing with a CAGR of approximately 23.36%.
By Product, Electronic Health Records Dominates the eHealth Market and Telemedicine Grows Fastest
Electronic health records remain the dominant product because every hospital, clinic and physician practice needs a system of record for clinical, billing and regulatory data. Large vendors sell integrated suites that cover documentation, orders, scheduling and patient portals, and switching costs keep customers for many years. Replacement cycles are now driven by demand for cloud delivery, embedded artificial intelligence and standards-based data exchange. Health systems also use the record as the platform on which other digital tools are connected, so spending on add-on modules tends to rise with each upgrade. Vendors also compete on certification status and the strength of their customer support networks.
Telemedicine is the fastest-growing product as virtual visits settle into routine care for primary care, behavioral health, chronic disease follow-up and specialty consultations. Providers use video and messaging to extend access in rural areas and to cut travel time for older patients. Employers and insurers sponsor virtual care benefits, and hospital-at-home programs depend on telehealth tools for daily check-ins. Platforms that join video, remote monitoring and record access in one workflow are gaining preference over stand-alone video applications. Reimbursement for virtual visits across public and private payers keeps this segment on a rapid growth path.
⮞In January 2026, MEDITECH announced that its Expanse electronic health record was live in 43 HCA Healthcare hospitals. The rollout shows continued large-scale demand for enterprise record platforms.
By Service Type, Monitoring Services Dominates the eHealth Market and Diagnostic Services Grows Fastest
Monitoring services lead because chronic disease management, post-discharge follow-up and elderly care all rely on continuous collection of vital signs and symptoms. Connected blood pressure cuffs, glucose meters, wearables and bedside sensors feed data to care teams who intervene early and avoid readmissions. Payers in several countries now reimburse remote monitoring, which gives providers a stable revenue basis for building programs. Demand is strongest in cardiology, diabetes and respiratory care, where trends in daily readings alter treatment decisions. Programs for heart failure and hypertension are expanding quickly, and these programs often include nurse-led outreach that raises patient engagement and adherence to treatment plans.
Diagnostic services are growing fastest as remote consultations expand to include digital imaging review, laboratory ordering, home test kits and AI-supported triage. Patients can complete a screening or send an image from home and receive a result without a clinic visit. Radiology and dermatology teams use cloud platforms to read cases from distant sites, and decision support tools flag abnormal results for clinicians. These capabilities widen access in regions with few specialists and reduce waiting times for routine tests. Reimbursement for remote reading of results is gradually becoming available in more countries, which supports the commercial case for building these services.
⮞In May 2026, Philips was selected, as part of a consortium, to deliver technology for hospital-at-home care in Region Stockholm for up to 15,000 patients a year. The contract shows how monitoring technology is being built into regional care models.
By End User, Healthcare Providers Dominates the eHealth Market and Patients and Consumers Grows Fastest
Healthcare providers account for the largest share because hospitals, clinics and physician groups buy the record systems, telemedicine platforms and clinical tools that make up most eHealth spending. Their purchases are guided by regulatory reporting duties, payment programs that reward digital capability and the need to coordinate patients across settings. Large hospital groups run enterprise agreements covering many sites, while independent practices choose cloud-based systems that need little local support, so the provider group spans very different buying patterns. Payers are an increasingly important buyer group as they invest in member apps and care navigation tools.
Patients and consumers are expected to grow fastest as people pay for virtual visits, health apps, wearable services and online pharmacies directly. Easy access to personal records through national portals and smartphone apps raises comfort with digital tools. Younger adults in particular expect booking, messaging and prescription renewal on their phones, and companies serving them compete on convenience and price. Subscription models for chronic condition coaching and mental health are widening the consumer market beyond episodic visits. Public health agencies also fund consumer apps for vaccination records and chronic disease management, which widens the base of users who engage with digital services every month.
⮞In July 2026, Canada Health Infoway reported that 49% of Canadians had accessed their health information electronically, up from 39% in 2023. The rise points to growing public readiness to use digital health services.
By Deployment, Cloud-Based Dominates the eHealth Market and Hybrid Grows Fastest
Cloud-based deployment leads because providers want faster implementation, automatic updates and the ability to scale during demand peaks without buying hardware. Vendors deliver electronic health records, telemedicine and analytics as subscription services, and large cloud providers have added healthcare-specific compliance programs that ease security concerns. Smaller practices in particular avoid server maintenance, and hospitals value the ease of adding AI features that run on shared infrastructure. Many vendors now price cloud tiers by usage, which lets providers match spending to patient volumes.
Hybrid deployment is growing fastest as large organizations move in stages and keep some workloads local. Imaging archives, medical device interfaces and data subject to residency rules often remain on premises, while patient-facing applications and analytics run in the cloud. Vendors that offer secure links between the two environments, along with tools to move data without disrupting care, are winning contracts from academic centers and national health agencies. This approach lets providers reduce risk while still gaining the benefits of modern platforms. Security certifications, encryption standards and clear data residency options remain central to winning large public sector contracts.
⮞In August 2025, Oracle introduced an AI-driven electronic health record for U.S. ambulatory providers, with acute care functionality planned for 2026. The launch reflects the shift of record platforms toward cloud-delivered artificial intelligence.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
70.00 |
|
Europe |
Germany |
24.37 |
|
Asia Pacific |
China |
38.64 |
|
Latin America |
Brazil |
49.26 |
|
Middle East & Africa |
Saudi Arabia |
31.82 |
North America eHealth Market Insights
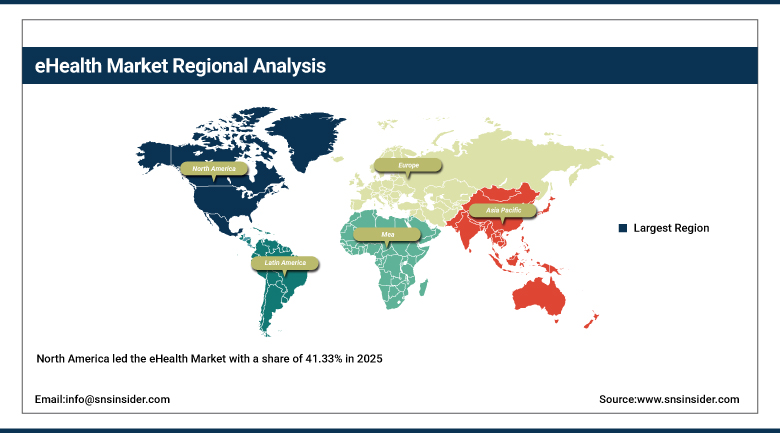
North America led the eHealth Market with a share of 41.33% in 2025, supported by high technology spending, near-universal electronic health record use and active policy on data exchange. U.S. hospitals and physician groups are replacing older systems with cloud platforms and adding AI documentation tools, while insurers fund virtual care and remote monitoring. Large technology companies, record vendors and specialist telehealth firms all compete for the same provider budgets. Venture funding and acquisitions continue to reshape the supplier base.
Canada adds demand through provincial digital health programs and growing patient use of online records. Provincial authorities are linking laboratory, imaging and pharmacy data to patient portals, and virtual care has become a regular part of access in remote and northern communities. Differences in funding and systems between provinces slow national consistency, yet cross-border vendors serve both countries with similar platforms adapted to local privacy rules and language needs. Remote and northern communities also gain access to specialist care through virtual visits funded by provincial plans.
⮞For instance, the National Center for Health Statistics reported in June 2026 that 80.0% of office-based U.S. physicians used telemedicine in 2024, down from 86.5% in 2021. The figure shows that virtual care has settled at a high level after the pandemic peak.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe eHealth Market Insights
Europe is a large, policy-led region in which Germany, the United Kingdom and France account for the main share of spending. National health services are building shared apps and records, and funding is directed toward tools that reduce waiting times and let patients manage appointments, prescriptions and results. The General Data Protection Regulation shapes product design, and vendors invest in local hosting, consent management and security certification. Regional differences in payment and reimbursement rules also shape which products reach scale in each country.
Germany now provides an electronic patient record to all people with statutory insurance, and the European Health Data Space is setting common rules for sharing records across borders. The Nordic countries have long used national portals, while southern European regions are adding digital front doors to reduce crowding in clinics. Procurement is often tender-based and slow, which favors established suppliers, although specialist firms succeed in specialized areas such as e-prescribing and remote monitoring. France and Italy are also extending national patient portals and secure messaging.
⮞In December 2025, NHS England reported more than 39 million registered users of the NHS App. The scale of the app makes it a central channel for digital access to care in England.
Asia Pacific eHealth Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 19.71% during 2026-2035, as governments build national digital health platforms and private operators invest in online care. Smartphone use is high, and super-app style services let patients book, pay and message providers in a single place. Large populations, a rising middle class and growing chronic disease burdens increase demand for remote consultation and monitoring. Medical tourism hubs such as Singapore and Thailand also invest in patient-facing digital services to attract international patients.
China has large internet hospital platforms and AI-assisted consultation services, Japan and South Korea are modernizing records for aging populations, and India is expanding digital health accounts under a national mission. Australia has a mature national record that supports patient access through apps. The region is diverse in language and regulation, so vendors work with local partners and adapt communication tools to each country. South Korea and Singapore are also advancing hospital data sharing, and Southeast Asian health ministries are funding telehealth links to rural clinics.
⮞In December 2025, the Australian Digital Health Agency reported more than 24.6 million active My Health Records. The volume of records forms a base on which patient-facing applications can be built.
MEA & Latin America eHealth Market Insights
In the Middle East and Africa, Gulf states provide most demand. Saudi Arabia and the United Arab Emirates invest in national health apps, virtual hospitals and health information exchanges under economic modernization plans, and international hospital brands set high service expectations. South Africa and Egypt are building private hospital networks that adopt digital records, though funding limits and uneven connectivity slow adoption in much of Africa. Qatar, Kuwait and Oman are also expanding digital health records as part of national visions for health reform.
⮞In September 2025, the Saudi Ministry of Health reported that its Seha Virtual Hospital, connected with more than 230 hospitals, won the 2025 Excellence Award in Virtual Healthcare Solutions. The recognition highlights the Gulf lead in large-scale virtual care.
In Latin America, Brazil is the largest market, with a public system that is building a national health data network and private hospital groups that adopt cloud records and telehealth. Mexico, Colombia, Chile and Argentina add demand through digital booking and private insurer programs. Currency swings and uneven connectivity restrain large projects, but mobile-first design suits a region where smartphones are the main route to the internet. Private insurers and hospital groups in the region also support apps that help members book care and rate providers.
⮞In July 2026, Brazil's Ministry of Health advanced a program to bring high-speed connectivity to 1,983 health units, with completion expected by June 2027. Better connectivity is a precondition for telehealth and electronic records in remote areas.
Market Dynamics
Growth Drivers: Government Incentives, Chronic Disease Burden and AI Assistants Drive Growth in the eHealth Market
Governments in North America, Europe and Asia are funding digital health through incentive programs, national record platforms and interoperability rules, which turns technology adoption into a policy objective rather than a discretionary purchase. Payment rules that reimburse virtual visits and remote monitoring give providers a clear route to recover the cost of new systems. Public sector programs also raise baseline demand for the supporting infrastructure, including secure networks, identity services and data standards used by every vendor. Vendors that map their roadmaps to these programs see steadier long-term demand from public sector customers.
Chronic disease and aging populations create a second driver, since patients with diabetes, heart disease and respiratory conditions benefit most from continuous monitoring and virtual follow-up. Generative AI copilots that draft notes and handle scheduling respond to workforce shortages and burnout, giving health systems a direct return on investment. Faster mobile networks and wider smartphone ownership extend these services to patients in rural and underserved areas. Public and private payers are also testing value-based contracts that reward digital follow-up, which strengthens the case for continued investment.
⮞In May 2026, India's Ayushman Bharat Digital Mission reported that it had crossed 90 crore (900 million) health accounts. The program shows how state-led platforms create the user base for digital health services.
Restraints: Data Security Risks, Interoperability Gaps and High Implementation Costs Restrain Growth in the eHealth Market
Data security and privacy concerns are the most cited barrier. Health records are valuable to criminals, and ransomware attacks on hospitals have disrupted care, so providers perform lengthy security reviews and some delay cloud migration. Compliance with privacy laws in each country adds legal cost for vendors operating across borders, and breaches can bring penalties and loss of patient trust that affect the adoption of connected services. Cloud providers and record vendors now publish detailed security documentation to speed buyer reviews, but the process remains slow in public sector tenders.
Interoperability gaps and implementation costs further limit growth. Providers often run several record systems with different formats, and connecting them to new applications requires interface work and testing. Training, workflow redesign and legacy system migration raise total project costs, which small practices and hospitals in lower-income countries find difficult to bear. Questions about liability for AI-generated advice also make some clinicians cautious about adopting new tools. Without sufficient funding for clinician training, even well-designed systems can fail to deliver the expected gains, which limits the pace of expansion in many markets.
⮞The European Health Data Space Regulation entered into force in March 2025, with key provisions applying from March 2029. The phased timetable sets compliance work for vendors and providers across several years.
Opportunities: AI Workflow Automation, Home-Based Care and Emerging Markets Create Opportunities in the eHealth Market
Providers are under pressure to cut administrative work, which creates a large opportunity for AI tools that automate documentation, coding, prior authorization and patient messaging. Vendors that integrate these functions into existing record workflows can charge for measurable time savings. Middleware that moves data between different systems and platforms that coordinate care at home also address real gaps left by earlier generations of products. Providers that adopt these tools early can free clinicians for patient care and may improve staff retention in a tight labor market.
Emerging markets offer additional growth as governments and development partners invest in digital health infrastructure. Direct-to-consumer telehealth models and mobile-first applications can reach populations with few physicians. Home-based acute care, supported by monitoring devices and virtual clinicians, is gaining attention from payers who want lower-cost alternatives to inpatient stays, and suppliers who offer end-to-end packages will benefit from this change. Telehealth firms that already hold patient relationships can also expand into diagnostics, prescribing and chronic condition management with limited additional spending.
⮞In October 2025, the World Health Organization and the European Union launched a EUR 8 million collaboration to advance digitized health systems in sub-Saharan Africa. Donor-backed programs of this kind build the foundation for later commercial adoption.
Recent Developments:
-
In March 2026, Universal Health Services agreed to acquire Talkspace, a virtual behavioral health provider, for USD 5.25 per share. The transaction gives a large hospital operator its own virtual mental health platform and links inpatient services with remote follow-up.
-
In November 2025, InterSystems introduced the HealthShare AI Assistant for its unified care record platform, which powers more than 1 billion health records. The assistant lets clinicians query patient histories drawn from many source systems in plain language.
-
In August 2026, athenahealth made AI-native capabilities in athenaOne available to its customer base of 170,000 clinicians. The update embeds ambient documentation and workflow automation directly into the ambulatory record used by independent practices.
-
In May 2026, Doctolib acquired Medicus, a United Kingdom supplier of electronic patient record software for general practices. The acquisition brings Doctolib's scheduling and patient-facing tools into British primary care and widens its European footprint.
eHealth Market Key Players
-
Epic Systems Corporation
-
Oracle Corporation (Oracle Health)
-
athenahealth, Inc.
-
MEDITECH (Medical Information Technology, Inc.)
-
eClinicalWorks, LLC
-
Veradigm Inc.
-
CareCloud, Inc.
-
Teladoc Health, Inc.
-
American Well Corporation (Amwell)
-
Doximity, Inc.
-
Hims & Hers Health, Inc.
-
Microsoft Corporation
-
Koninklijke Philips N.V.
-
InterSystems Corporation
-
Dedalus Group
-
CompuGroup Medical SE & Co. KGaA
-
Doctolib
-
Ping An Healthcare and Technology Company Limited
-
Surescripts, LLC
eHealth Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 299.59 Billion |
| Market Size by 2035 | USD 1,432.71 Billion |
| CAGR | CAGR of 16.94% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Electronic Health Records, Telemedicine, mHealth, E-Prescribing, Clinical Decision Support, and Other Products) • By Service Type (Monitoring Services, Diagnostic Services, and Other Services) • By End User (Healthcare Providers, Payers, Patients and Consumers, and Other End Users) • By Deployment (Cloud-Based, On-Premise, and Hybrid) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Epic Systems Corporation, Oracle Corporation (Oracle Health), athenahealth, Inc., MEDITECH (Medical Information Technology, Inc.), eClinicalWorks, LLC, Veradigm Inc., CareCloud, Inc., Teladoc Health, Inc., American Well Corporation (Amwell), Doximity, Inc., Hims & Hers Health, Inc., Microsoft Corporation, Koninklijke Philips N.V., InterSystems Corporation, Dedalus Group, CompuGroup Medical SE & Co. KGaA, Doctolib, Ping An Healthcare and Technology Company Limited, Surescripts, LLC |

Frequently Asked Questions
Some of the major companies operating in the eHealth Market include Epic Systems, Oracle Health, athenahealth, MEDITECH, eClinicalWorks, Veradigm, CareCloud, Teladoc Health, Amwell, Doximity, Hims & Hers, Microsoft, Philips, InterSystems, Dedalus, CompuGroup Medical, Doctolib, Ping An Healthcare and Technology, and Surescripts
Government funding and interoperability rules, together with the rising burden of chronic disease and the use of AI assistants to ease workforce shortages, are the key growth factors for the market.
By Product, the Electronic Health Records segment dominated the eHealth Market with approximately 36.75% share in 2025, because every hospital, clinic and physician practice needs a system of record for clinical, billing and regulatory data.
North America dominated the eHealth Market with a share of 41.33% in 2025, supported by high technology spending, near-universal electronic health record use and active policy on data exchange.
Key opportunities include AI tools that automate documentation and administrative work, middleware that connects different systems, home-based acute care supported by remote monitoring, and digital health programs in emerging markets across Asia Pacific, the Middle East, Africa and Latin America.
